
Introduction
Having a reliable van can make a significant difference to your business, whether you are a self-employed tradesperson, a delivery driver, or a growing company managing multiple jobs. However, purchasing a van outright is not always financially practical. This is where vehicle finance can provide a useful alternative, allowing you to spread the cost over an agreed period.
For drivers who have faced credit difficulties or have limited borrowing history, finding suitable finance can feel challenging. Guaranteed van finance in the UK is a popular search term among people looking for accessible vehicle funding. Understanding what these offers actually mean, how lenders assess applications, and which options are available can help you make a more informed decision.
What Is Van Finance and How Does It Work?
Van finance allows individuals and businesses to pay for a vehicle through scheduled instalments rather than covering the entire purchase price upfront. Depending on the agreement, you may pay a deposit followed by monthly payments over a specified term.
Several finance options are commonly available:
- Hire Purchase (HP): You pay towards the van in instalments and generally become its owner after completing the agreement and paying any applicable final fee.
- Personal Contract Purchase (PCP): You make monthly payments based on the vehicle's projected future value, with a final payment usually required if you want to own it.
- Personal Contract Hire (PCH): You lease the van for an agreed period and return it at the end, subject to the contract's conditions.
- Business van finance: Depending on eligibility, businesses and sole traders may access finance arrangements designed around their operational needs.
The right option depends on your budget, mileage requirements, business circumstances, and whether you want to own the vehicle.
Is Guaranteed Van Finance in the UK Really Possible?
It is important to understand the meaning behind the word "guaranteed" when researching vehicle finance. No responsible lender can promise approval to every applicant without assessing their circumstances.
Although some brokers advertise high approval rates or finance options for people with poor credit, acceptance generally depends on factors such as income, affordability, credit history, and the lender's criteria.
When exploring guaranteed van finance in the UK, look for providers that explain their eligibility requirements clearly instead of relying on unrealistic promises. A specialist broker may be able to introduce you to lenders whose criteria better match your circumstances.
Before applying, check whether the provider conducts a soft credit search initially and whether a full credit application could affect your credit file.
Can You Get Van Finance with Bad Credit?
Having a low credit score does not automatically mean you cannot obtain van finance. Lenders assess applications differently, and some consider applicants who have experienced previous financial difficulties.
Your chances may improve if you can demonstrate stable income, manageable existing commitments, and a realistic repayment plan.
Consider these practical steps before applying:
- Review your credit report: Check for inaccurate information and correct any errors before submitting an application.
- Set a realistic budget: Calculate how much you can comfortably afford each month.
- Consider a deposit: A deposit may reduce the amount you need to borrow, although it does not guarantee approval.
- Choose a suitable vehicle: A reasonably priced used van may result in more manageable repayments.
- Avoid multiple applications: Research providers carefully before submitting formal applications that could involve hard credit searches.
These measures can help you approach lenders with a clearer understanding of your financial position.
What Affects Your Monthly Van Finance Payments?
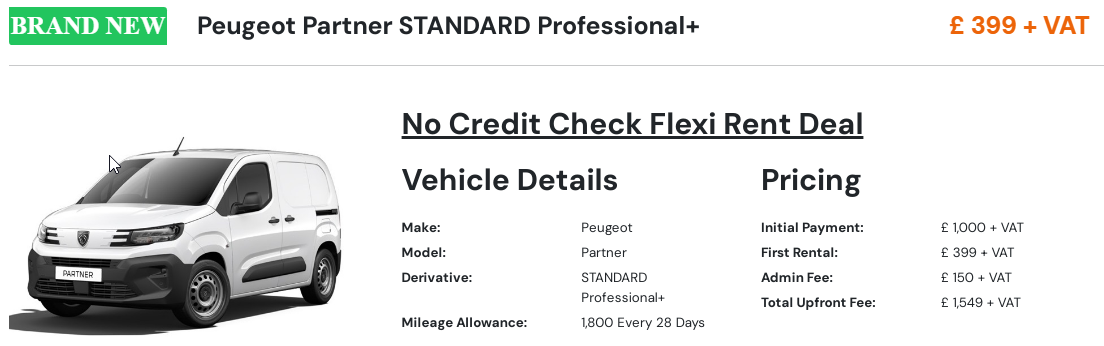
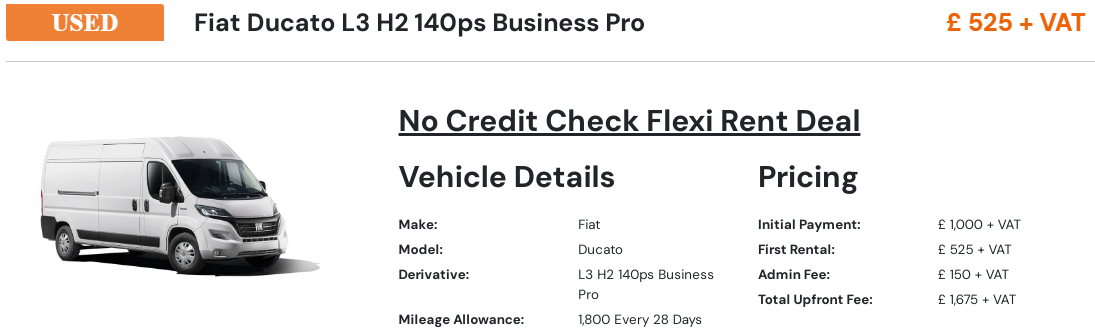
Your monthly payments depend on several factors, so comparing the headline repayment alone may not provide the complete picture.
The main considerations include:
- Vehicle price: More expensive vans generally require greater borrowing.
- Deposit amount: A larger deposit can reduce the outstanding finance.
- Agreement length: Longer terms may lower monthly payments but increase the total interest payable.
- Interest rate: The rate offered influences the overall cost of borrowing.
- Credit profile: Your financial history and circumstances may affect the available terms.
- Additional charges: Fees, mileage restrictions, maintenance obligations, and final payments can vary by agreement.
Always request a clear breakdown of the total amount payable, including interest and applicable fees, before committing.
How to Choose a Reliable Van Finance Provider
Finding suitable finance involves more than securing an initial approval. You should also consider the provider's reputation, transparency, and willingness to explain the agreement.
Look for lenders or brokers that clearly disclose their fees, explain the application process, and provide written information about repayment obligations. Check the Financial Conduct Authority's register where applicable to verify the firm's regulatory status and permissions.
Ask questions about early settlement, missed payments, vehicle ownership, and what happens if your circumstances change. If you are financing a van for business purposes, check whether the agreement suits your intended use.
Conclusion
Getting the right van finance can help you access a dependable vehicle without paying the full purchase price upfront. Although guaranteed van finance in the UK may sound appealing, approval is never something you should assume is automatic. Comparing suitable agreements, understanding the total cost, and assessing affordability are essential steps towards making a confident decision.
Take time to review your options, ask questions, and choose a finance agreement that supports your personal or business needs without placing unnecessary pressure on your finances.