
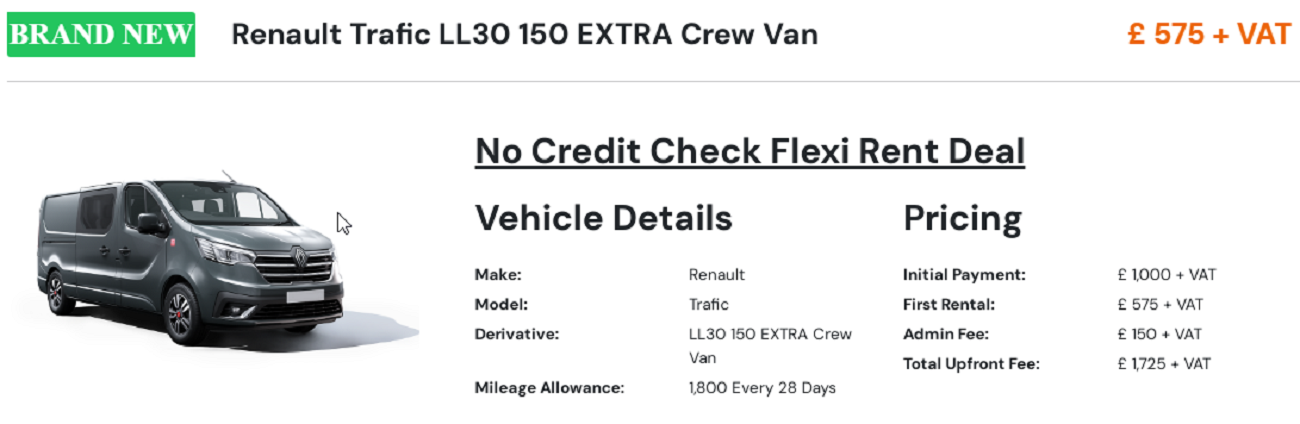
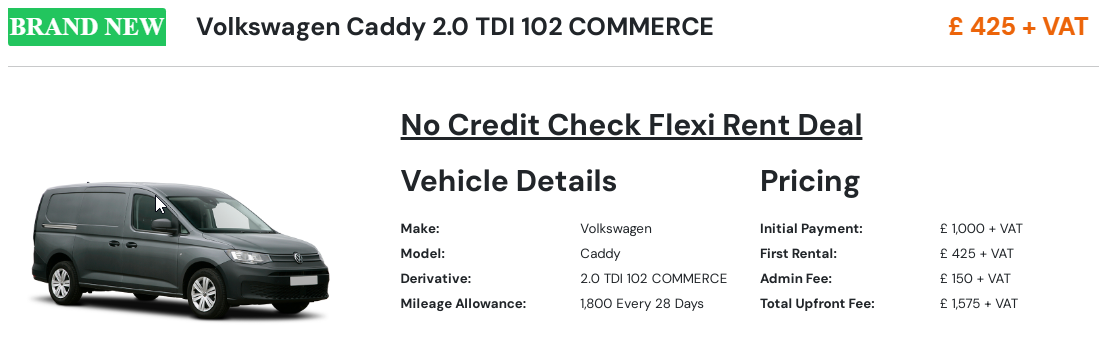
Running a business or starting a delivery service often requires a reliable vehicle, but financial hurdles can make that difficult. If your credit history isn’t perfect, you might think your options are limited. The good news is that van finance for bad credit is more accessible than ever, thanks to flexible lenders and tailored financing solutions.
Understanding Van Finance with Bad Credit
Bad credit doesn’t automatically disqualify you from getting vehicle financing. Many lenders today assess more than just your credit score—they consider your income, business potential, and ability to repay.
Van financing typically involves spreading the cost of the vehicle over monthly payments. Even with a low credit score, specialized lenders design plans that fit your financial situation, making it possible to get on the road without a large upfront investment.
Why Lenders Still Approve Applications
You might wonder why lenders would take the risk. The answer lies in structured financing and asset security. The van itself often acts as collateral, reducing the lender’s risk.
Here’s what lenders usually look for:
- Stable income or business revenue
- Proof of affordability
- A reasonable deposit (optional but helpful)
- Commitment to consistent repayments
By focusing on these factors, lenders can confidently offer van finance for bad credit to applicants who demonstrate financial responsibility in other ways.
Key Benefits of Financing a Van
Choosing financing instead of paying upfront comes with several advantages:
- Immediate access to a vehicle without large capital investment
- Improved cash flow for your business
- Opportunity to rebuild your credit score through timely payments
- Flexible repayment terms tailored to your budget
These benefits make financing an attractive option, especially for small business owners and self-employed individuals.
Tips to Improve Your Approval Chances
While approval is possible, taking a few smart steps can significantly boost your chances:
1. Check Your Credit Report
Before applying, review your credit file for errors. Correcting inaccuracies can slightly improve your score.
2. Save for a Deposit
Even a small deposit reduces the lender’s risk and may result in better terms.
3. Choose an Affordable Van
Opting for a reasonably priced vehicle increases the likelihood of approval and manageable repayments.
4. Work with Specialist Lenders
Some lenders specifically offer van finance for bad credit, making them more flexible than traditional banks.
Common Financing Options Available
Not all finance agreements are the same. Understanding your choices helps you pick the best fit:
- Hire Purchase (HP): You pay monthly installments and own the van at the end
- Lease Agreements: Lower monthly payments but no ownership
- Personal Contract Purchase (PCP): Flexible end-of-term options
Each option has its pros and cons, so it’s important to evaluate what aligns with your financial goals.
Mistakes to Avoid
When seeking van financing, steer clear of these common pitfalls:
- Applying for multiple loans at once (can harm your credit score)
- Ignoring the total cost of finance, not just monthly payments
- Overcommitting to high monthly installments
- Not reading the terms and conditions carefully
Avoiding these mistakes ensures a smoother financing experience and long-term financial stability.
Final Thoughts
Securing a van despite poor credit may seem challenging, but it’s far from impossible. With the right approach, preparation, and lender, you can find a deal that works for you. Whether you’re launching a new venture or expanding an existing one, van finance for bad credit provides a practical pathway to mobility and growth.
By staying informed and making smart financial decisions, you can not only acquire the vehicle you need but also take a step toward improving your overall credit profile.