
If you've ever applied for a business loan and gotten denied, or been asked to personally guarantee a credit card for your LLC, you're not alone, and you're not stuck. Most business owners never learn that business credit works in tiers, and skipping steps is the number one reason applications get rejected.
Here's the roadmap I use with my own companies and walk through in full on Money Moves With Mark.
FOUNDATION FIRST
Before any tier matters, your business needs to look like a real, separate legal entity to lenders and vendors. That means an EIN, a D-U-N-S number from Dun & Bradstreet, a dedicated business bank account, and a business address and phone number that aren't tied to your personal name. Skip this step and every tier below it will be harder to unlock, because lenders can't find a credit history to check.
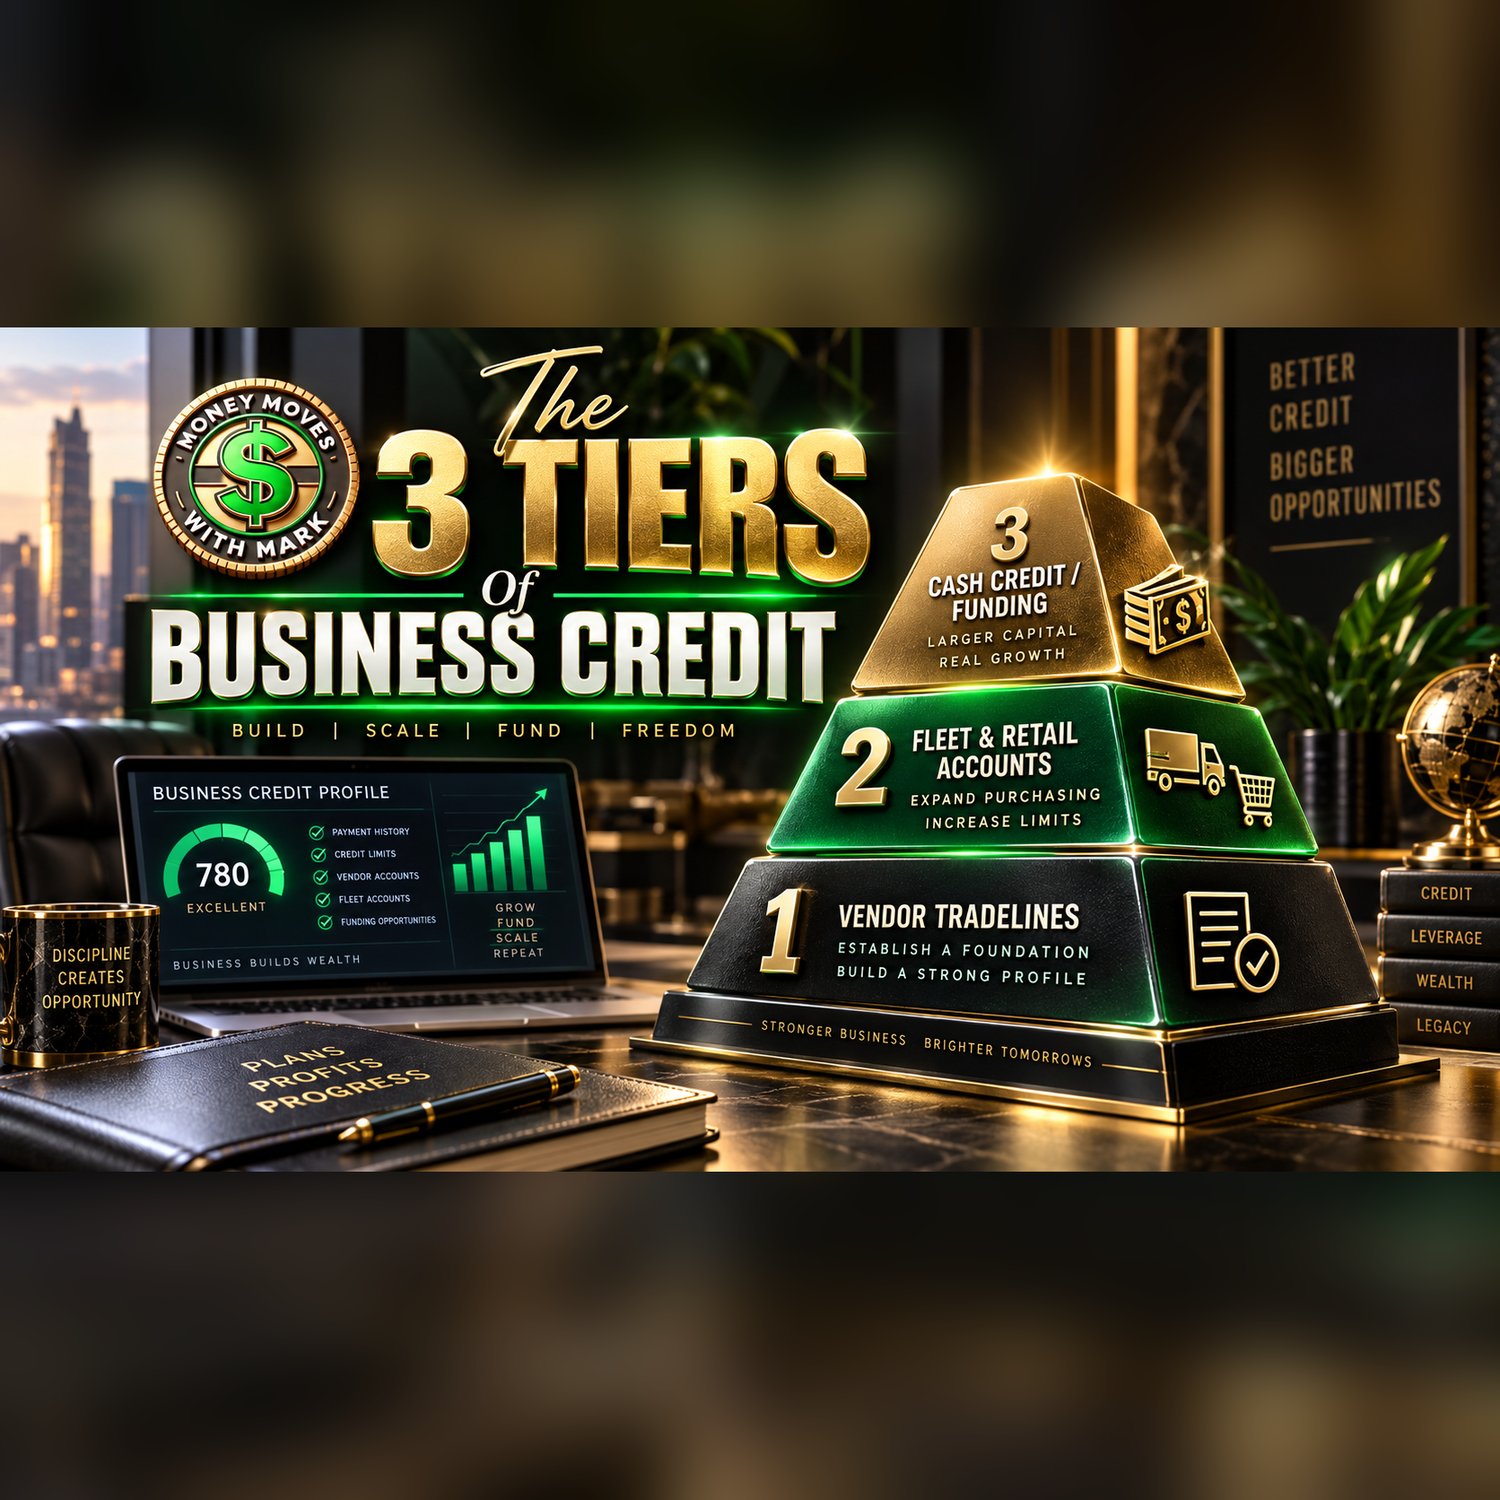
TIER 1: VENDOR TRADELINES
This is where business credit actually starts. Vendor tradelines are Net-30 accounts from companies like Uline, Quill, and Grainger that extend you short-term credit and then report your payment history to the business credit bureaus. Buy something small, pay it off on time, and you start building a credit profile for your EIN instead of your Social Security number. Three to five reporting tradelines paid on time is usually enough to move to the next tier.
TIER 2: FLEET AND RETAIL CREDIT
Once you've got tradelines reporting, you can qualify for fleet cards (think fuel and vehicle-related accounts) and retail store credit. These accounts usually come with higher limits and start training your business credit score, similar to a personal FICO score but for your EIN, which opens the door to real funding down the line.
TIER 3: NO PERSONAL GUARANTEE CREDIT
This is the goal. Cards from lenders like Ramp and Brex that don't require a personal guarantee, meaning your personal credit and personal assets aren't on the line if the business can't pay. Qualifying here takes a strong Tier 1 and Tier 2 foundation, consistent revenue, and clean business banking history. Once you're in, you're scaling on the business's credit, not yours.
THE MISTAKE THAT STALLS MOST PEOPLE
Applying for Tier 3 credit before the foundation and Tier 1 are in place. Lenders see a business with no credit history and no tradelines, and they either deny the application or require a personal guarantee anyway, which defeats the entire purpose. Build in order, and don't skip steps to save time.
If you want the full breakdown, including the exact vendors to start with and the mistakes that get people denied, I put it all together in The Tier System Guide, available now in the shop. Follow along on Money Moves With Mark for the video walkthroughs of each tier.