
The Refinance Break-Even Calculator Pack — Eight linked calculators, every formula checked by recalculation
Eight calculators for a loan you already have and an offer to replace it. Sheet 1 is the simple break-even; sheets 2 and 5 are the two things it leaves out -- the clock restarting at 30 years, and the balance you still owe when you sell. On the worked example the simple break-even is 19 months and the honest one is 25. Sheets 7 and 8 cover borrowing against the house. Every formula in this workbook was recalculated and checked against an independent implementation before it shipped; see the Verification sheet.
What is in it
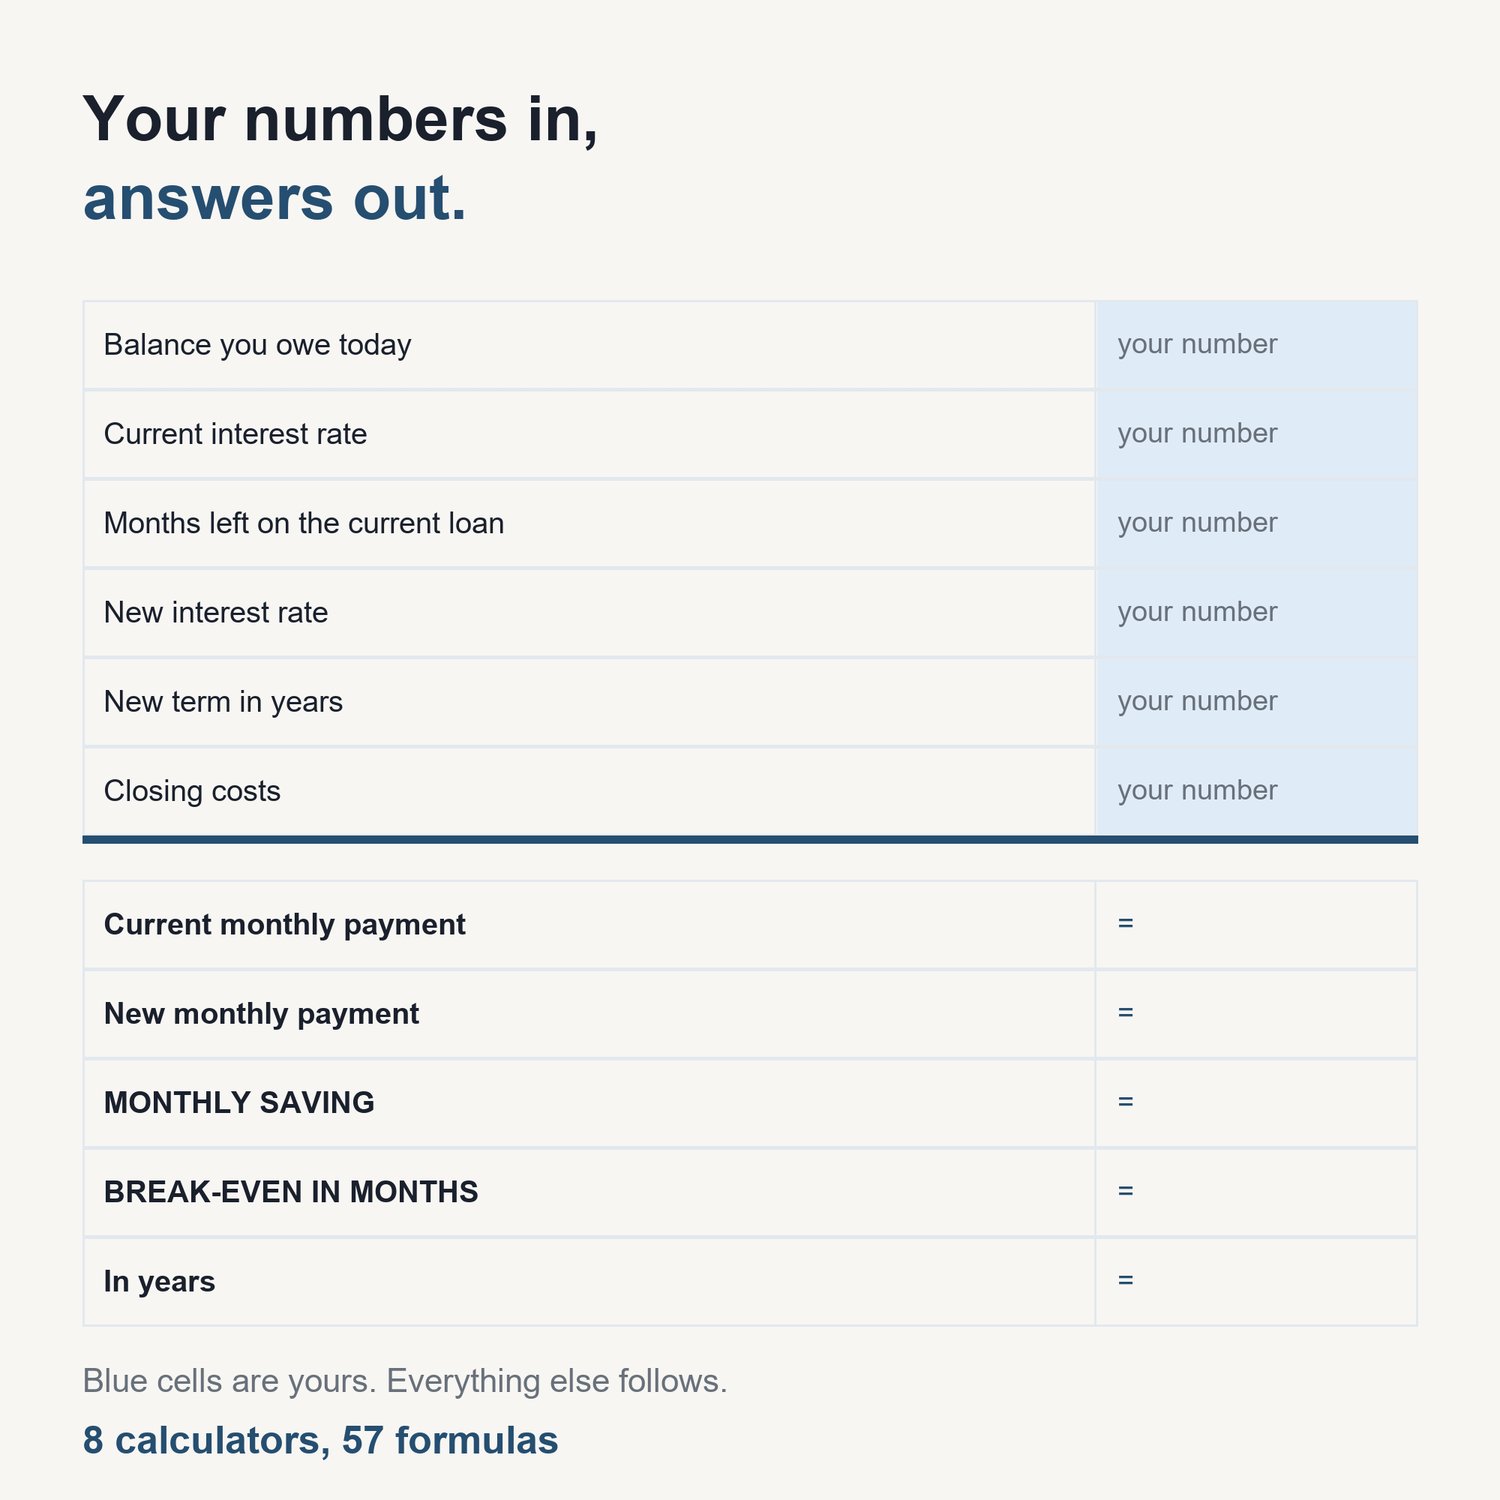
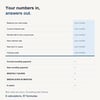
8 calculators, one per sheet. Overwrite the blue cells with your own numbers and everything else follows — nothing is locked, there are no macros, and it opens in Excel, Numbers, LibreOffice and Google Sheets.
- Break-even months — How many months of lower payments pay back the closing costs?
- Term-reset trap — Does a lower payment on a fresh 30 years cost more in total?
- Same-term refinance — What if the new loan ends on the same date as the old one?
- Costs rolled into the loan — What do closing costs cost if you borrow them instead of paying?
- Will you stay long enough — If you sell in a few years, does the refinance still pay?
- Rate drop you need — How low must the new rate be to break even in N years?
- Cash-out refinance — What does taking cash out of a refinance really cost?
- HELOC versus cash-out — Is a HELOC cheaper than a cash-out refinance for the same cash?
Every formula was checked
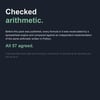
This pack contains 57 formulas. Before it was published, every one of them was recalculated by a spreadsheet engine and compared against an independent implementation of the same arithmetic written in Python. All 57 agreed to within a cent, and the workbook carries a Verification sheet saying so.
That is an unusual thing to be able to claim about a spreadsheet, and it is the main reason to buy this one rather than download a free template. A formula that looks right and is wrong is worse than no formula at all, because you will act on it.
What each calculator assumes
There is a sheet listing this, because a calculator that hides its assumptions is just a number generator:
- Principal and interest only. Taxes and insurance are the same either way, so they do not change the break-even.
- Both loans are paid to the end with no overpayments. If you will sell or refinance again first, sheet 5 is the better test.
- The lender will write a loan for the remaining term. Ask; if it will not, enter the nearest term it offers.
- The loan is paid to the end. Sold or repaid sooner, the extra interest is smaller, and the balance at sale is higher by whatever of the costs is still owed.
- A dollar now and a dollar at the sale are treated alike: no allowance for interest you could earn on the closing costs. The years until sale must be shorter than both loans.
- The new loan keeps your current payoff date, so the saving comes from the rate alone and not from a longer term.
- Both loans paid to the end with no overpayments, and dollars in different years treated alike.
- The HELOC rate is held fixed for illustration. If yours is variable, treat this as one scenario and rerun it at a higher rate. The whole amount is drawn on day one and only interest is paid during the draw period.
What this is not
Not financial, tax or legal advice, and not a recommendation to buy, sell, borrow or sign anything. These are calculators: they show what a choice costs, not which choice is right for you. Where a published rate or threshold is used it is the one current when the pack was built — those change, the arithmetic does not.
Honest about the format
One .xlsx workbook, 8 calculator sheets plus Start Here, Assumptions and Verification. Not a PDF, not a physical product, not a Notion template. Available immediately after purchase; nothing ships.
Refunds
If this isn't what you expected, email me within 30 days and I'll refund you in full — no need to explain. Because it's an instant download I can't take the file back, so I'd rather you just had your money back.