
Trump Account Employer Implementation Kit
Turn the new Trump Account employer rules into an implementation process your organization can actually use.
Employers may now make tax-advantaged contributions to Trump Accounts for employees or their dependents through a qualifying Section 128 Trump Account contribution program. But implementing a program involves more than simply sending a contribution.
The Syntera Systems Trump Account Employer Implementation Kit translates the new requirements into practical tools for HR, payroll, benefits, accounting, and management teams.
Your kit includes:
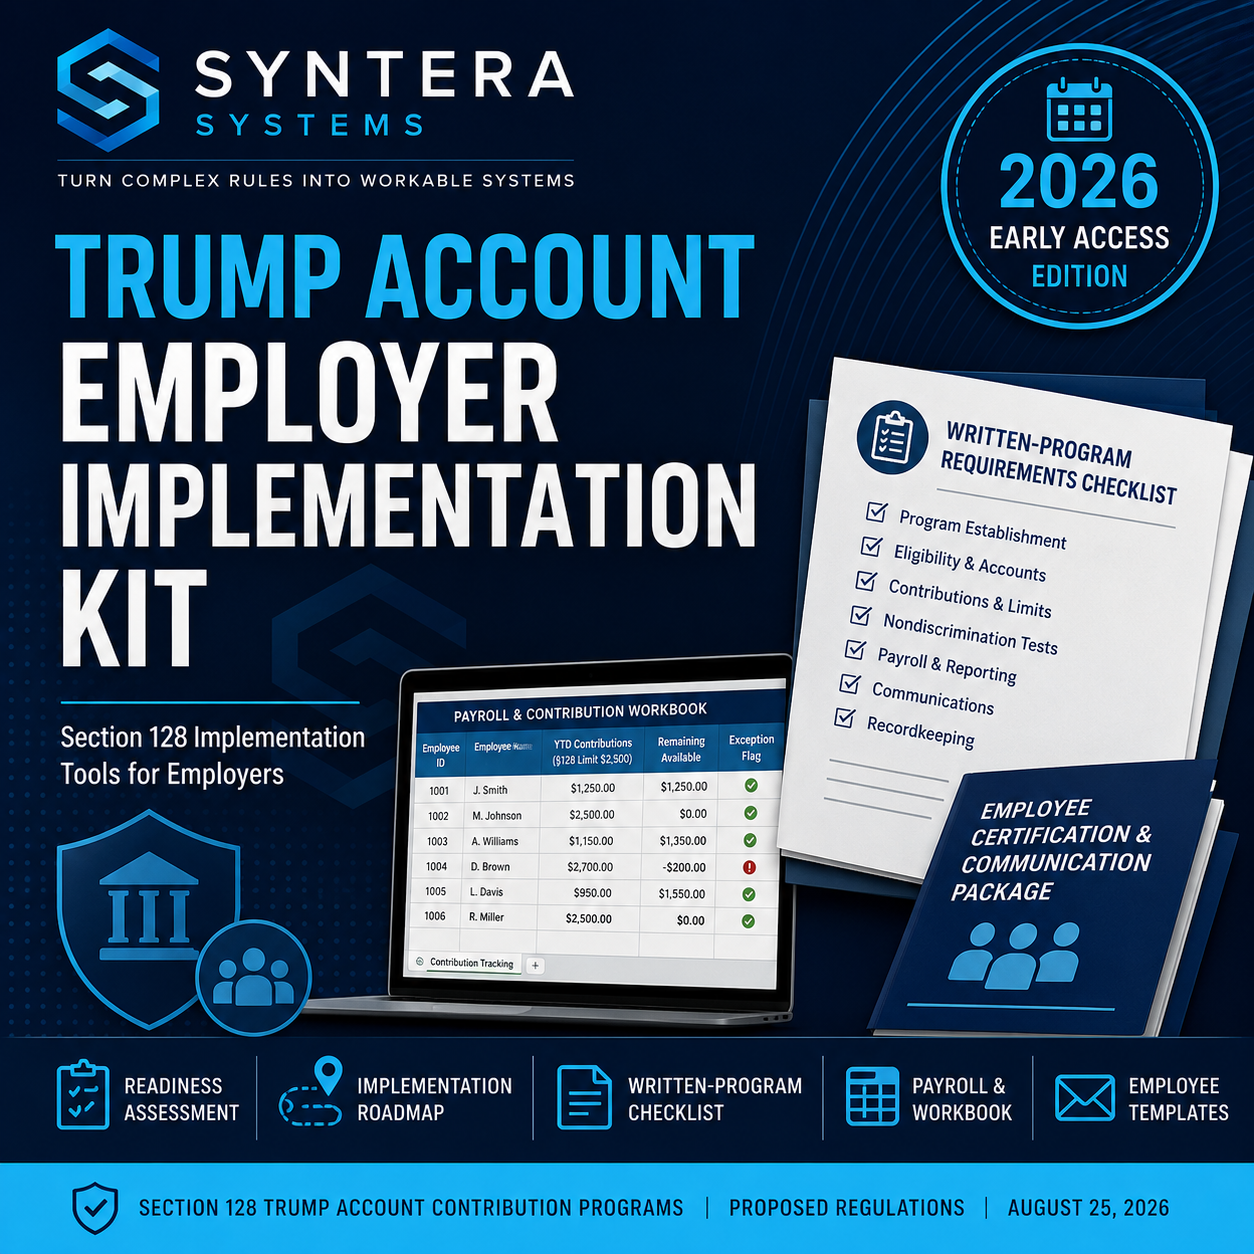
• Employer Readiness Assessment — evaluate whether your organization is prepared to establish and administer a Section 128 program.
• Implementation Roadmap — step-by-step guidance from program design through payroll setup, contributions, corrections, annual reporting, and ongoing administration.
• Written-Program Requirements Checklist — organize and document the required elements of the employer's written Trump Account contribution program.
• Payroll & Contribution Workbook — Excel-based administrative controls for employee-level contribution tracking, contribution-cycle reconciliation, exception flags, and year-end reporting support.
• Employee Certification & Communication Package — ready-to-customize certification, employee notice, and annual statement templates.
Built around the rules employers actually have to administer
The toolkit addresses key issues including the $2,500 annual Section 128 employee-level limit, account and beneficiary verification, nondiscrimination requirements, trustee communication, payroll controls, contribution corrections, employee notifications, and Form W-2 reporting using Box 12 Code TA.
Current IRS instructions confirm that employers may contribute up to $2,500 annually beginning July 4, 2026 under a qualifying Section 128 program and establish Code TA for W-2 reporting.
Early Access — $129
Sources checked October 11, 2026. This edition includes the September 30 temporary Section 530A account regulations, alongside enacted Section 128, IRS guidance, the August employer proposed regulations and correction, current W-2/W-3 instructions, and related DOL guidance.
Important regulatory status: The detailed Section 128 employer regulations remain proposed. Separate temporary Section 530A account rules are operative and affect account establishment, activation or claiming, provider evidence, and restrictions on unclaimed automatic accounts. Reassess the kit when final or superseding guidance is issued.
The five editable tools record receiving-account evidence, provider acceptance, conditional rollover-basis evidence, and input hold checks. The workbook preserves annual totals of entered amounts; an employer must reconcile provider/payroll records and complete annual-limit review before approving payment. Its review indicators are administrative records, not payment authorization or a final compliance determination.
Who this is for
Employers considering Trump Account contributions; HR and benefits professionals; payroll and accounting personnel; CPAs and business advisers assisting employers with implementation.
Important: This product provides educational, administrative, and implementation resources. It does not constitute legal, tax, investment, or individualized professional advice. Employers should evaluate their specific circumstances and obtain professional advice when appropriate.