
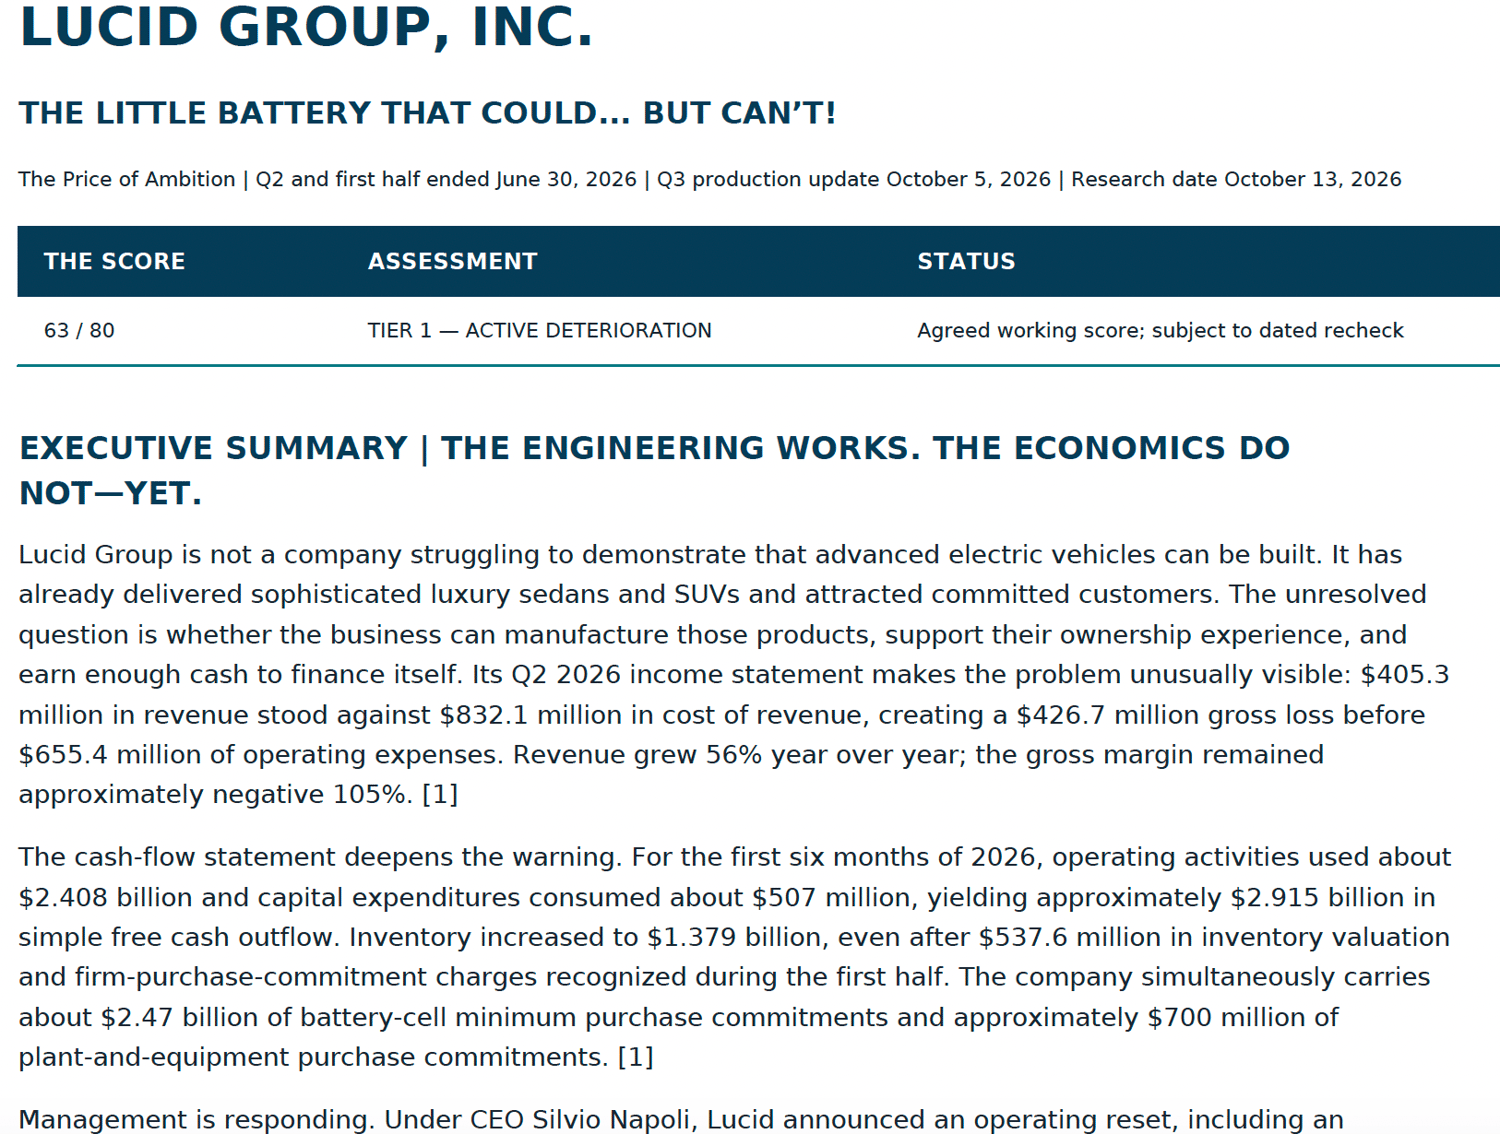
Vada Vista Full Analysis Lucid Group, inc Oct 2026
Lucid Group, Inc. (LCID): The Little Battery That Could… But Can't!
Vada Vista Financial Deep Dive | 63/80 — Tier 1: Active Deterioration
YouTube Video link
Lucid builds extraordinary luxury electric vehicles. But can it build a profitable and sustainable business worthy of those cars?
Lucid began as a battery and electric-powertrain technology company with an ambitious vision. Today, its luxury electric vehicles are admired for their engineering, performance, efficiency, and design. Yet behind those achievements, the financial statements reveal a troubling contradiction. In the second quarter of 2026, Lucid generated approximately $405 million in revenue against $832 million in cost of revenue—a gross loss of nearly $427 million. During the first six months of 2026, the company consumed approximately $2.91 billion in free cash flow. And the challenges extend beyond manufacturing costs. Lucid faces substantial inventory write-downs, billions in future battery-purchase commitments, underutilized manufacturing capacity, and continuing dependence on external financing.
How did an advanced technology company arrive at this financial position? And can new CEO Silvio Napoli build an organization worthy of Lucid's vehicles?
Inside This Vada Vista Investigation
This comprehensive financial analysis examines:
- Revenue and Manufacturing Economics: Why growing vehicle sales have not translated into positive gross margins.
- Operating Profitability: The financial burden of production, research, development, and operating expenses.
- Free Cash Flow: How much cash Lucid is consuming and what that means for future financing.
- Inventory and Supplier Commitments: The implications of inventory write-downs, excess production capacity, and approximately $2.47 billion in battery-cell purchase commitments.
- Balance Sheet and Liquidity: Cash, receivables, inventory, debt, preferred equity, and financial flexibility.
- Management's Turnaround Strategy: The operational changes underway and the financial results needed to demonstrate progress.
- Guidance and Expectations: The gap between Lucid's original ambitions, current production volumes, and financial performance.
- The Vada Vista Score: All eight deterioration measures, supporting evidence, and our final assessment.
The Score: 63/80 — Tier 1
Lucid is Vada Vista's first Tier 1 — Active Deterioration investigation.
But a Tier 1 score is not a prediction of bankruptcy or an automatic recommendation to sell or short the stock.
It identifies serious financial deterioration concerns that warrant careful analysis and ongoing monitoring.
The Central Question
Lucid has already demonstrated that it can engineer remarkable luxury electric vehicles. The next challenge is not simply producing more cars or reducing expenses. It is creating a business model that supports Lucid's luxury identity, serves its customers, and generates sustainable financial returns. Lucid does not need to become less than what it is. It needs a business worthy of its cars.
Discover the story behind the numbers with Vada Vista.
Research based primarily on Lucid's financial statements through June 30, 2026, and subsequent publicly reported operating developments through October 2026.
Vada Vista | The Score
Independent financial research and education. Not personalized investment advice.