
Student Load Pauses And What Capitalised Interest Costs
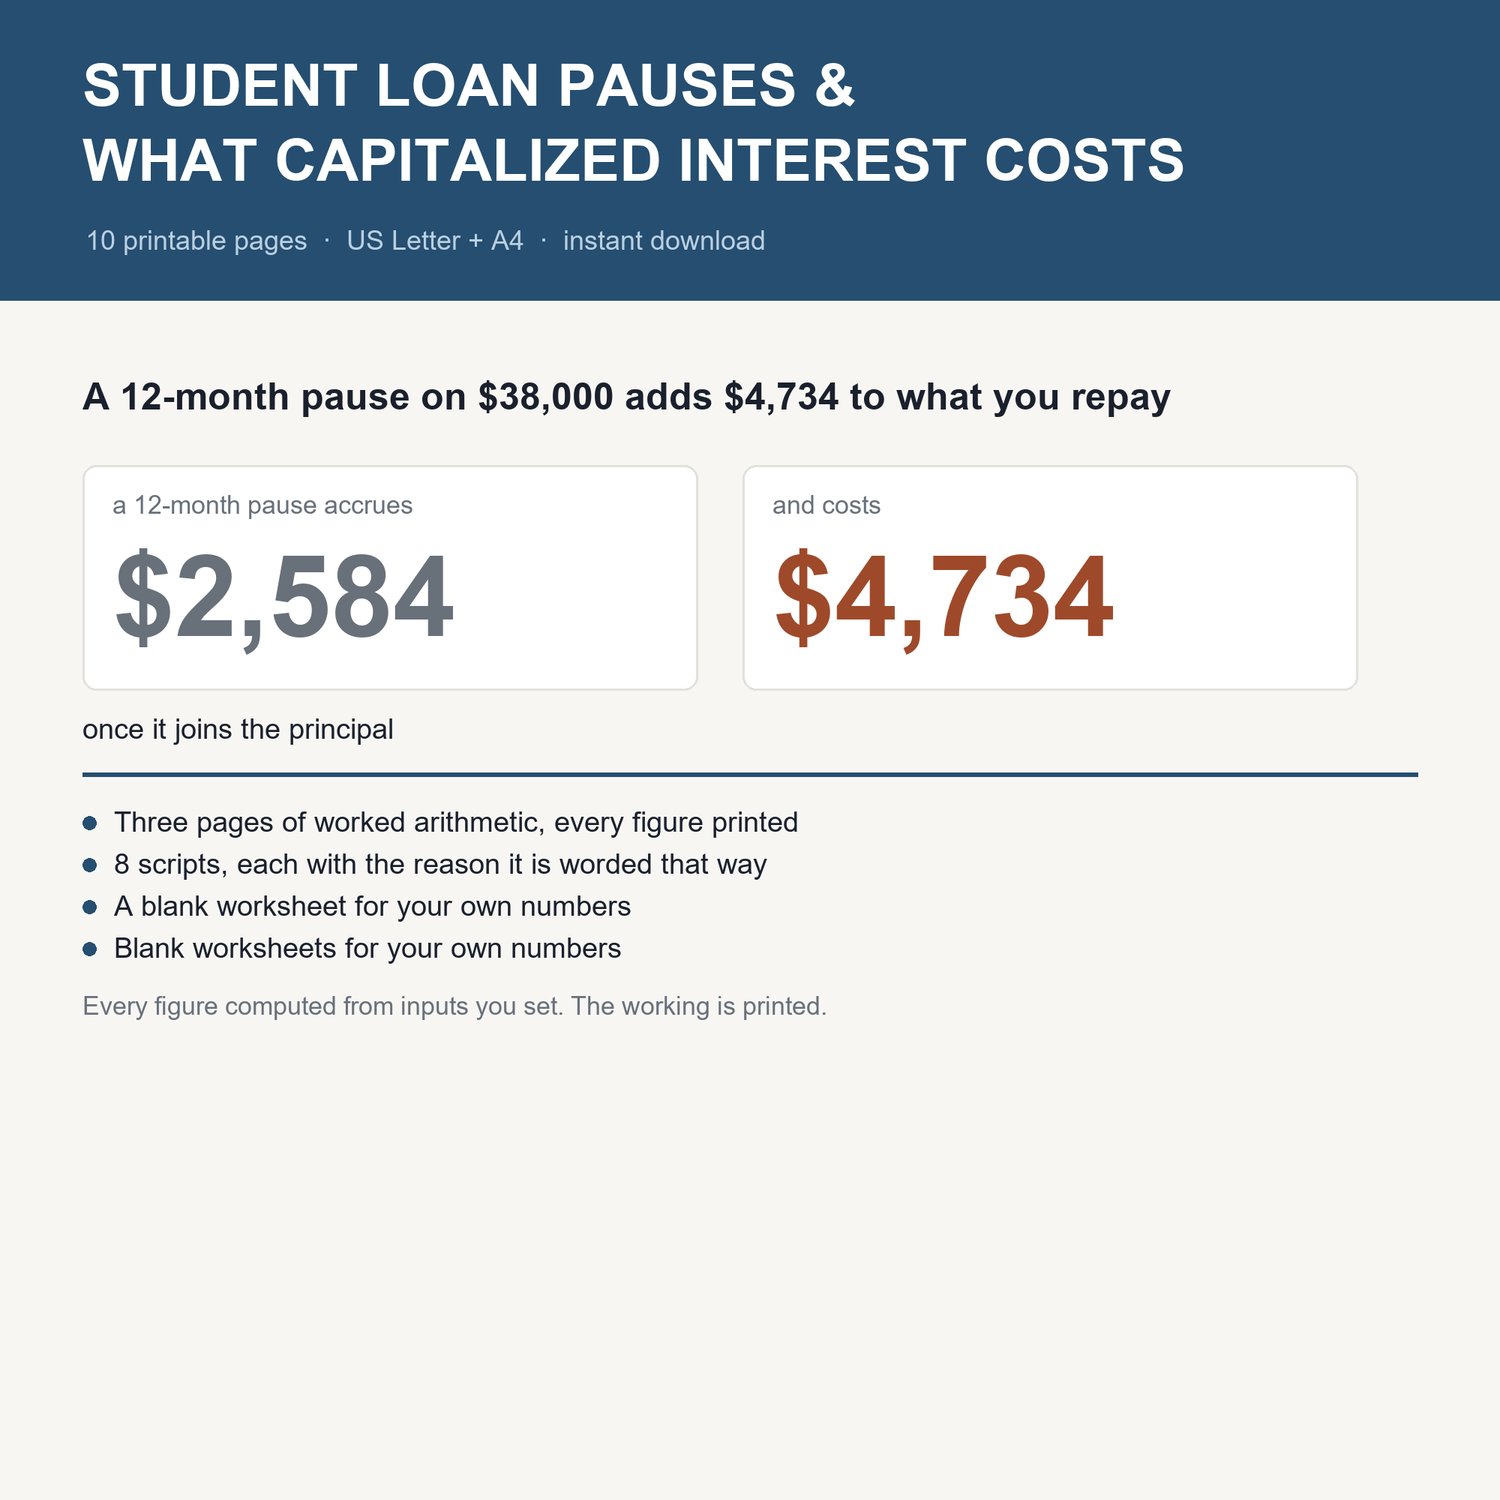
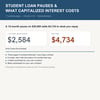
A pause does not freeze a student loan. Interest keeps accruing and, when the pause ends, it is added to the principal -- and from then on it earns interest itself. On $38,000 at 6.8%, a twelve-month pause accrues $2,584. Once that is capitalized and repaid over the remaining twenty years, the pause adds $4,734 to what you repay: the $2,584 itself plus $2,150 of interest on it. The pause was free in the month you took it and costs you for two decades afterwards.
A 12-month pause adds $4,734 to what you repay, not $2,584
A pause does not freeze a student loan. Interest keeps accruing, and when the pause ends it is added to the principal (capitalized) — at which point it stops being interest and becomes debt that earns interest of its own.
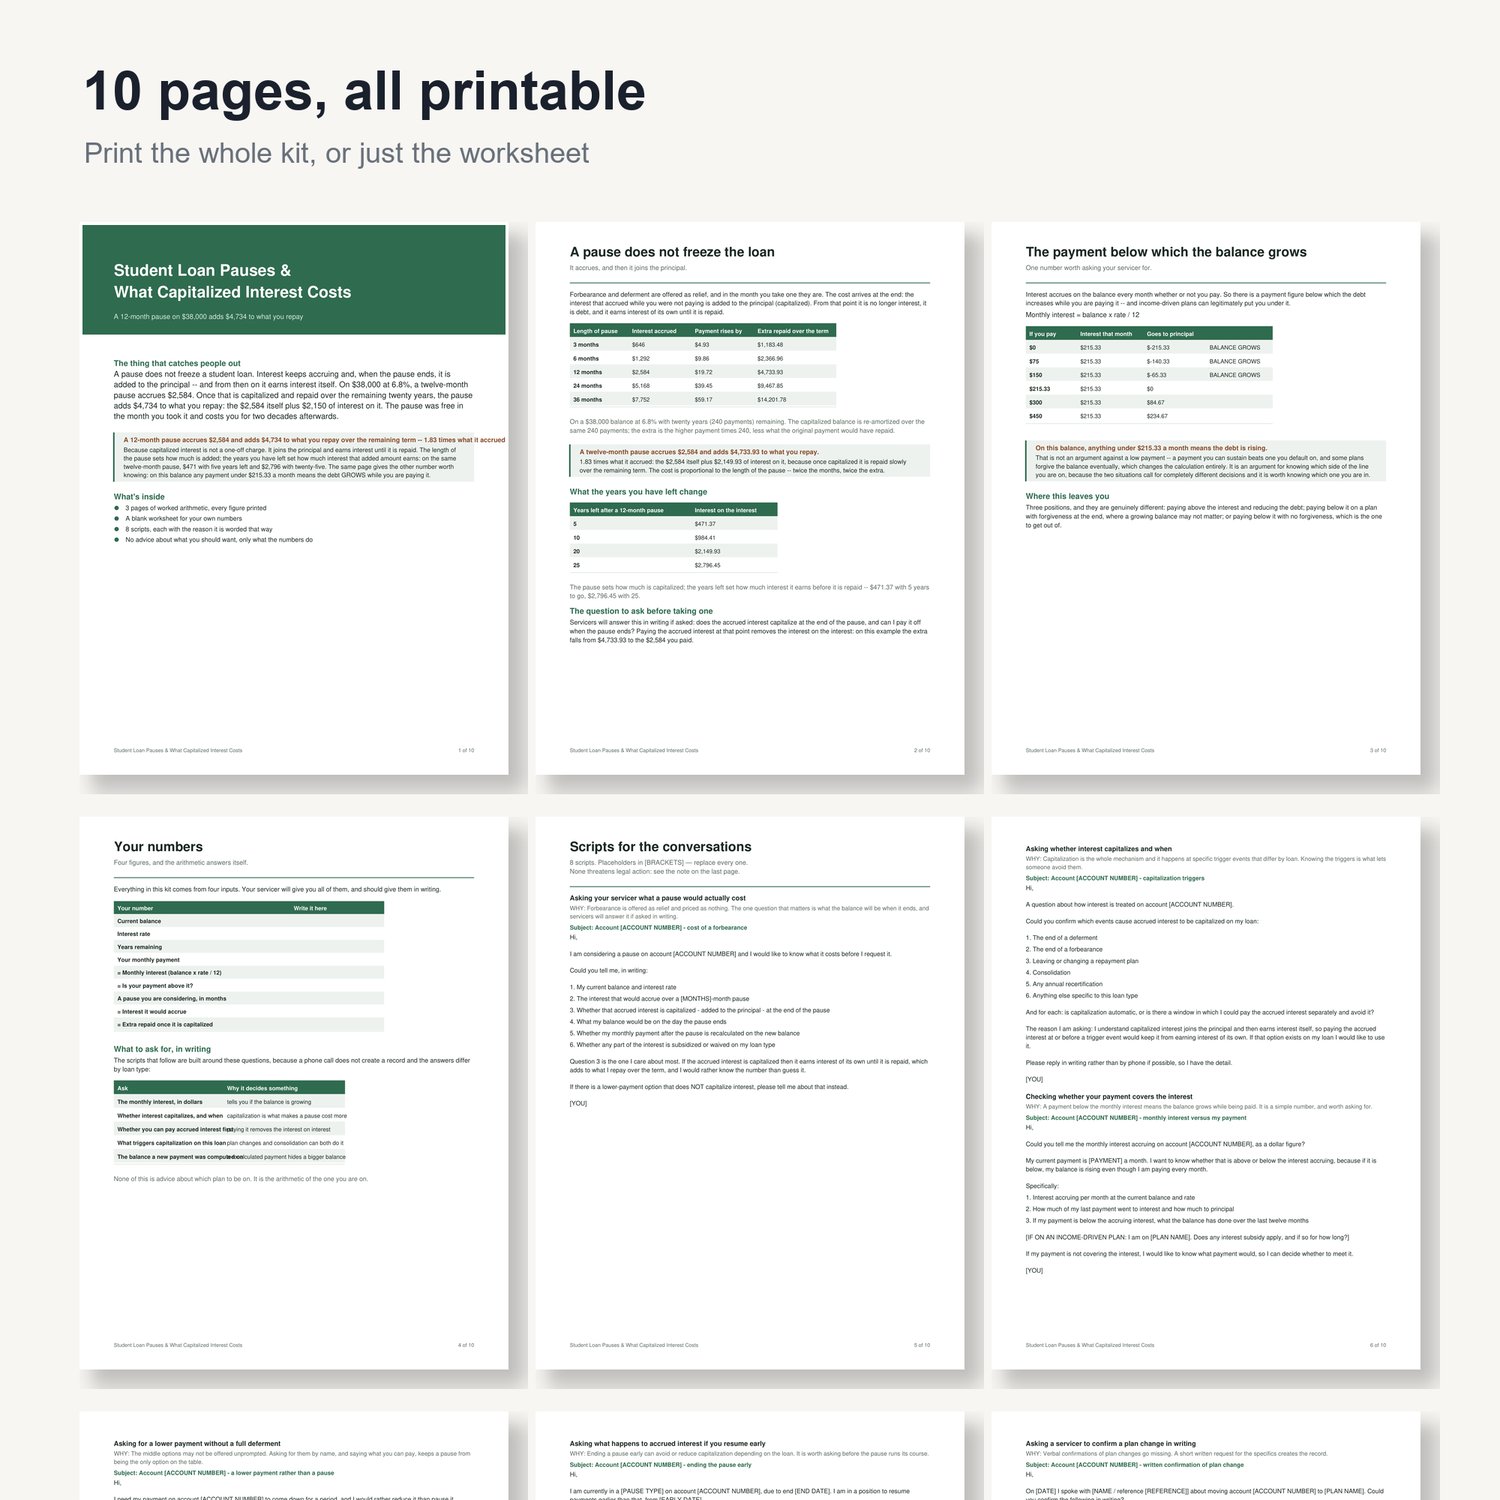
On $38,000 at 6.8% with twenty years left, a twelve-month pause accrues $2,584. Capitalized and repaid over the remaining 240 payments, it adds $4,733.93 to what you repay — 1.83 times what it accrued. Even a three-month break adds $1,183.48.
The length of the pause sets how much is capitalized; the years you have left set how much interest it earns. On the same twelve-month pause the interest on the interest is $471 with 5 years to go and $2,796 with 25.
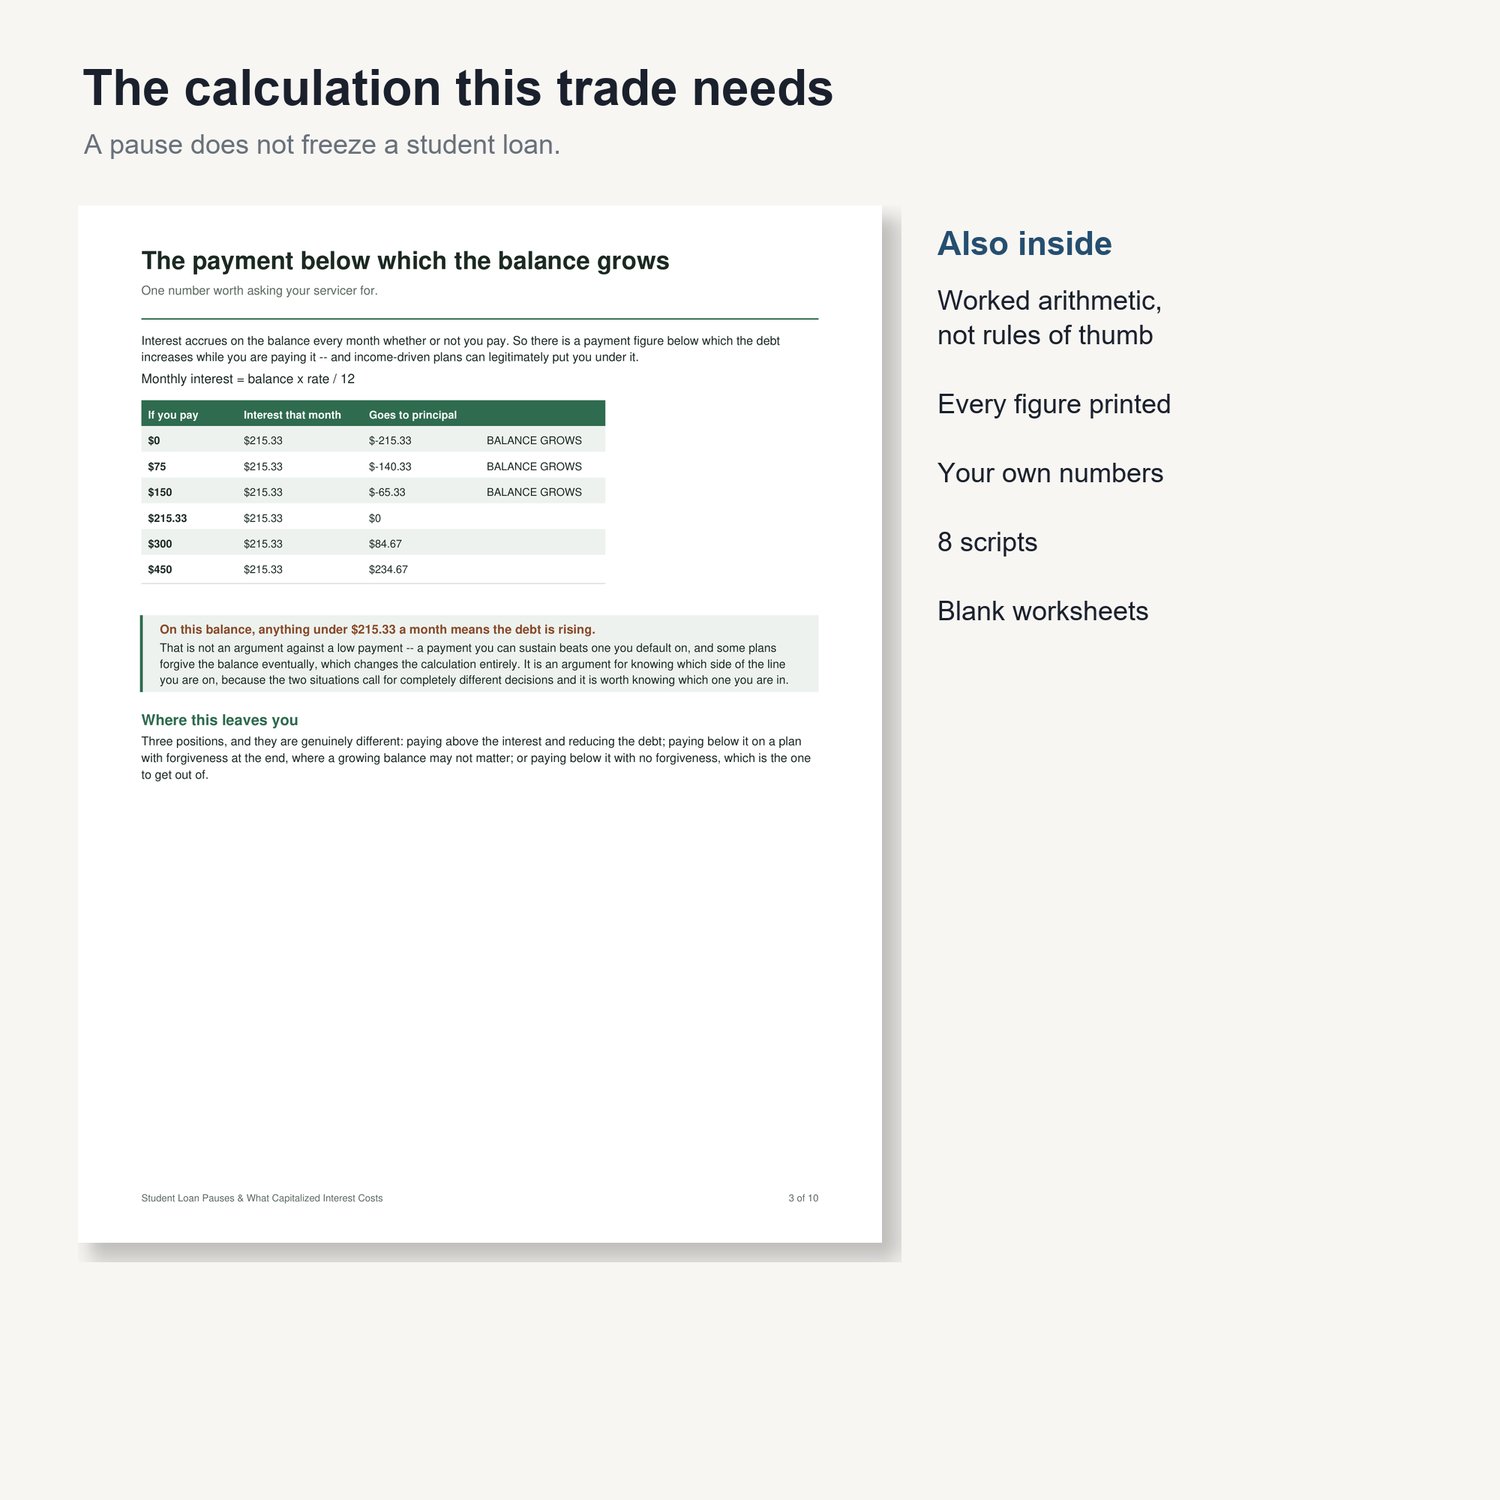
The other number worth knowing: on this balance, any payment under $215.33 a month means the debt grows while you are paying it. Income-driven plans can legitimately put you under that line, and the kit shows you how to tell which side you are on — because a growing balance with forgiveness at the end and a growing balance without it call for completely different decisions.
Includes a live Excel workbook — your balance, rate, term and payment, and it reports your monthly interest, whether the balance is growing, and what a pause would cost. Every formula verified by recalculation. Plus eight scripts for the servicer conversations: what a pause would cost, whether interest capitalizes and when, and whether you can pay accrued interest before it does.
Not financial advice. Arithmetic about the loan you already have.
8 scripts for the conversations this involves
Each one carries a line explaining why it is worded that way, because
a script you do not understand is one you will not send. Placeholders are in
[BRACKETS] so nothing goes out in someone else's words.
- Asking your servicer what a pause would actually cost
- Asking whether interest capitalizes and when
- Checking whether your payment covers the interest
- Asking for a lower payment without a full deferment
- Querying a balance that went up after a pause
- Asking what happens to accrued interest if you resume early
- Telling family why you are not pausing despite the offer
- Asking a servicer to confirm a plan change in writing
What this is not
This is arithmetic, not advice. Every figure is computed from
the inputs stated on the page, and the working is printed so you can substitute
your own. What it cannot tell you is what you should want — it shows what a
choice costs, not which choice is right for your household.
Nothing here is financial, tax or legal advice, and it is not a recommendation
to buy, sell, borrow or sign anything. The scripts are wording for a
conversation, not legal instruments, and none of them threatens anything.
Where the kit uses a published rate or threshold, it is the one current when
the kit was built. Those change; the arithmetic does not.
Honest about the format
Printable PDFs plus an editable Excel workbook, not a physical product. One US Letter PDF (10 pages) and one A4 PDF (10 pages), and one .xlsx that opens in Excel, Numbers, LibreOffice and Google Sheets. Files are available immediately after purchase; nothing ships.
Refunds
If this isn't what you expected, email me within 30 days and I'll refund you in full — no need to explain. Because it's an instant download I can't take the files back, so I'd rather you just had your money back.