
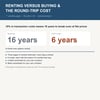
Renting Versus Buying & The Round-Trip Cost — 10% in transaction costs means 16 years to break even at flat prices
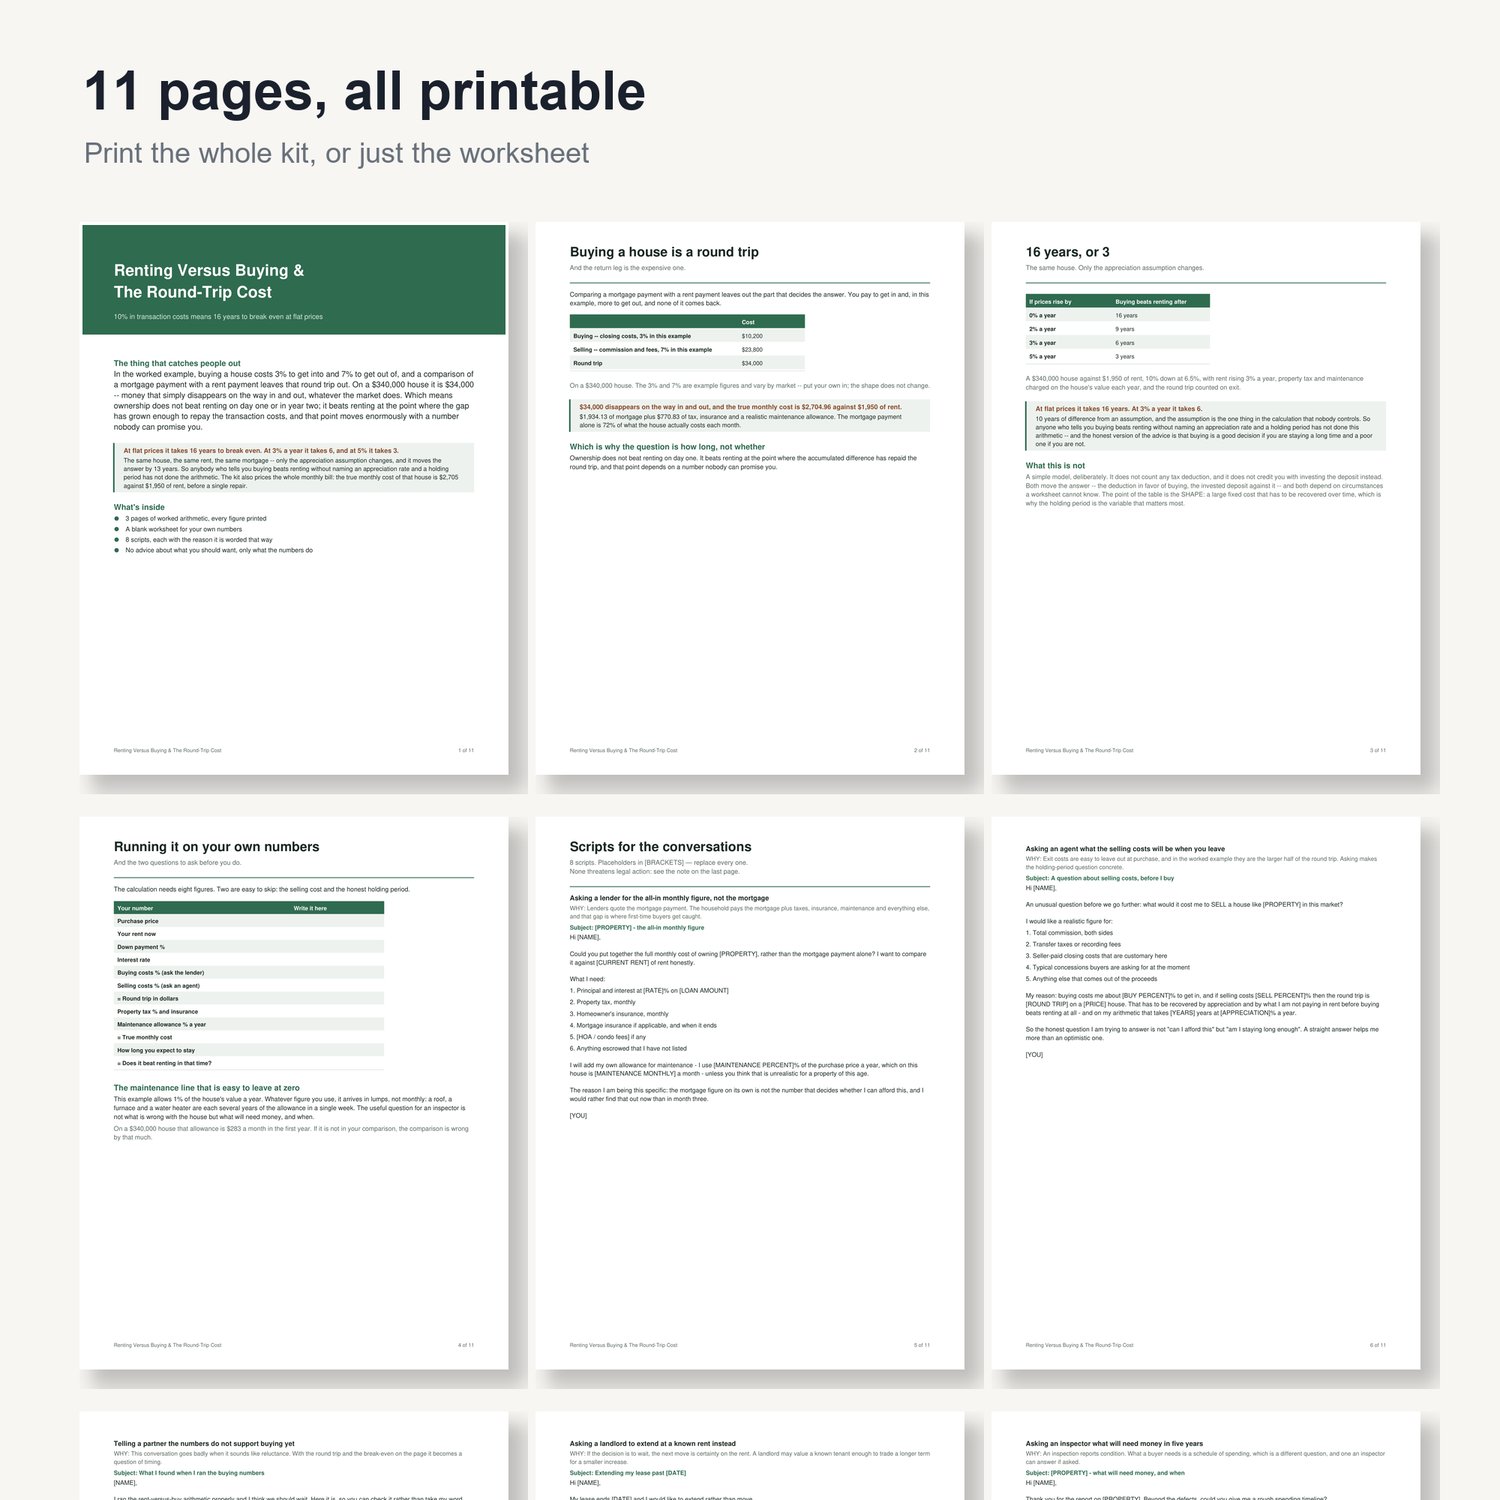
In the worked example, buying a house costs 3% to get into and 7% to get out of, and a comparison of a mortgage payment with a rent payment leaves that round trip out. On a $340,000 house it is $34,000 -- money that simply disappears on the way in and out, whatever the market does. Which means ownership does not beat renting on day one or in year two; it beats renting at the point where the gap has grown enough to repay the transaction costs, and that point moves enormously with a number nobody can promise you.
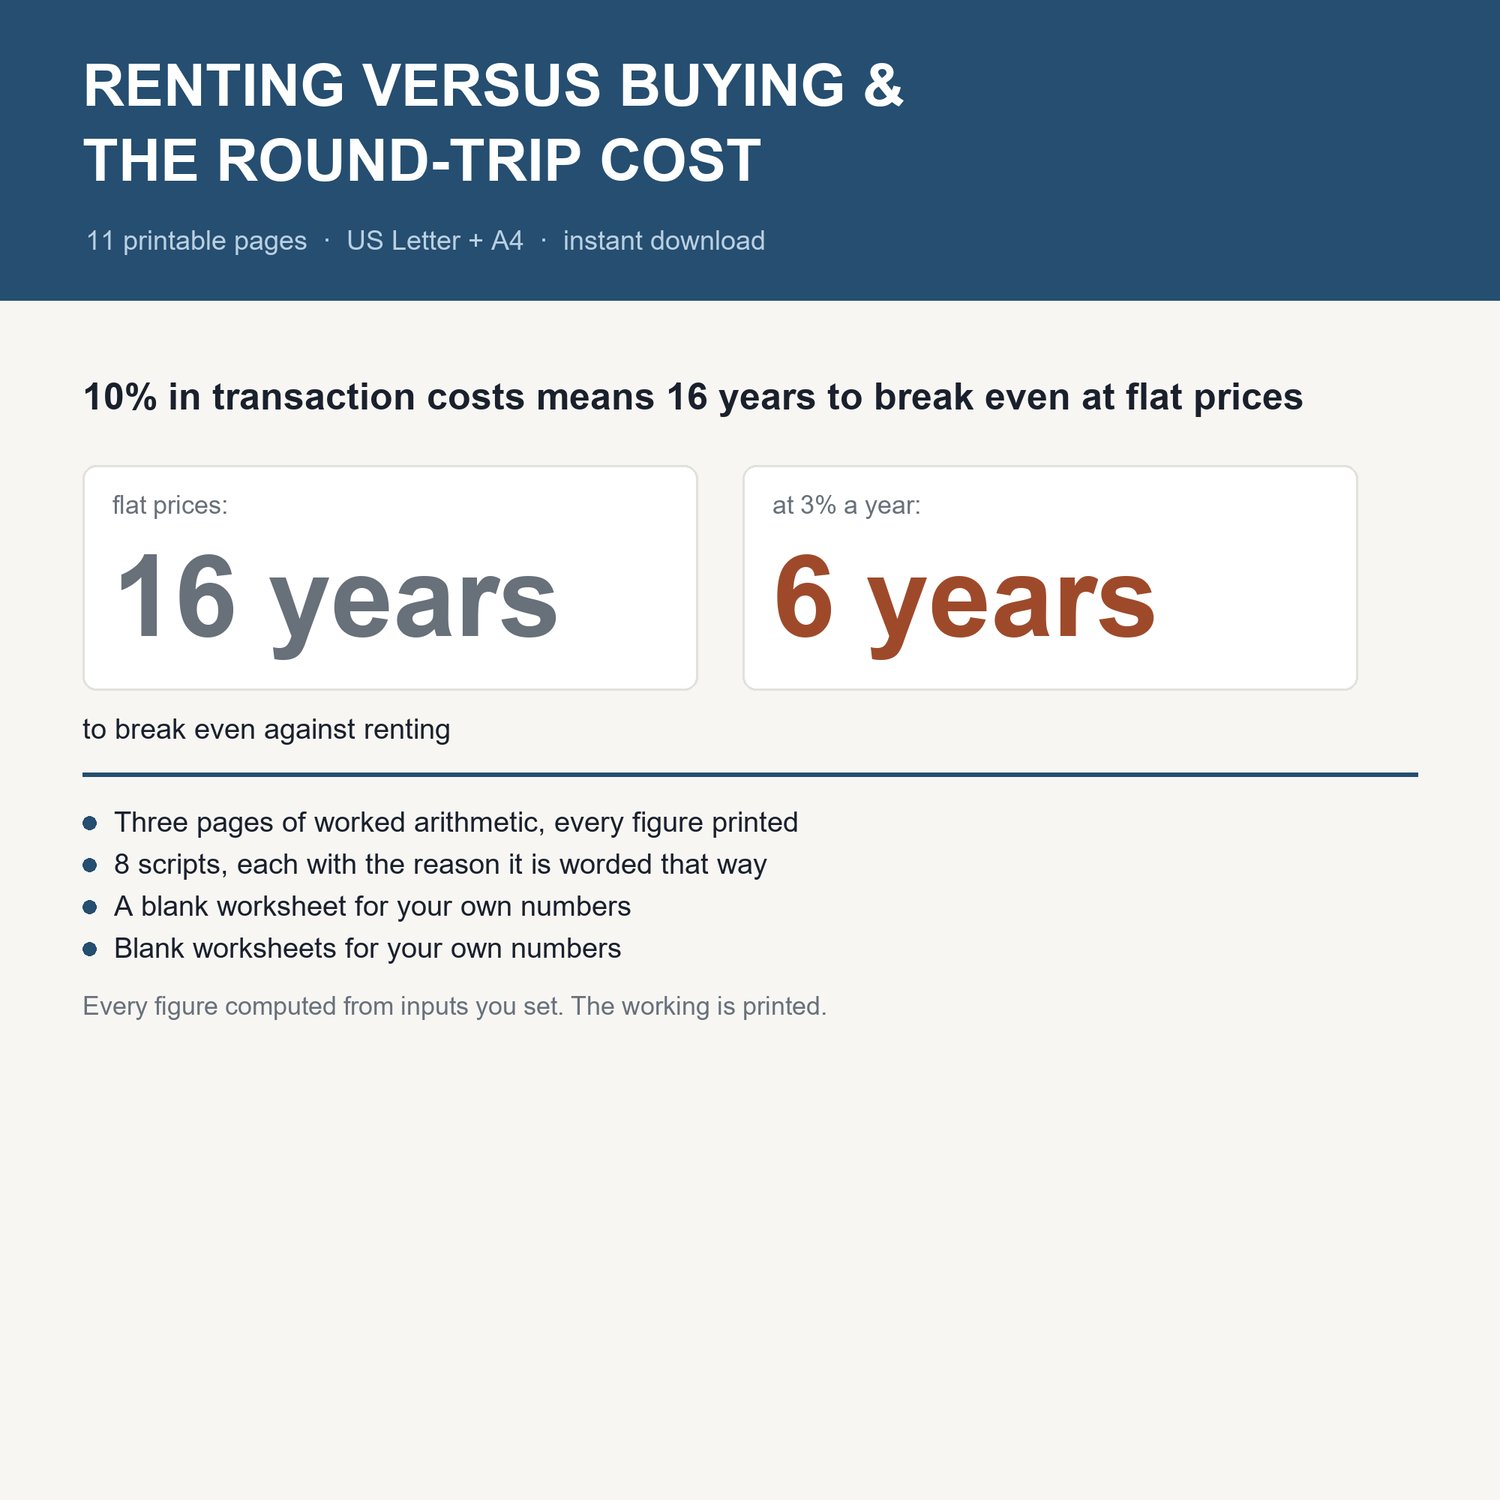
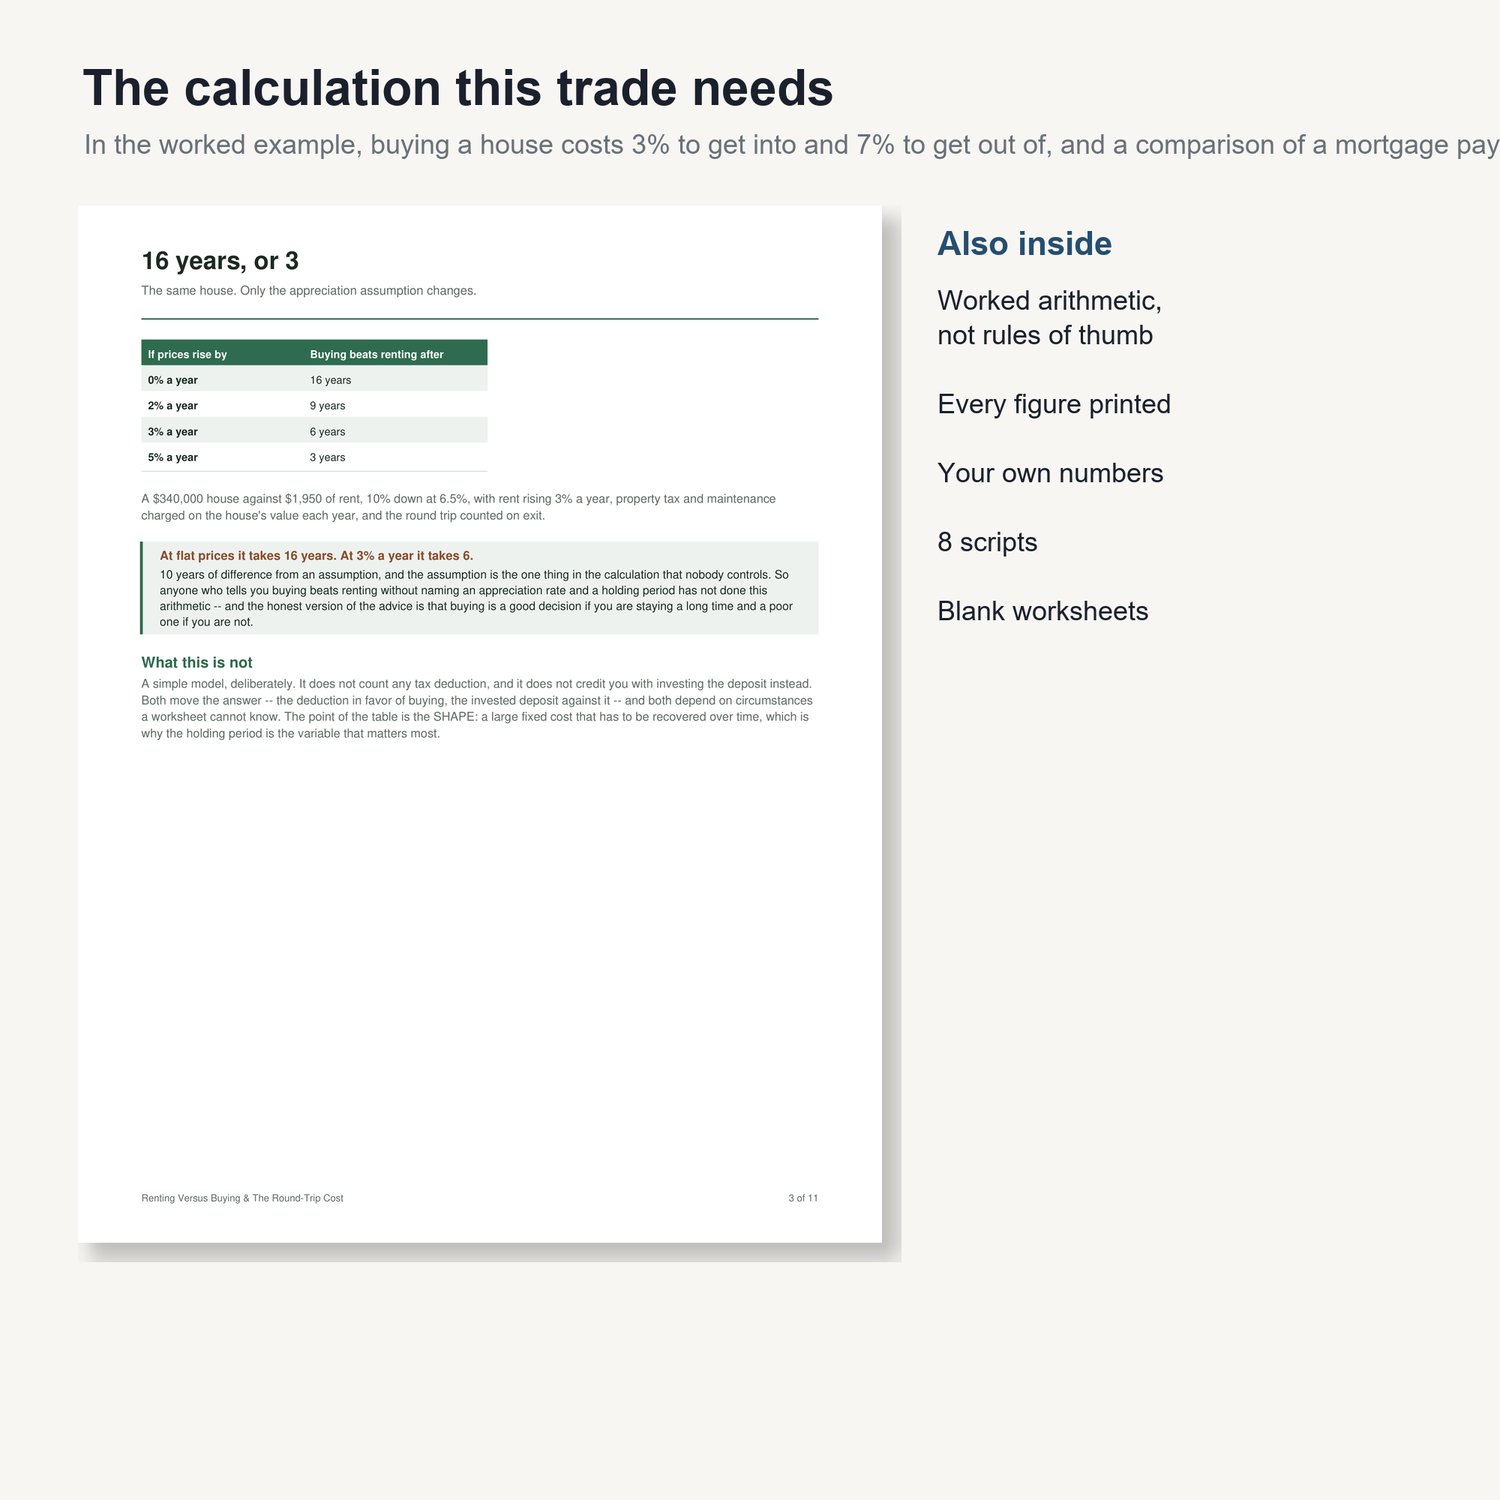
16 years to break even, or 3
Comparing a mortgage payment with a rent payment leaves out the part that decides the answer. In the worked example buying costs 3% to get into and 7% to get out of (example figures — they vary by market) — on a $340,000 house that is $34,000 that simply disappears, whatever the market does.
And the monthly comparison is wrong too. That house costs $2,704.96 a month all in — $1,934.13 of mortgage plus $770.83 of tax, insurance and a realistic maintenance allowance — against $1,950 of rent. The mortgage payment is 72% of what the house actually costs.
So the question is not whether buying beats renting but WHEN. At flat prices it takes 16 years. At 3% a year, 6 years. At 5%, 3. 13 years of difference from an assumption nobody controls — which is why anyone who tells you buying always beats renting has not done this arithmetic.
The kit is honest about what it leaves out: no tax deduction, and no credit for investing the deposit instead. Both move the answer and both depend on circumstances a worksheet cannot know. What it gives you is the shape — a large fixed cost that has to be recovered over time, which makes your holding period the variable that matters most.
Includes a live Excel workbook and eight scripts — asking a lender for the all-in monthly figure rather than the mortgage, asking an agent what selling will cost before you buy, declining to stretch to the top of your approval, and asking family offering a deposit what they expect in return.
Not financial advice.
8 scripts for the conversations this involves
Each one carries a line explaining why it is worded that way, because a script you do not understand is one you will not send. Placeholders are in [BRACKETS] so nothing goes out in someone else's words.
- Asking a lender for the all-in monthly figure, not the mortgage
- Asking an agent what the selling costs will be when you leave
- Telling a partner the numbers do not support buying yet
- Asking a landlord to extend at a known rent instead
- Querying a good-faith estimate that grew
- Asking an inspector what will need money in five years
- Declining to stretch to the top of your approval
- Asking family offering a deposit what they expect in return
What this is not
This is arithmetic, not advice. Every figure is computed from the inputs stated on the page, and the working is printed so you can substitute your own. What it cannot tell you is what you should want — it shows what a choice costs, not which choice is right for your household.
Nothing here is financial, tax or legal advice, and it is not a recommendation to buy, sell, borrow or sign anything. The scripts are wording for a conversation, not legal instruments, and none of them threatens anything.
Where the kit uses a published rate or threshold, it is the one current when the kit was built. Those change; the arithmetic does not.
Honest about the format
Printable PDFs plus an editable Excel workbook, not a physical product. One US Letter PDF (11 pages) and one A4 PDF (11 pages), and one .xlsx that opens in Excel, Numbers, LibreOffice and Google Sheets. Files are available immediately after purchase; nothing ships.
Refunds
If this isn't what you expected, email me within 30 days and I'll refund you in full — no need to explain. Because it's an instant download I can't take the files back, so I'd rather you just had your money back.