
Granny Flat CGT & Main Residence Checker (Australia) – Partial Exemption, Cost Base, 50% Discount and Tax for Each Owner (Excel)
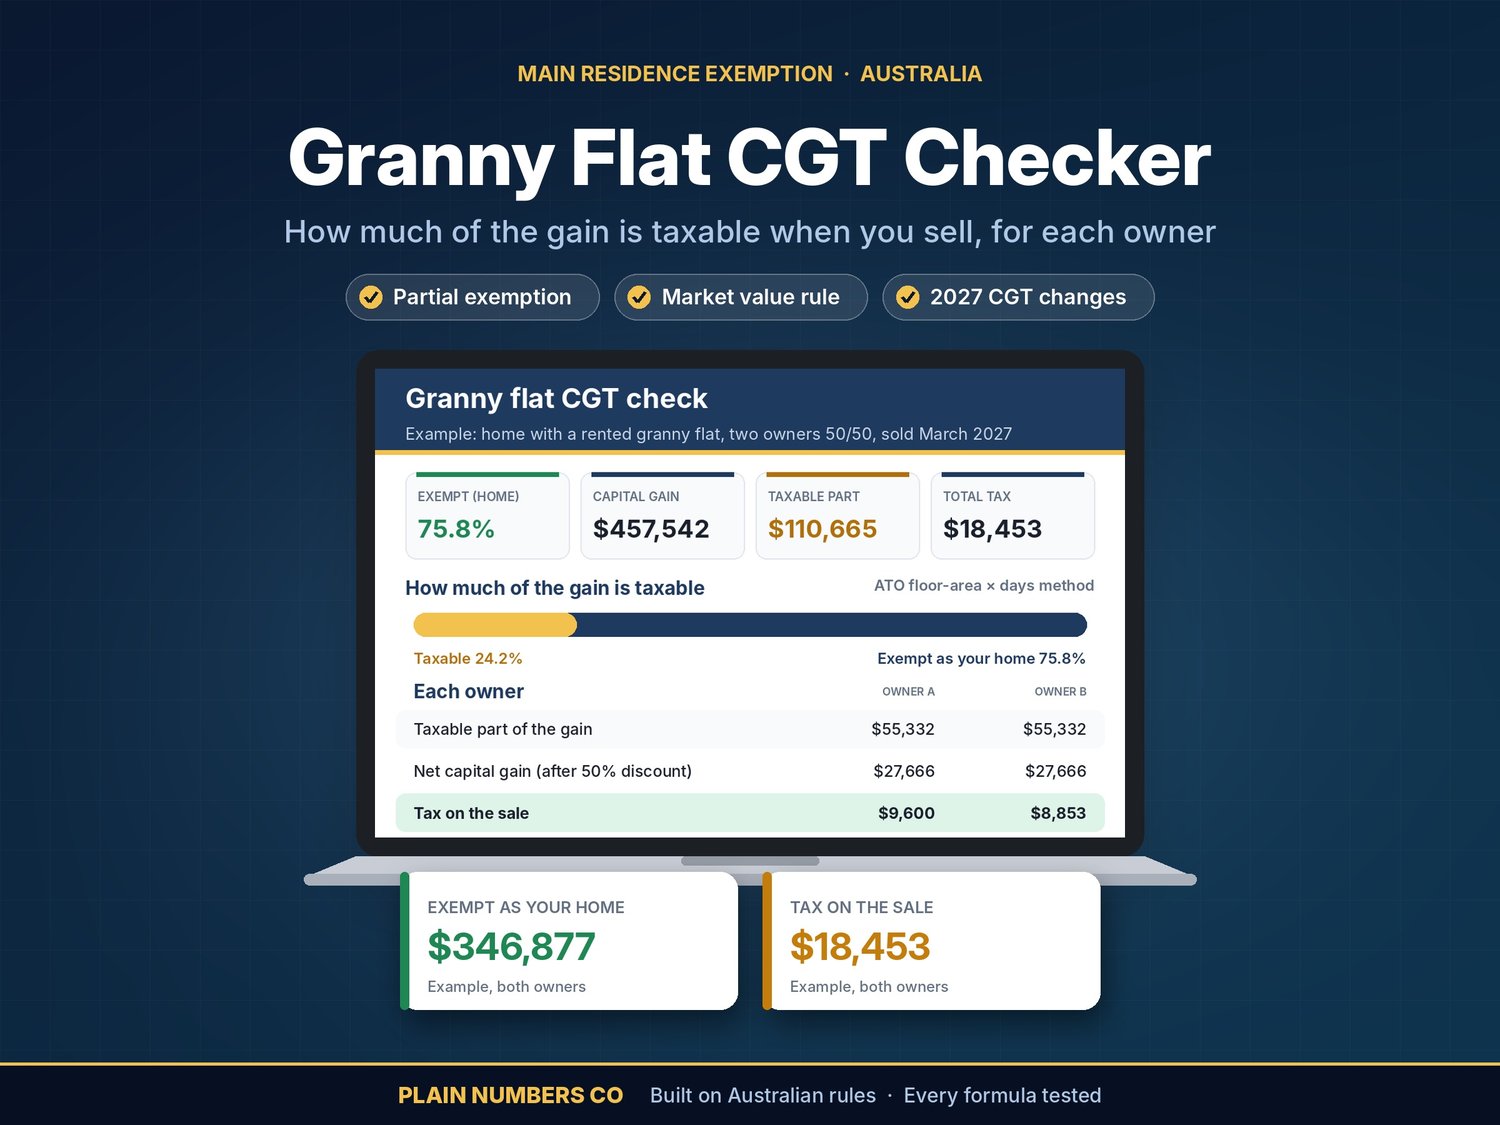
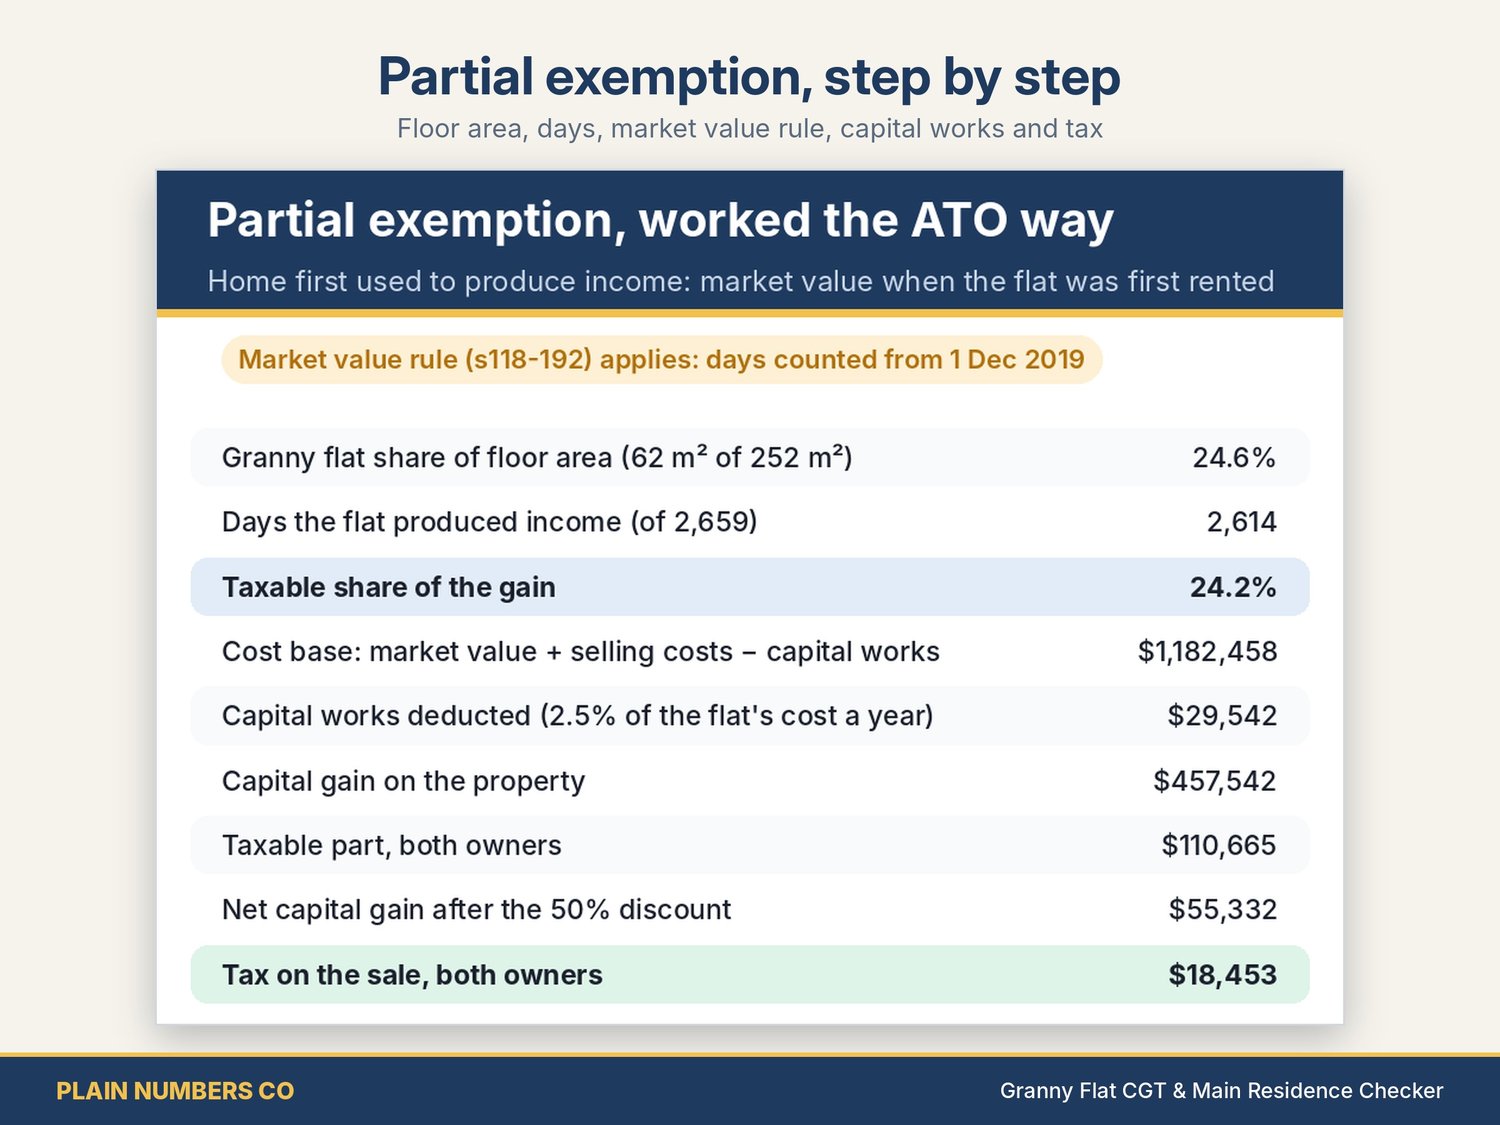
Find out how much of the gain is taxable when you sell a home with a granny flat, or a house and granny flat that are both rented, and roughly how much tax each owner will pay. The workbook applies the ATO's own method: the granny flat's share of the floor area, multiplied by the days it produced income, divided by the days you owned the home.
Enter the dates, prices, the flat's cost and floor area, and each owner's share and income. The workbook shows:
- Full, partial or no main residence exemption for each owner, with the exempt and taxable shares of the gain.
- The "home first used to produce income" rule (s118-192), applied automatically when your home was first rented out after 20 August 1996: the market value on that date becomes the cost base and the day count starts again. This rule isn't optional, and it can raise or lower your gain.
- The cost base, including the granny flat's construction cost, less the capital works deductions (2.5% a year) that you could claim. These reduce the cost base whether or not you claimed them. It estimates the flat's deductions, or you can enter your own.
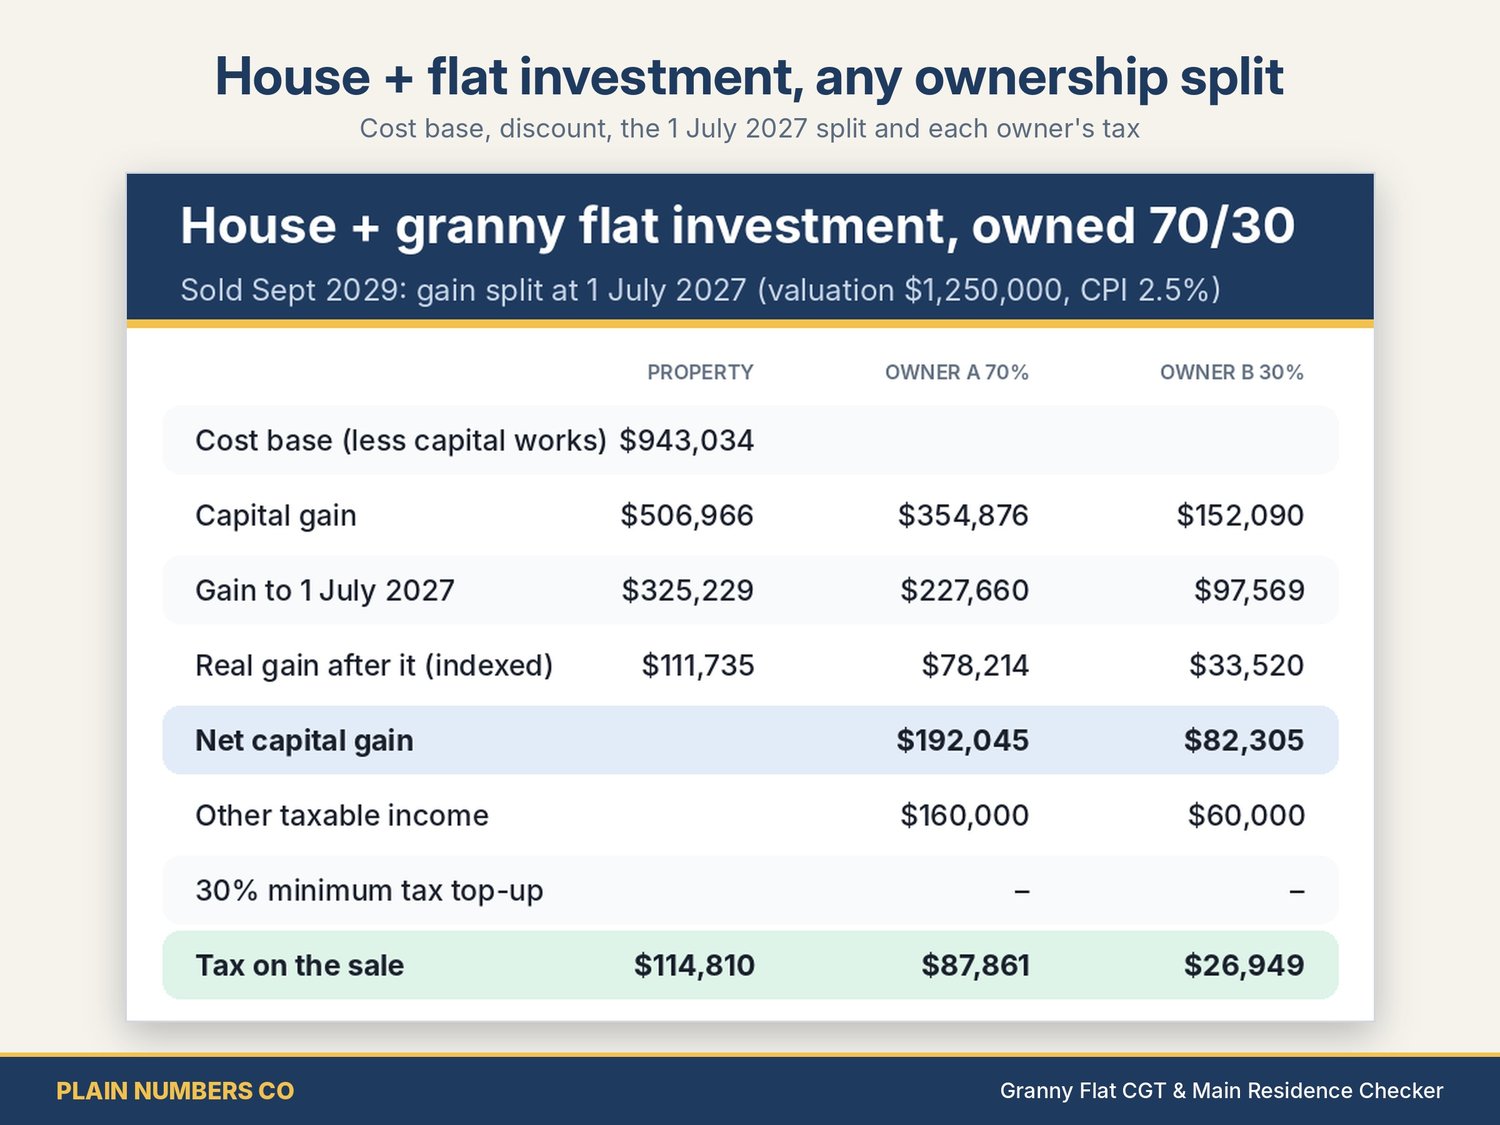
- The 50% CGT discount (held at least 12 months), capital losses and the net capital gain for each owner, with any ownership split (50/50, 70/30 and so on).
- Tax on the sale at each owner's marginal rate, using the current resident rates for the year of the sale (2025-26, 2026-27, or the legislated 14% rate from 2027-28), the low income tax offset and the Medicare levy.
- Sales on or after 1 July 2027 of a fully rented property: the gain is split at 1 July 2027. The part before keeps the 50% discount. The part after is indexed for inflation (once you've owned the property 12 months, counted from the day you bought it, as the ATO says), with the 30% minimum tax top-up, as the ATO describes the Treasury Laws Amendment (Tax Reform No. 1) Act 2026. Pre-CGT property (bought before 20 September 1985) stays exempt for gains up to 1 July 2027. You enter a valuation at 1 July 2027 and your own CPI assumption. The government's alternative "apportionment method" isn't law yet; the workbook labels its estimate as not legislated.
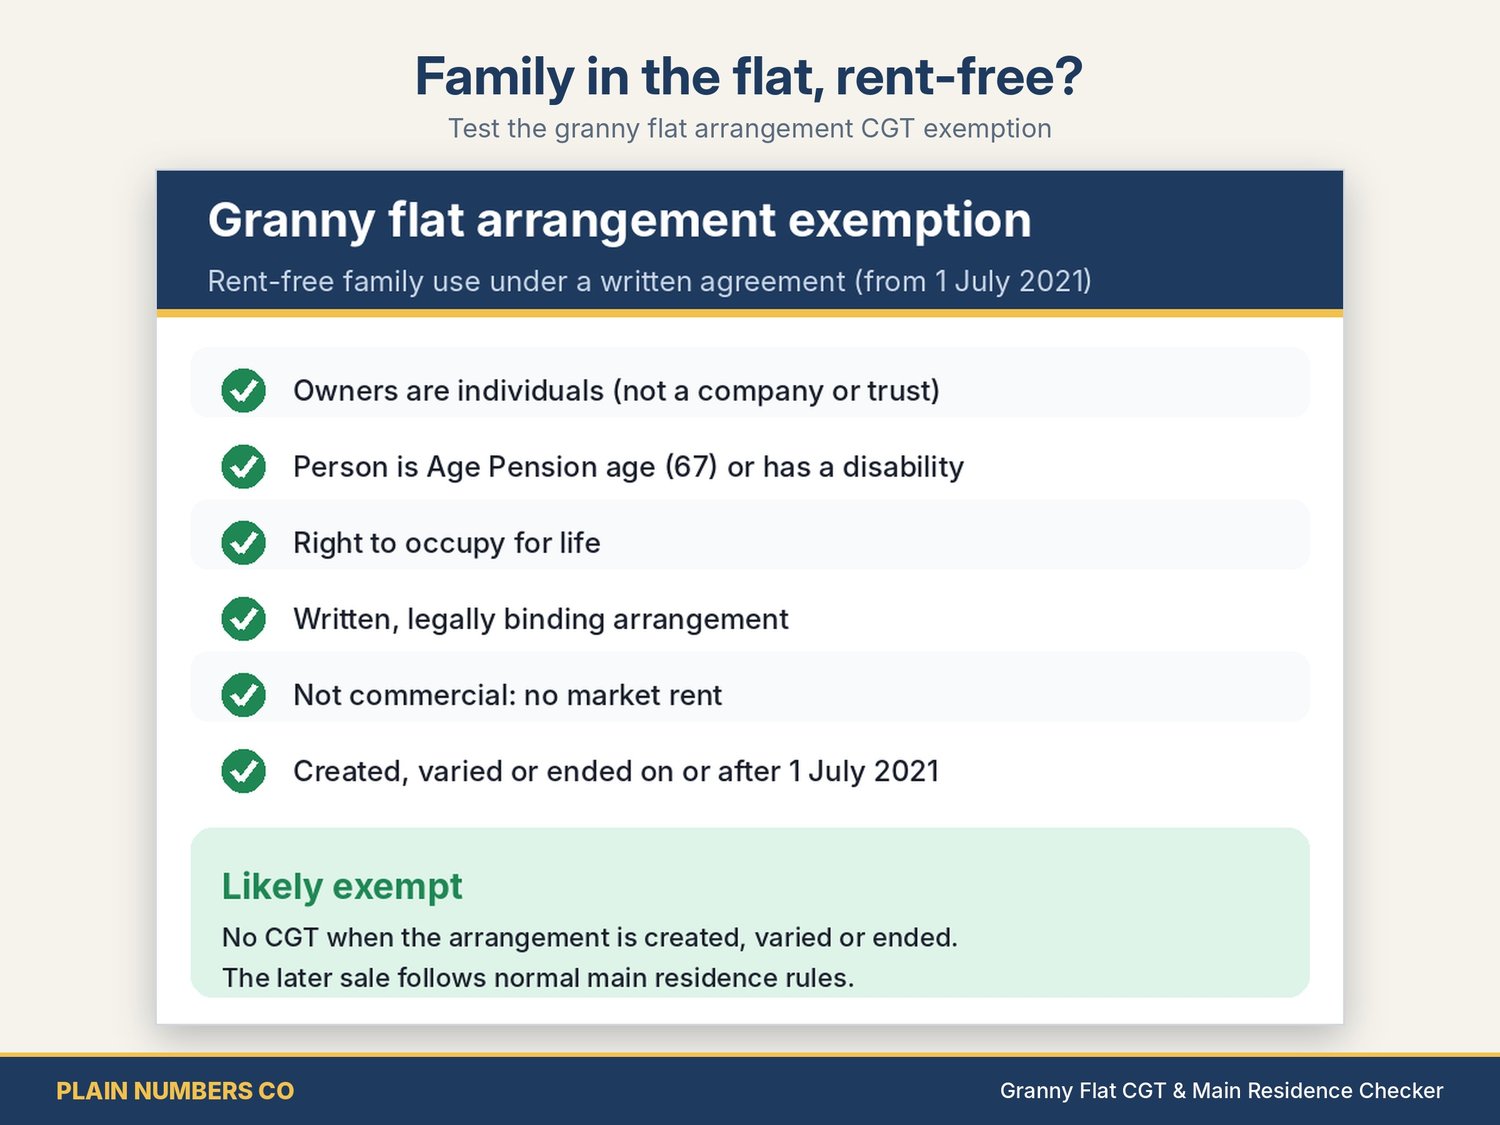
- A granny flat arrangement exemption test (from 1 July 2021) for a family member who lives in the flat rent-free under a written agreement. They must have reached Age Pension age or have a disability.
- A plain-English summary and 13 automatic checks.
Includes: Home, Dashboard, Your Details, Rules & Rates, Calculator, Granny Flat Arrangement, Summary, Checks and Notes & Sources. Notes & Sources lists every official link and the date it was checked. Example figures are filled in. Works in Excel and also opens in LibreOffice.
Built and checked by a CPA. Every formula tested against a separate calculation.
Designed by Plain Numbers Co with the help of AI tools. Listing images are designed previews of the actual file.
30-DAY MONEY-BACK GUARANTEE: if it doesn't work for your situation, message us within 30 days. We'll fix it, or refund you in full if you'd rather. This is in addition to your rights under the Australian Consumer Law, which are not excluded.
General information only, not tax or financial advice. This workbook does not consider your objectives, financial situation or needs. Consider speaking to a registered tax agent before you sign a contract or lodge a return.