
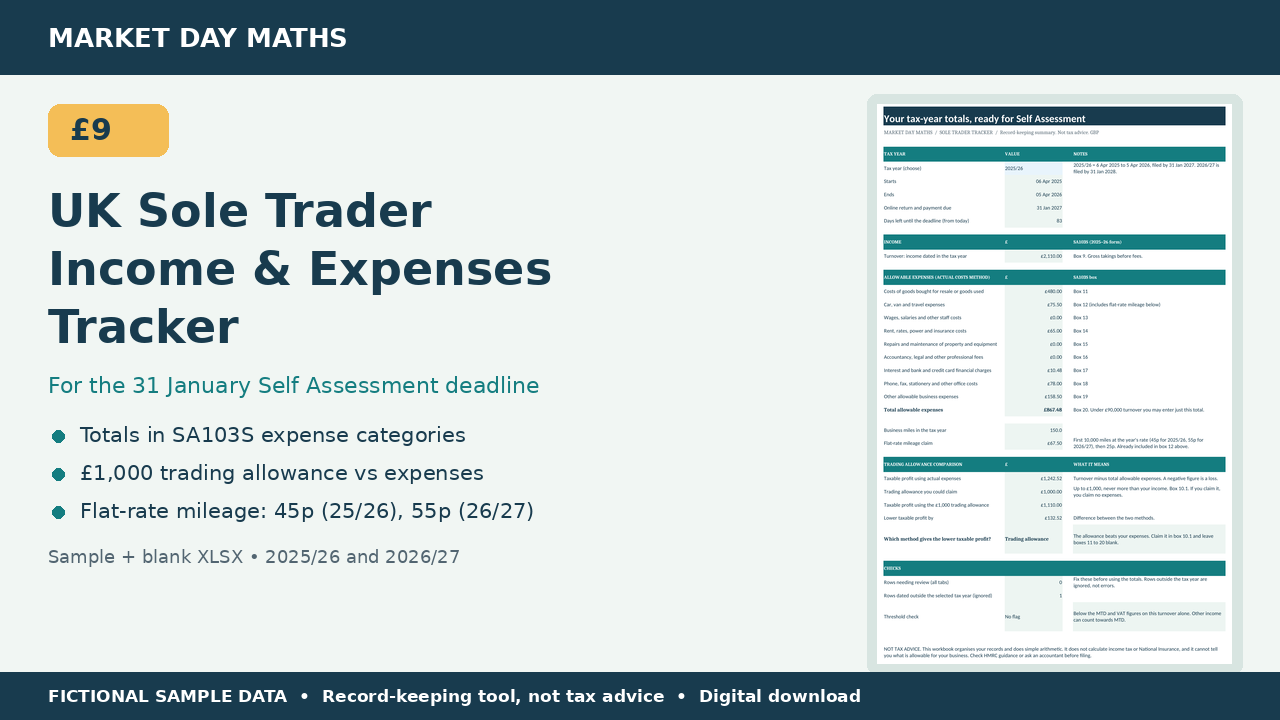
UK Sole Trader Income & Expenses Tracker | Self Assessment Spreadsheet for Makers
January doesn't have to mean a shoebox of receipts. This spreadsheet keeps your money in and money out in one place and gives you the totals your Self Assessment return asks for.
Log market takings, Etsy payouts, website orders and commissions on the Income tab. Add receipts on the Expenses tab, choosing from the nine categories used on HMRC's short self-employment page (SA103S), with a business-use percentage for mixed costs like your phone. Log business journeys and the tracker adds flat-rate mileage at the right rate for the year: 45p a mile for 2025/26, 55p for 2026/27, then 25p after 10,000 miles.
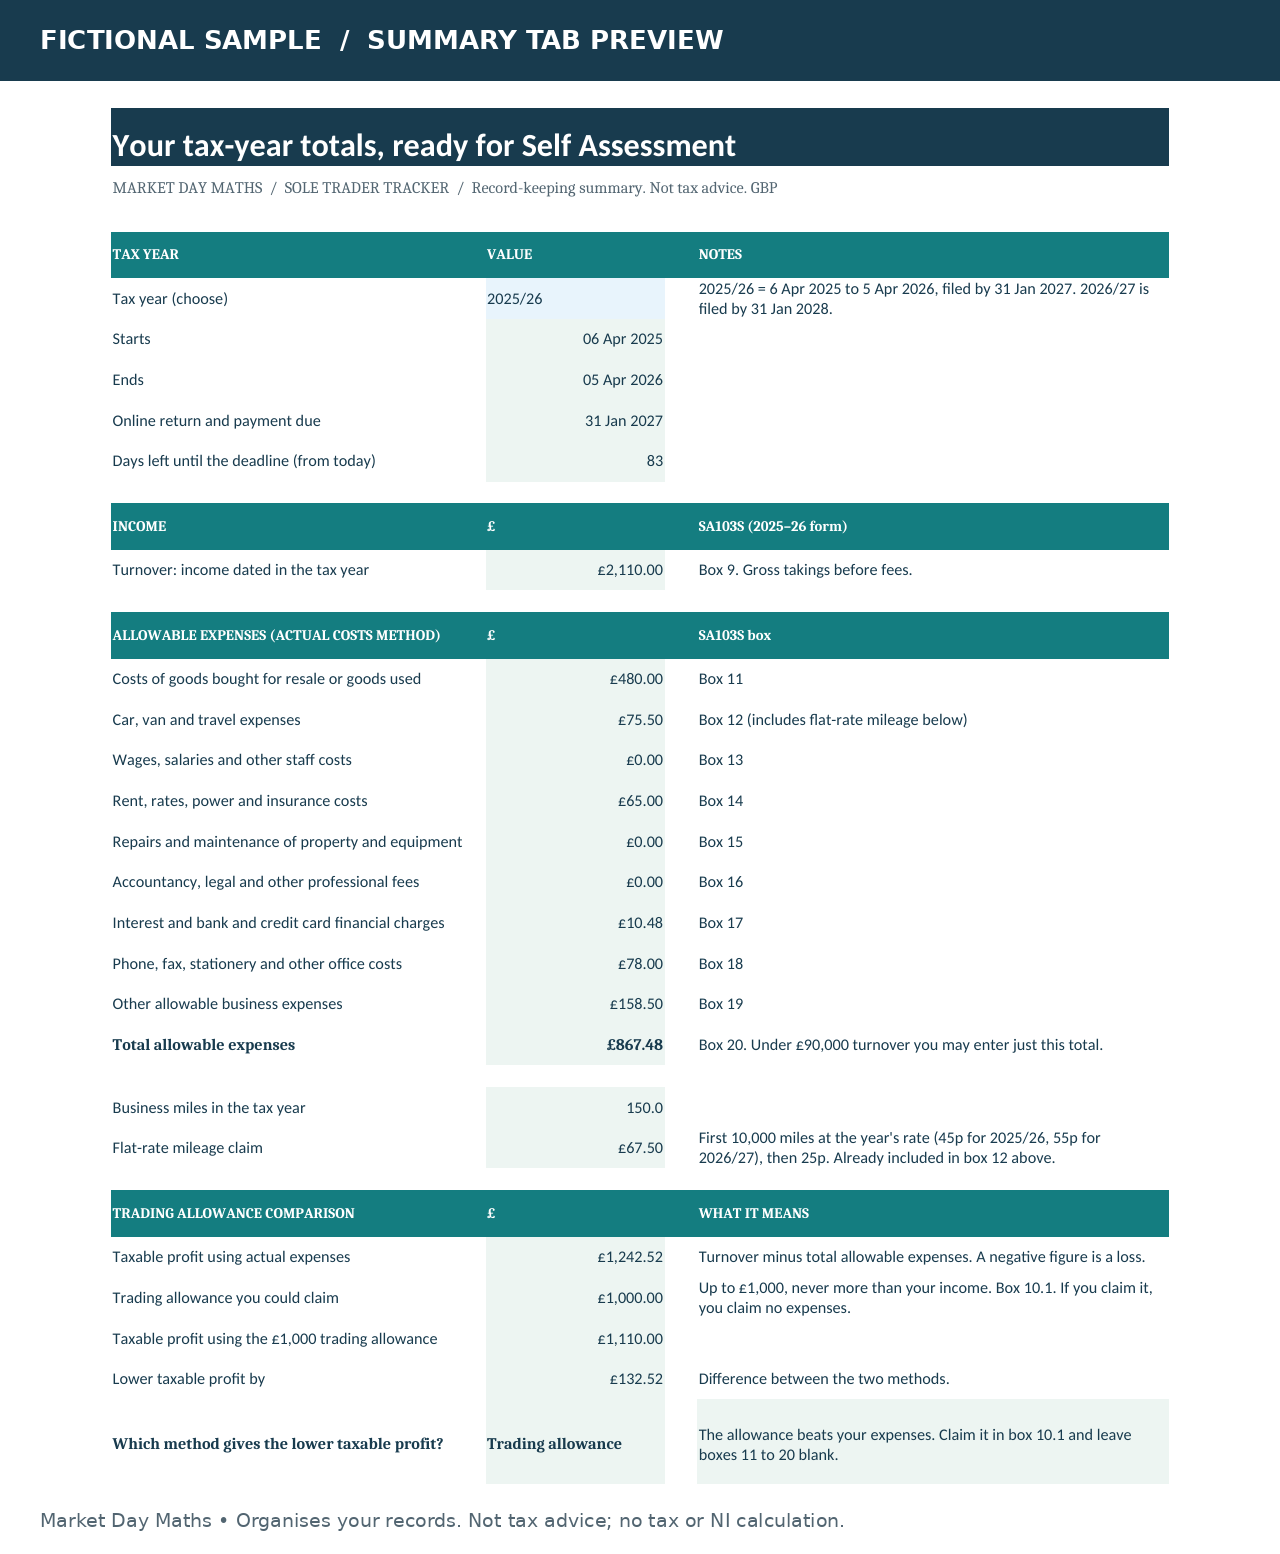
The Summary tab shows your turnover, expenses by box and total allowable expenses, then compares them with the £1,000 trading allowance so you can see which gives the lower taxable profit. Choose the 2025/26 tax year (return due 31 January 2027) or 2026/27. Rows dated outside the year are ignored and labelled, and incomplete rows are flagged.
Includes a fictional worked example (a candle maker) and a blank copy for your own records.
Not tax advice. This is a record-keeping tool. It does not calculate income tax or National Insurance, file anything with HMRC, or decide what is allowable for your business. It doesn't cover capital allowances, VAT or partnerships. If Making Tax Digital for Income Tax applies to you (from 6 April 2026 above £50,000 qualifying income, from 6 April 2027 above £30,000), you'll need HMRC-recognised software.
What's included: Two XLSX files (sample and blank): Summary, Income (500 lines), Expenses (500 lines), Mileage (300 journeys), How to use and Settings tabs. Rates checked on GOV.UK 9 Nov 2026 and editable.
Compatibility: Excel, LibreOffice Calc and Google Sheets XLSX import. No macros, add-ins or external data links. Tested in LibreOffice; not directly tested in Excel or Google Sheets. Import may change styling or protection.
Digital download / rights: Downloadable files only, no physical item. For use in your own business. Your statutory rights are unaffected.