

Debt Payoff Planner (Snowball and Avalanche)
Debt Payoff Planner Excel with both payoff methods side by side — snowball and avalanche — plus a full debt list, payment log, progress tracker, and dashboard. Know the date each debt dies, what the interest is really costing, and which method gets you out cheaper.
Built for anyone carrying several balances at once — cards, loans, medical bills, buy-now-pay-later plans — who wants one honest plan instead of ten statements. If a minimum payment barely covers the interest, this workbook shows it in the first minute.
WHAT'S INCLUDED (6 sheets):
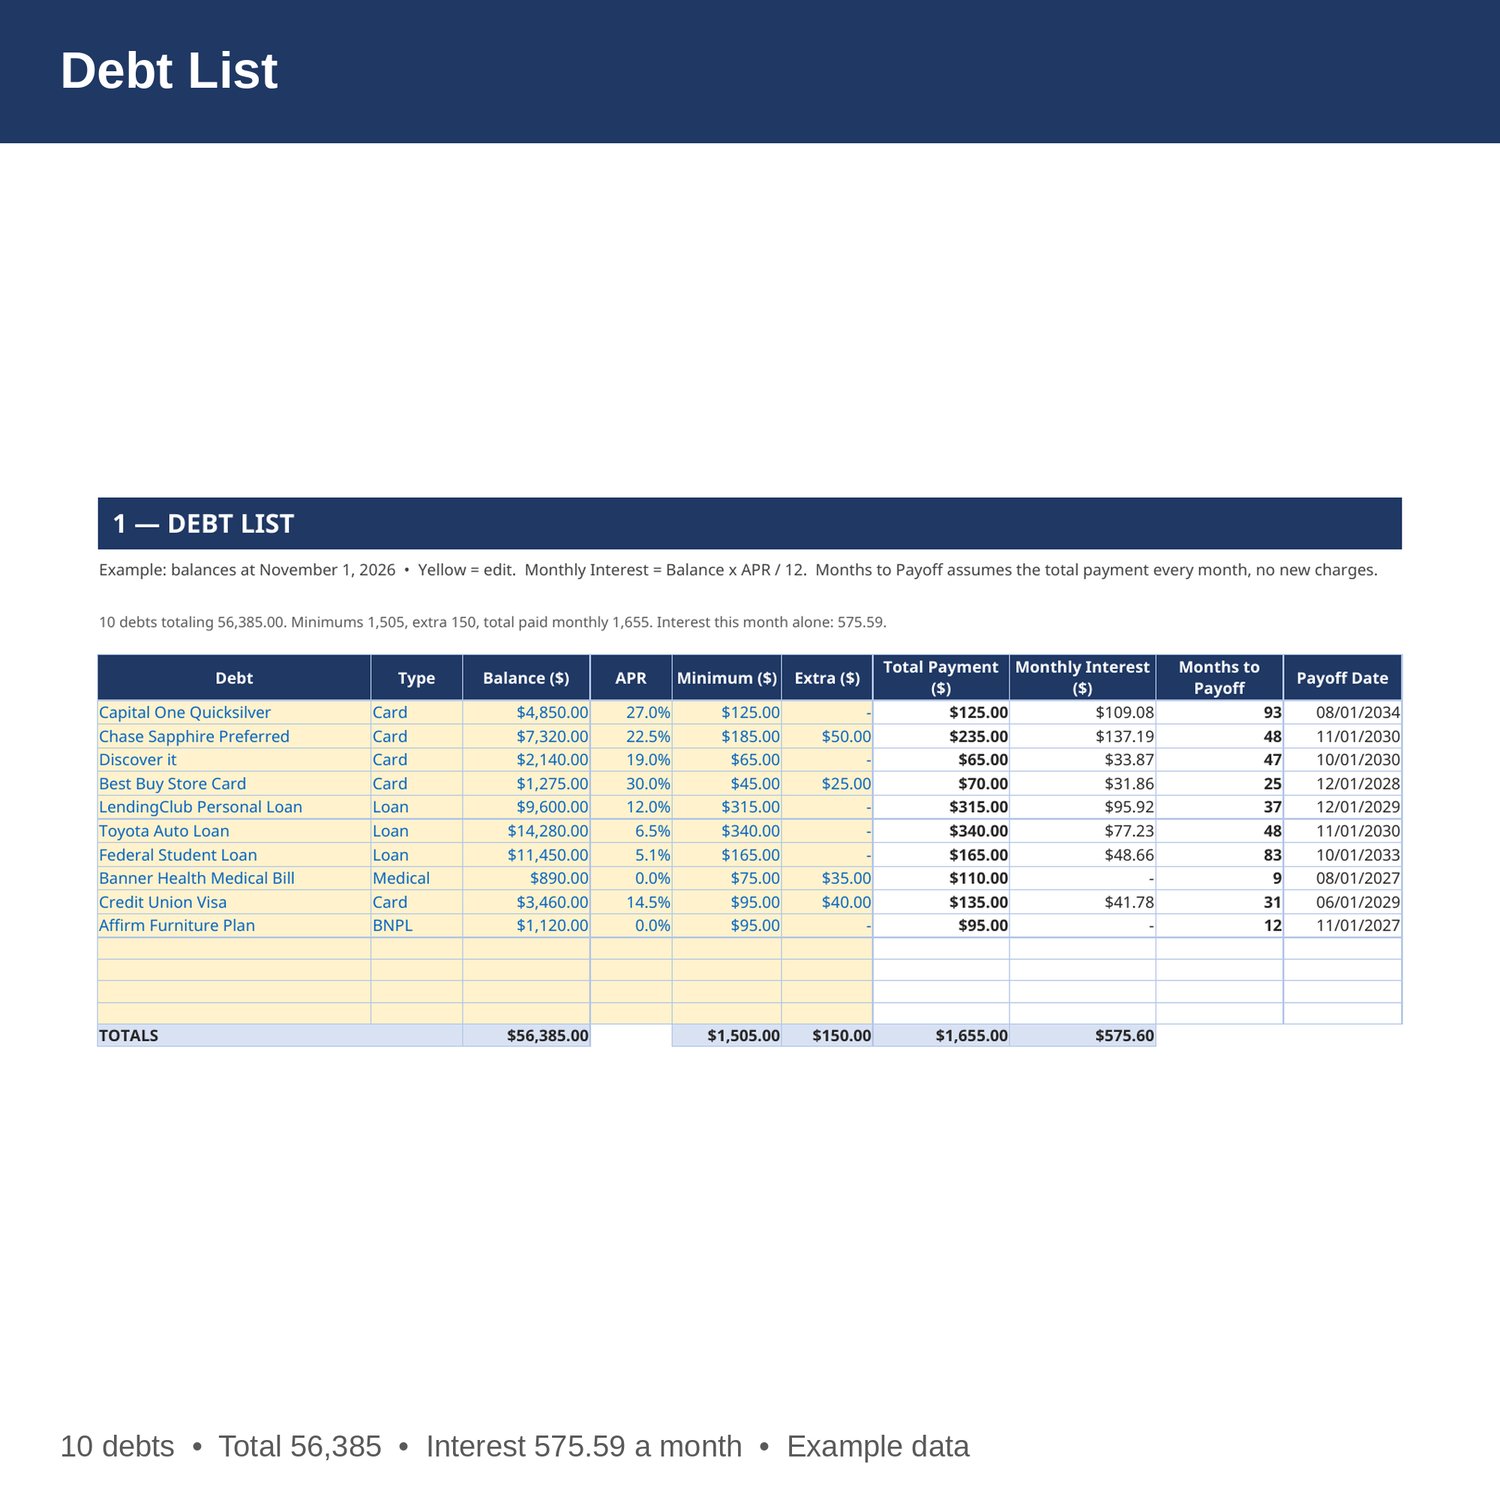
- Debt List — every debt with its balance, APR, minimum payment, and any extra you pay. Total payment, monthly interest, months to payoff, and the payoff date fill in by formula.
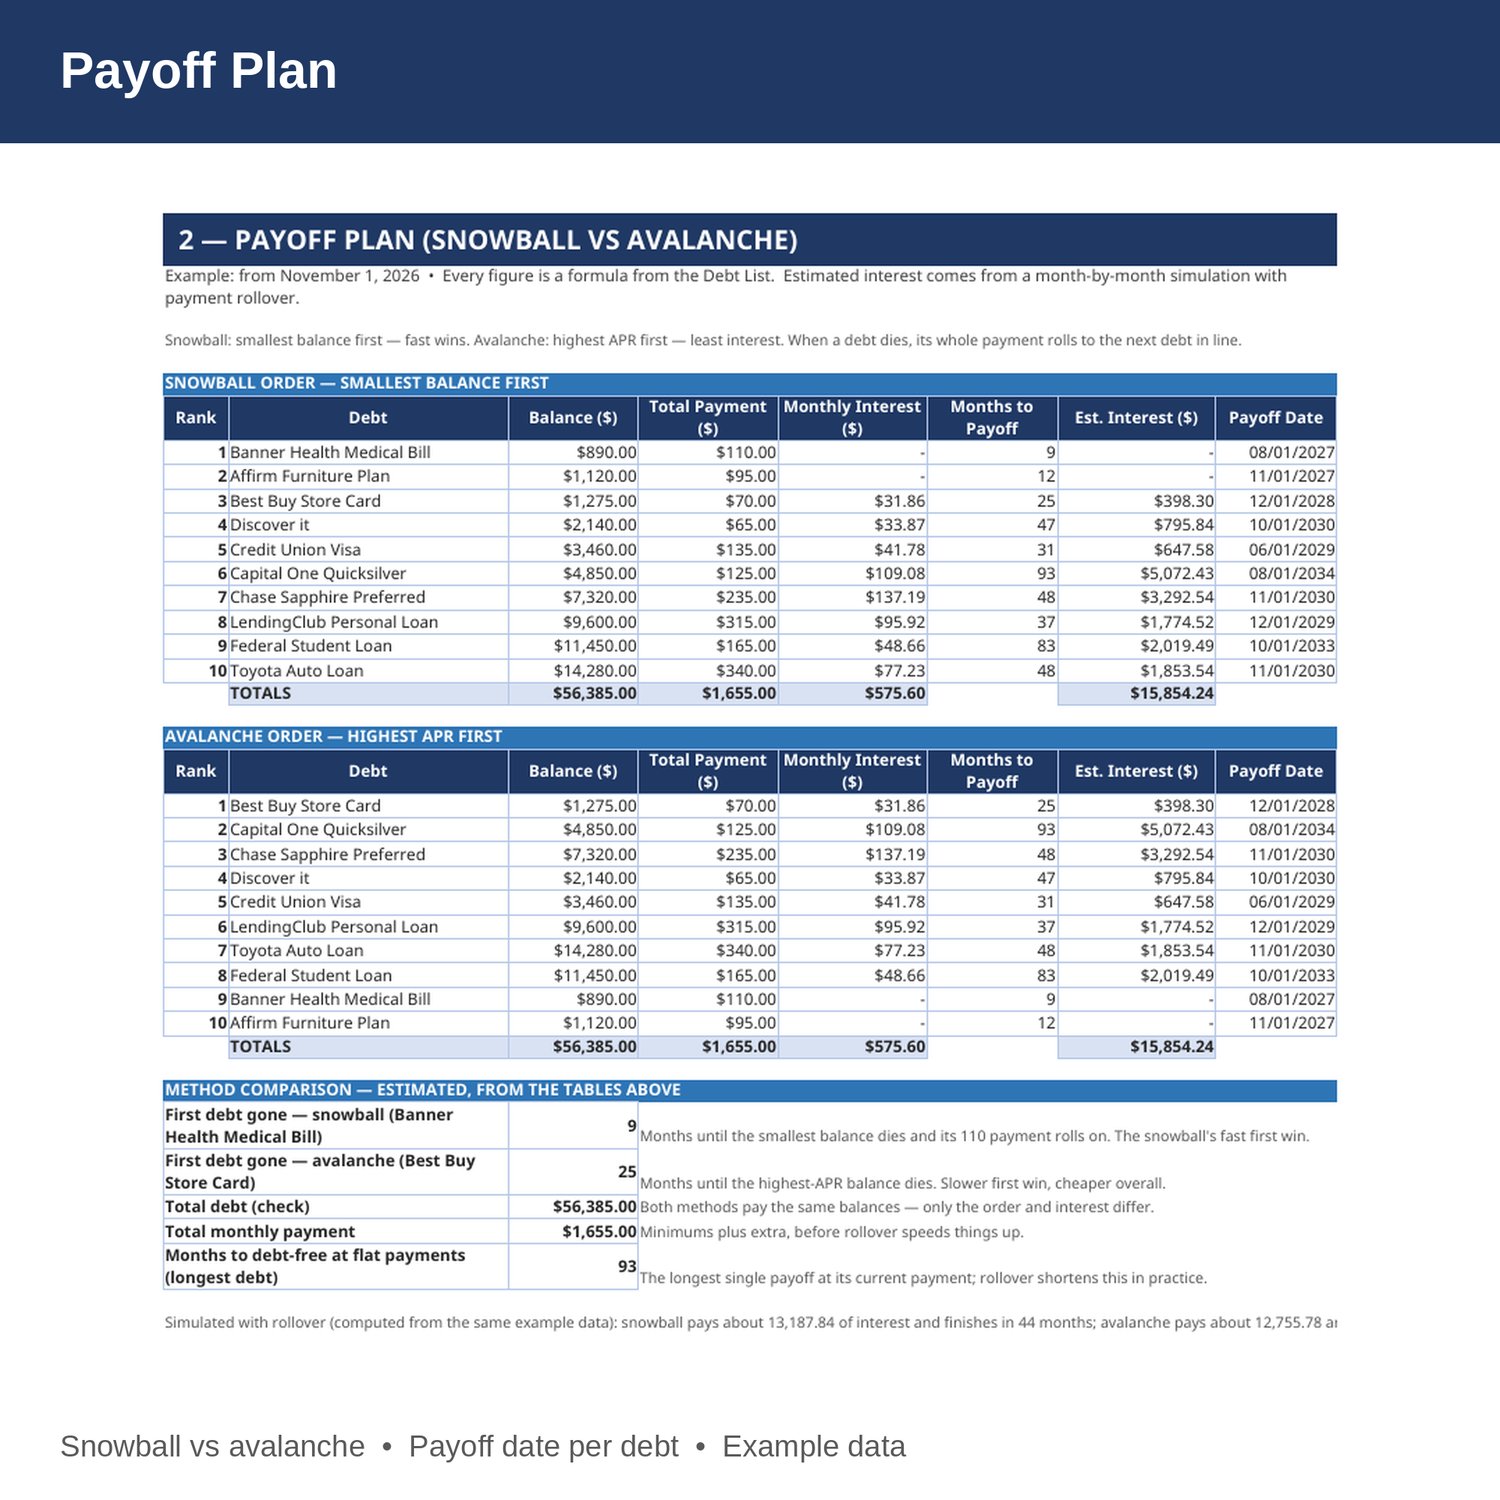
- Payoff Plan — the same debts in snowball order (smallest balance first) and avalanche order (highest APR first), each row pulled from the Debt List by formula, with first-win timing for each method and a simulated rollover comparison computed from the same example data.
- Payment Log — every payment: date, debt, amount paid, interest portion from your statement, principal by formula, and the statement balance after the payment.
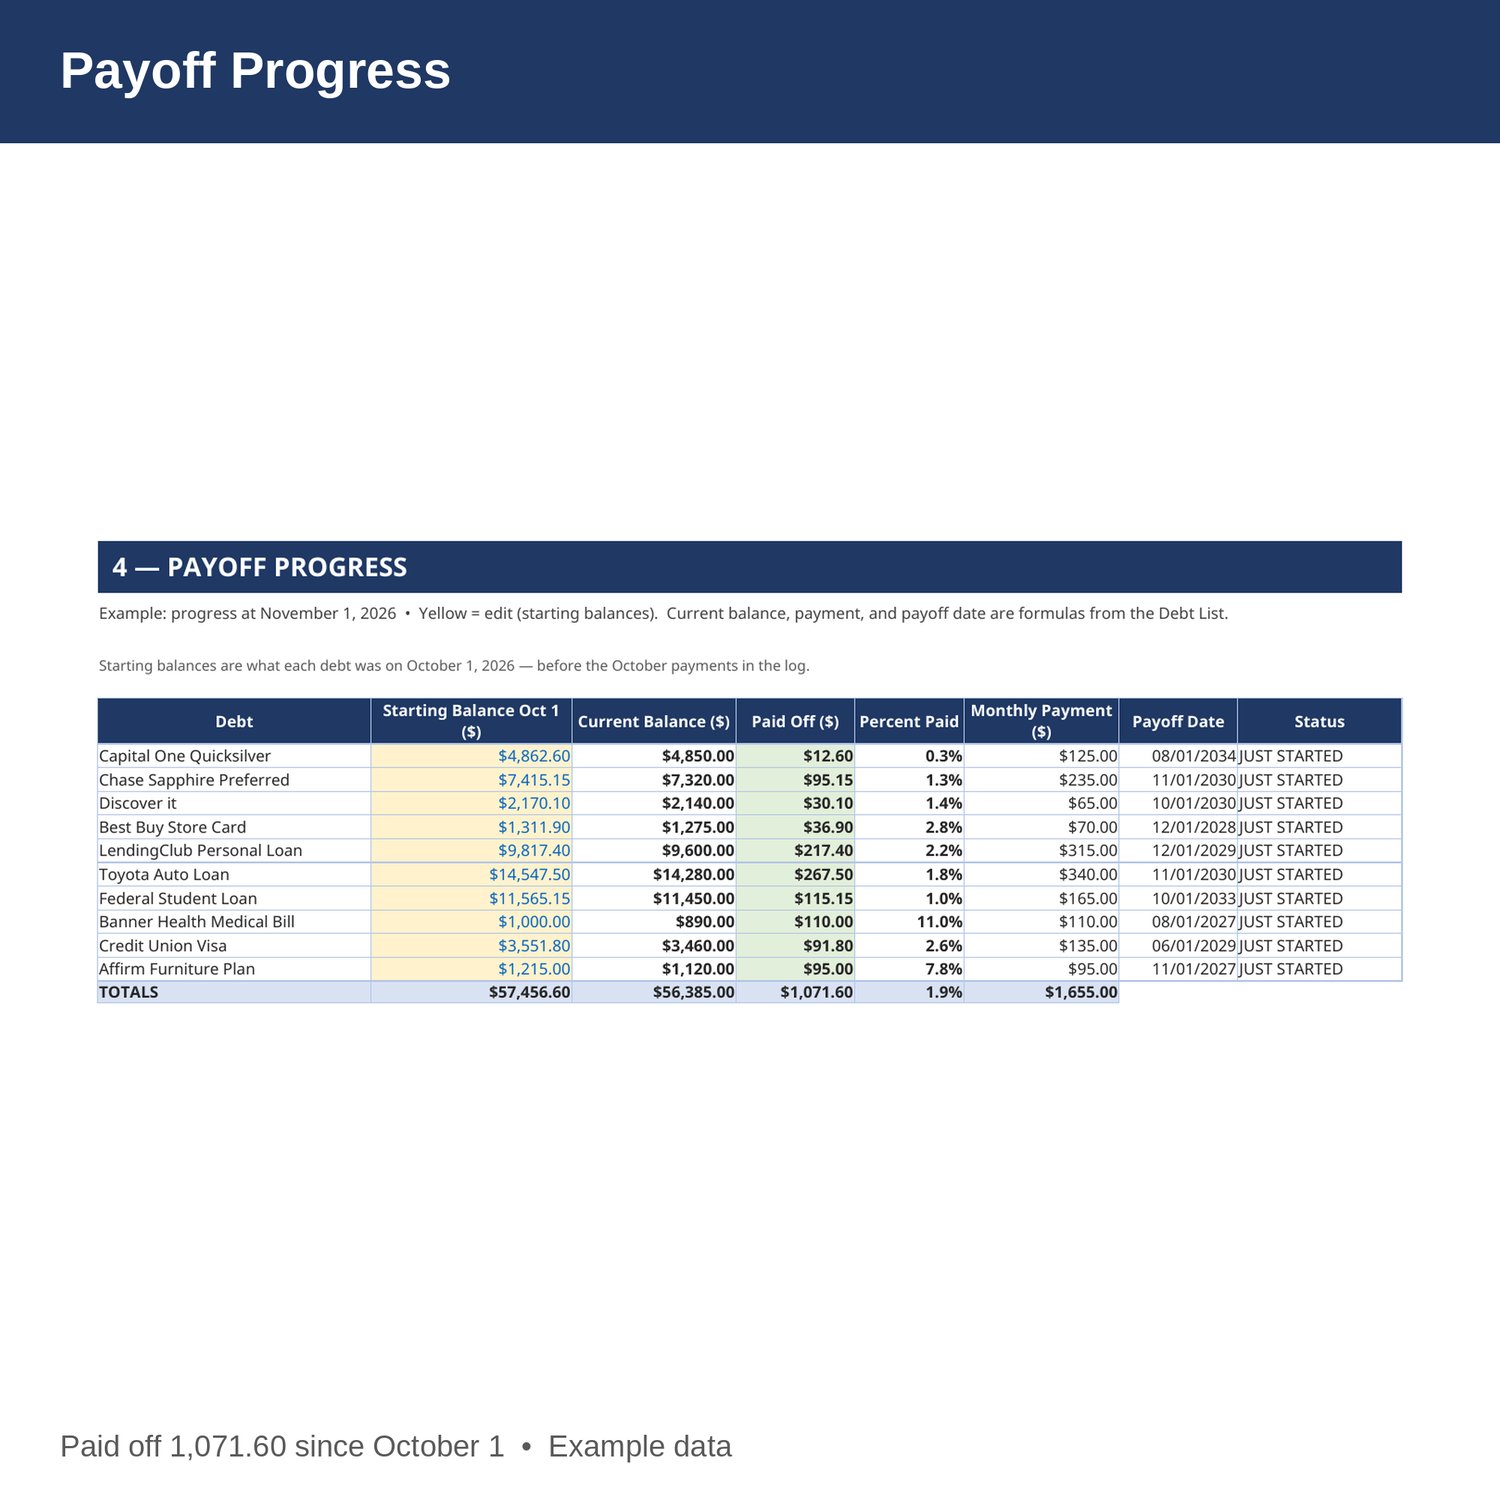
- Payoff Progress — starting balance on October 1 vs current balance per debt, amount paid off, percent paid, monthly payment, payoff date, and status.
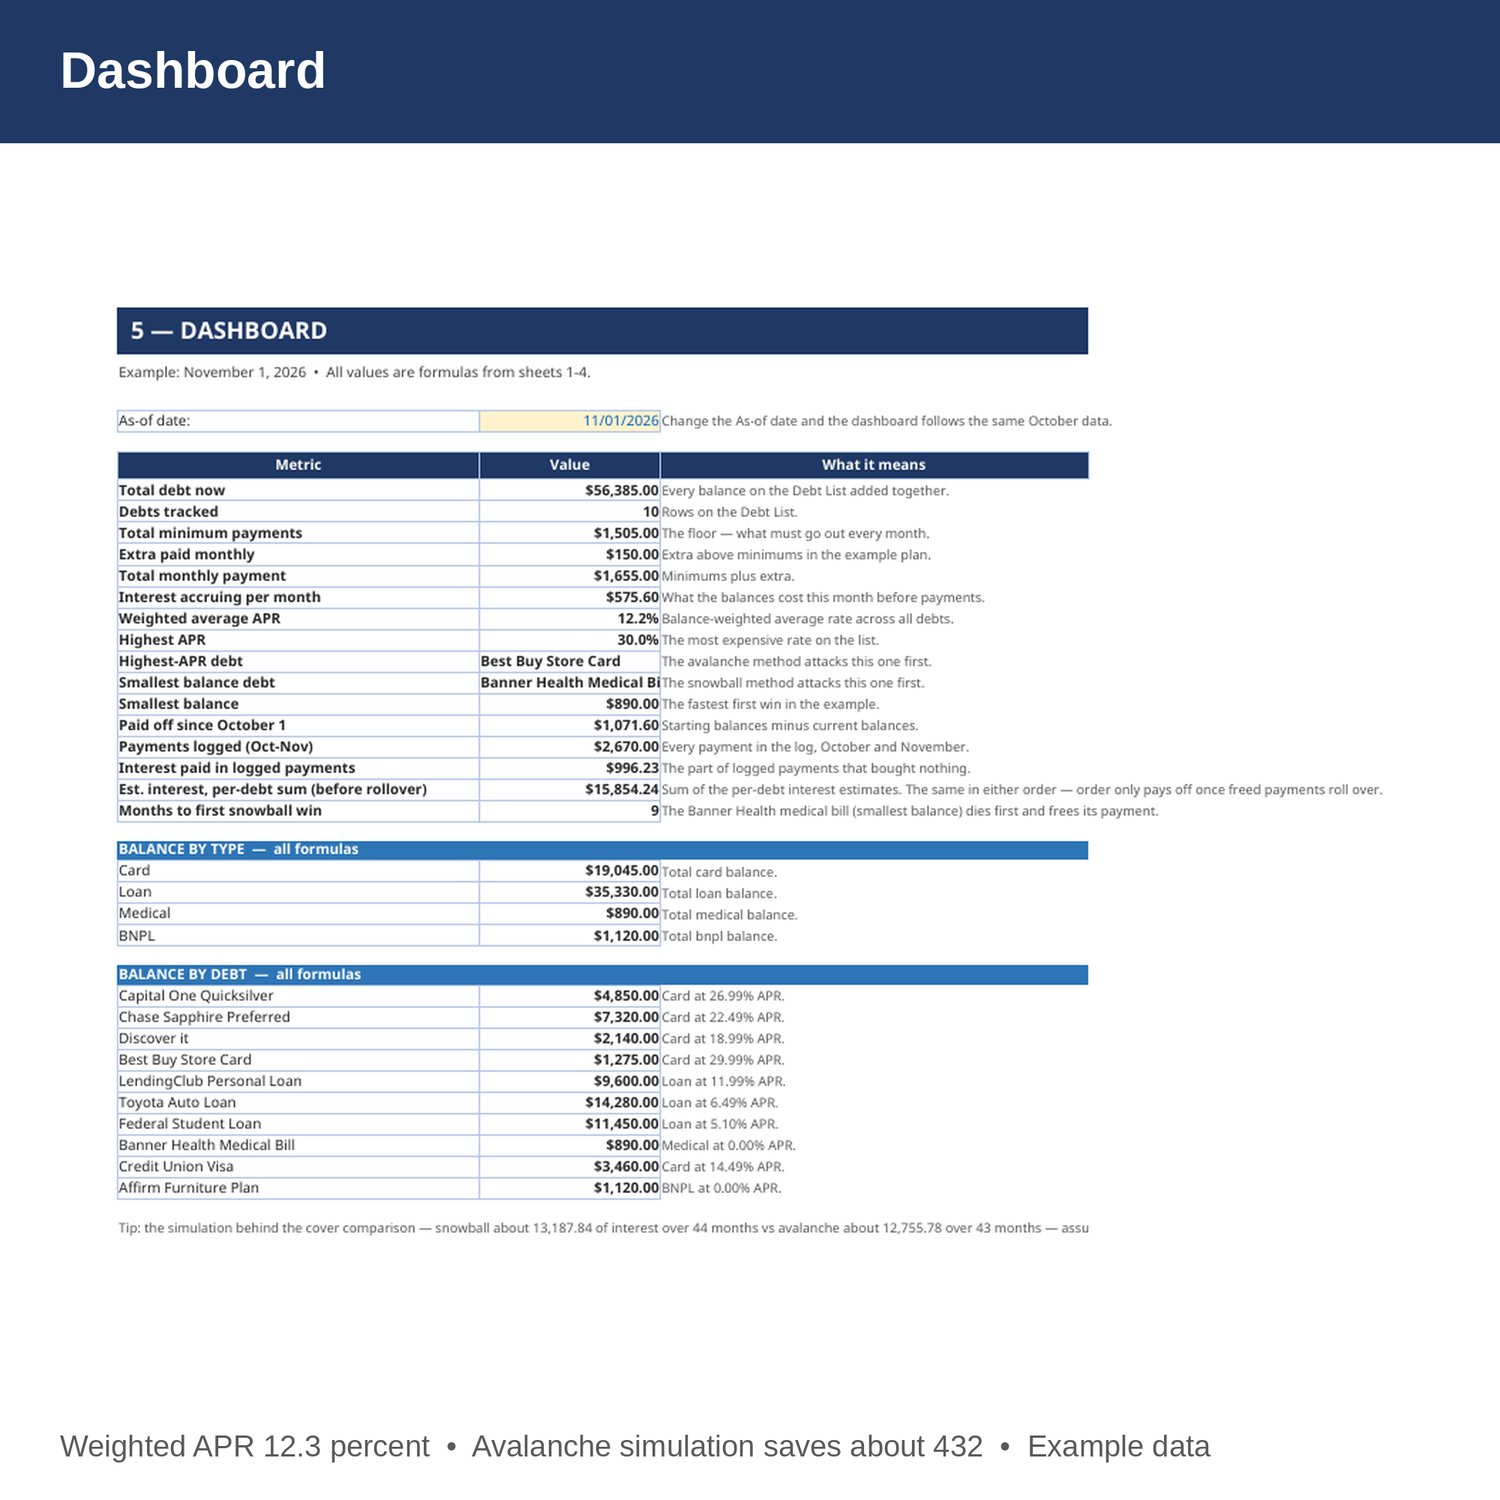
- Dashboard — total debt, number of debts, total minimums, extra paid monthly, total monthly payment, interest accruing per month, weighted average APR, highest-APR debt, smallest-balance debt, paid-off progress, logged payments, balance by type, and balance by debt.
- Cover and How to Use — start here. Yellow cells are the only ones you edit.
EXAMPLE DATA (balances at November 1, 2026 — replace with your own numbers):
- 10 debts totaling 56,385: cards, a personal loan, an auto loan, a student loan, a medical bill, and a buy-now-pay-later plan.
- Minimums 1,505 a month, extra payments 150, total monthly payment 1,655. Interest accruing this month: 575.59. Weighted average APR 12.3 percent.
- Simulated with payment rollover: snowball pays about 13,187.84 of interest over 44 months; avalanche pays about 12,755.78 over 43 months — a saving of about 432.06. The snowball's win is the fast first payoff, not the math, and the workbook says so.
- 14 payments logged for October and November 2026 totaling 2,670, of which 996.23 was interest.
- Paid off since October 1: 1,071.60.
HOW IT WORKS:
1. Download the Excel file instantly after purchase.
2. On sheet 1, list every debt: balance, APR, minimum, and any extra you pay. Interest, months to payoff, and payoff date fill in by formula.
3. On sheet 2, compare the two orders. When a debt dies, roll its whole payment to the next debt in line.
4. On sheet 3, log each payment with the interest portion from your statement. Principal fills in by formula.
5. Sheets 4 and 5 update by formula as your balances change.
HOW THE NUMBERS WORK:
Monthly interest is balance times APR divided by 12. Months to payoff assumes the same total payment every month and no new charges, using the standard loan payoff calculation. Estimated interest per debt in the plan tables is the monthly interest times months to payoff divided by 2, a declining-balance approximation before rollover. The rollover comparison is a month-by-month simulation run on the same example data: each month interest accrues, payments land, and a paid-off debt's payment rolls to the next debt in line. Your actual interest depends on statement timing, rate changes, and new charges.
WHO IT'S FOR:
Anyone with two or more debts who wants a real payoff date, an honest interest number, and a plan they can watch shrink — without accounting software.
PLEASE NOTE:
- This is a digital download. No physical item will be shipped.
- Works in Microsoft Excel and Google Sheets (upload to Google Drive to open in Sheets).
- Example data is included (10 debts, payments logged October-November 2026). Replace it with your own numbers.
- The honest weak spot in the example: the Capital One card at 26.99 percent APR accrues about 109.08 of interest a month against a 125 minimum, so the minimum alone moves that balance by about 16 a month for years. The plan only works if new charges stop.
- This is a planning tool only, not tax, legal, or financial advice. Confirm payoff decisions with your own accountant or financial advisor.
- Due to the nature of digital downloads, refunds are not available. Message me before buying if you have a question.
Built by an accountant: B.S. Accountancy, ASU W. P. Carey, with revenue-reconciliation experience at Marriott and audit work at PwC.