
Snowball Avalanche And What The Ordering Really Costs
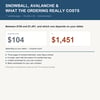
Snowball against avalanche is an argument. The gap between them is a number. Avalanche -- highest interest rate first -- is mathematically optimal, and that is true and useless without a number attached. The number turns out to depend on something neither camp mentions: whether your smallest balance happens also to be your most expensive one. On a mixed set where it is, both strategies attack the same debt first and choosing snowball costs $104 over four years. On a set where the small debt is cheap and the big one dear, snowball costs $1,451 and finishes two months later.
Snowball costs $104 on one set of debts and $1,451 on another
Snowball against avalanche is an argument. The gap between them is a number. Avalanche — highest rate first — is mathematically optimal, which is true and useless without a number attached.
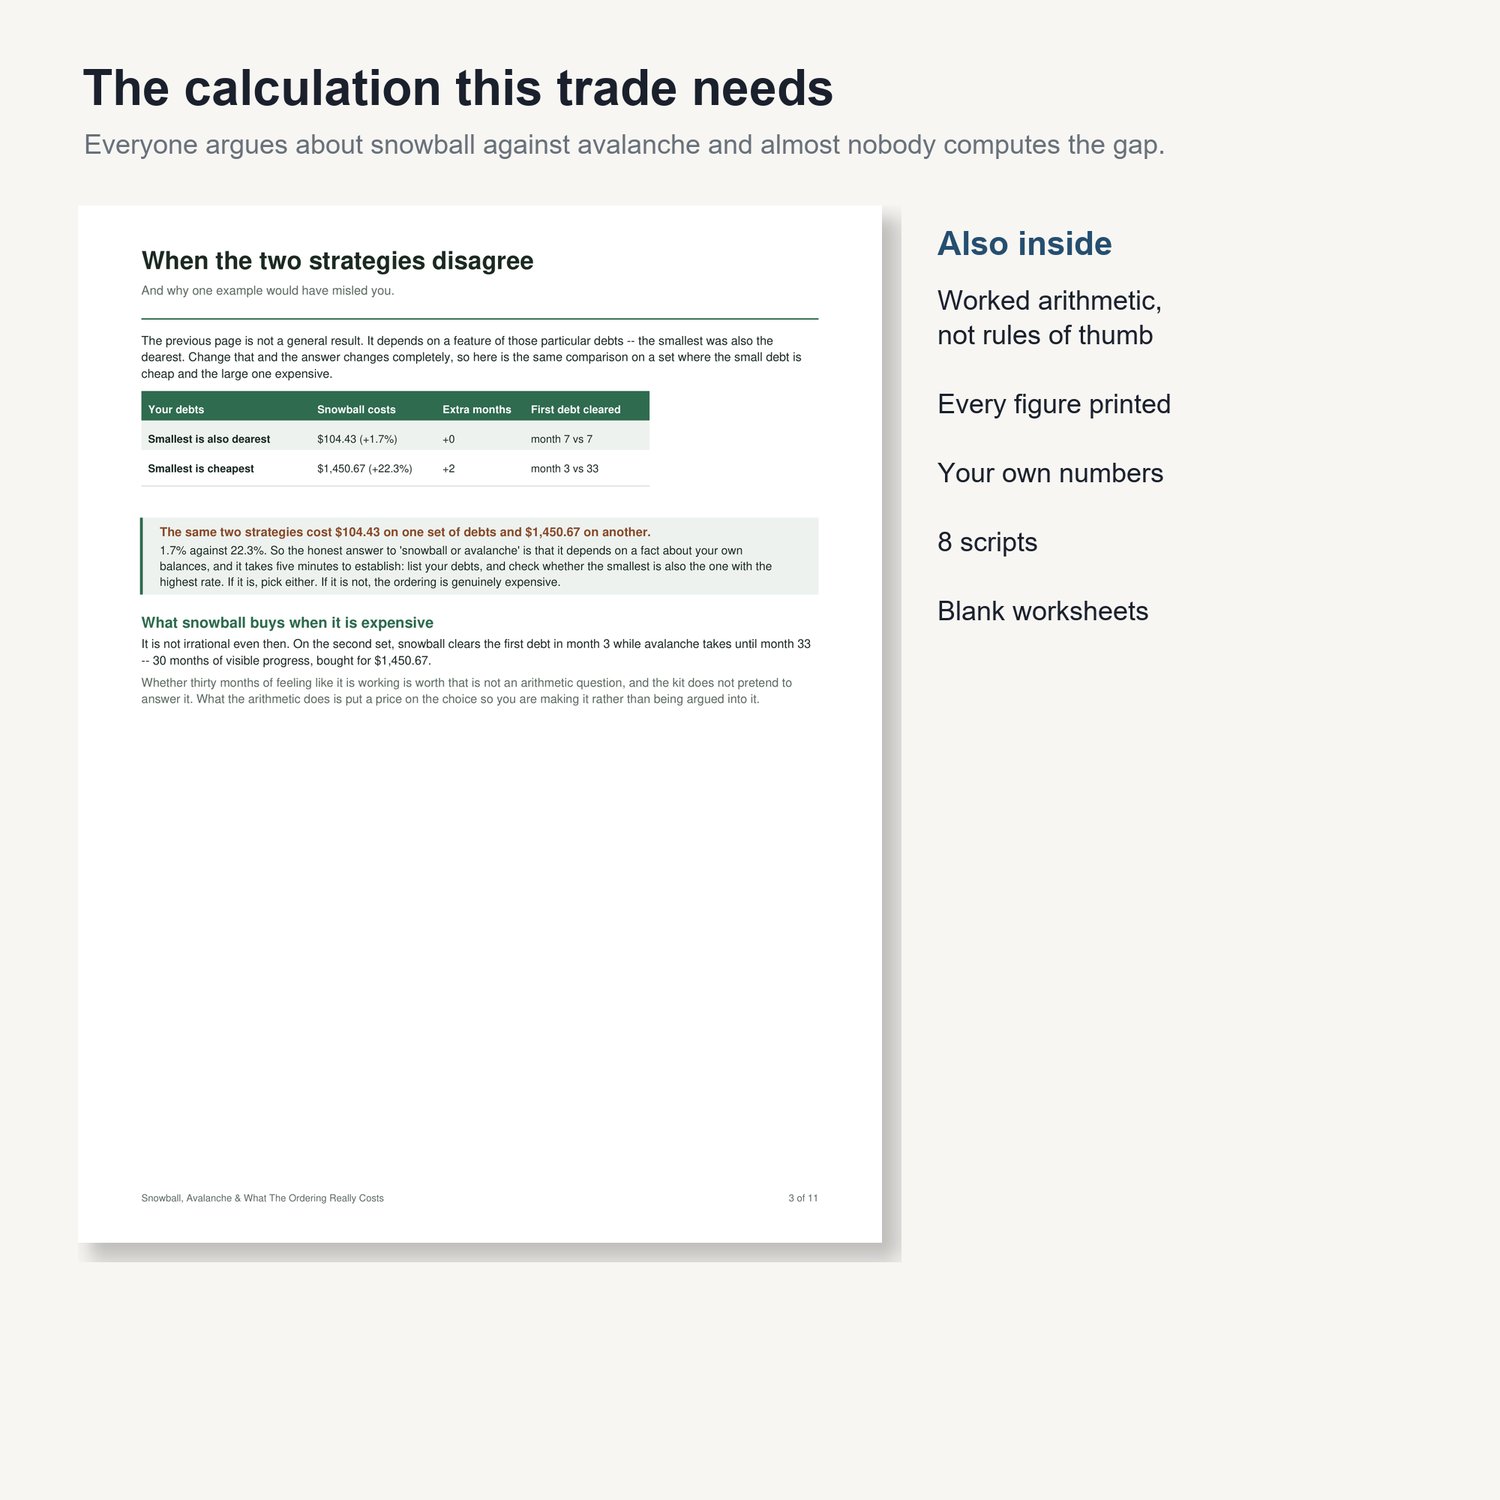
The number depends on something neither camp mentions: whether your smallest balance happens also to be your most expensive one. On a realistic five-debt set where it is — a small store card at 26.99% — both strategies attack the same debt first, both finish in 46 months, and choosing snowball costs $104.43, or 1.7%. The entire argument is worth about a hundred dollars.
Change that one feature and it inverts. Where the small debt is cheap and the large one dear, snowball costs $1,450.67 (22.3%) and finishes 2 months later. But it clears your first debt in month 3 instead of month 33 — so you are buying 30 months of visible progress, which is a real trade rather than a mistake. The kit prices it and lets you decide.
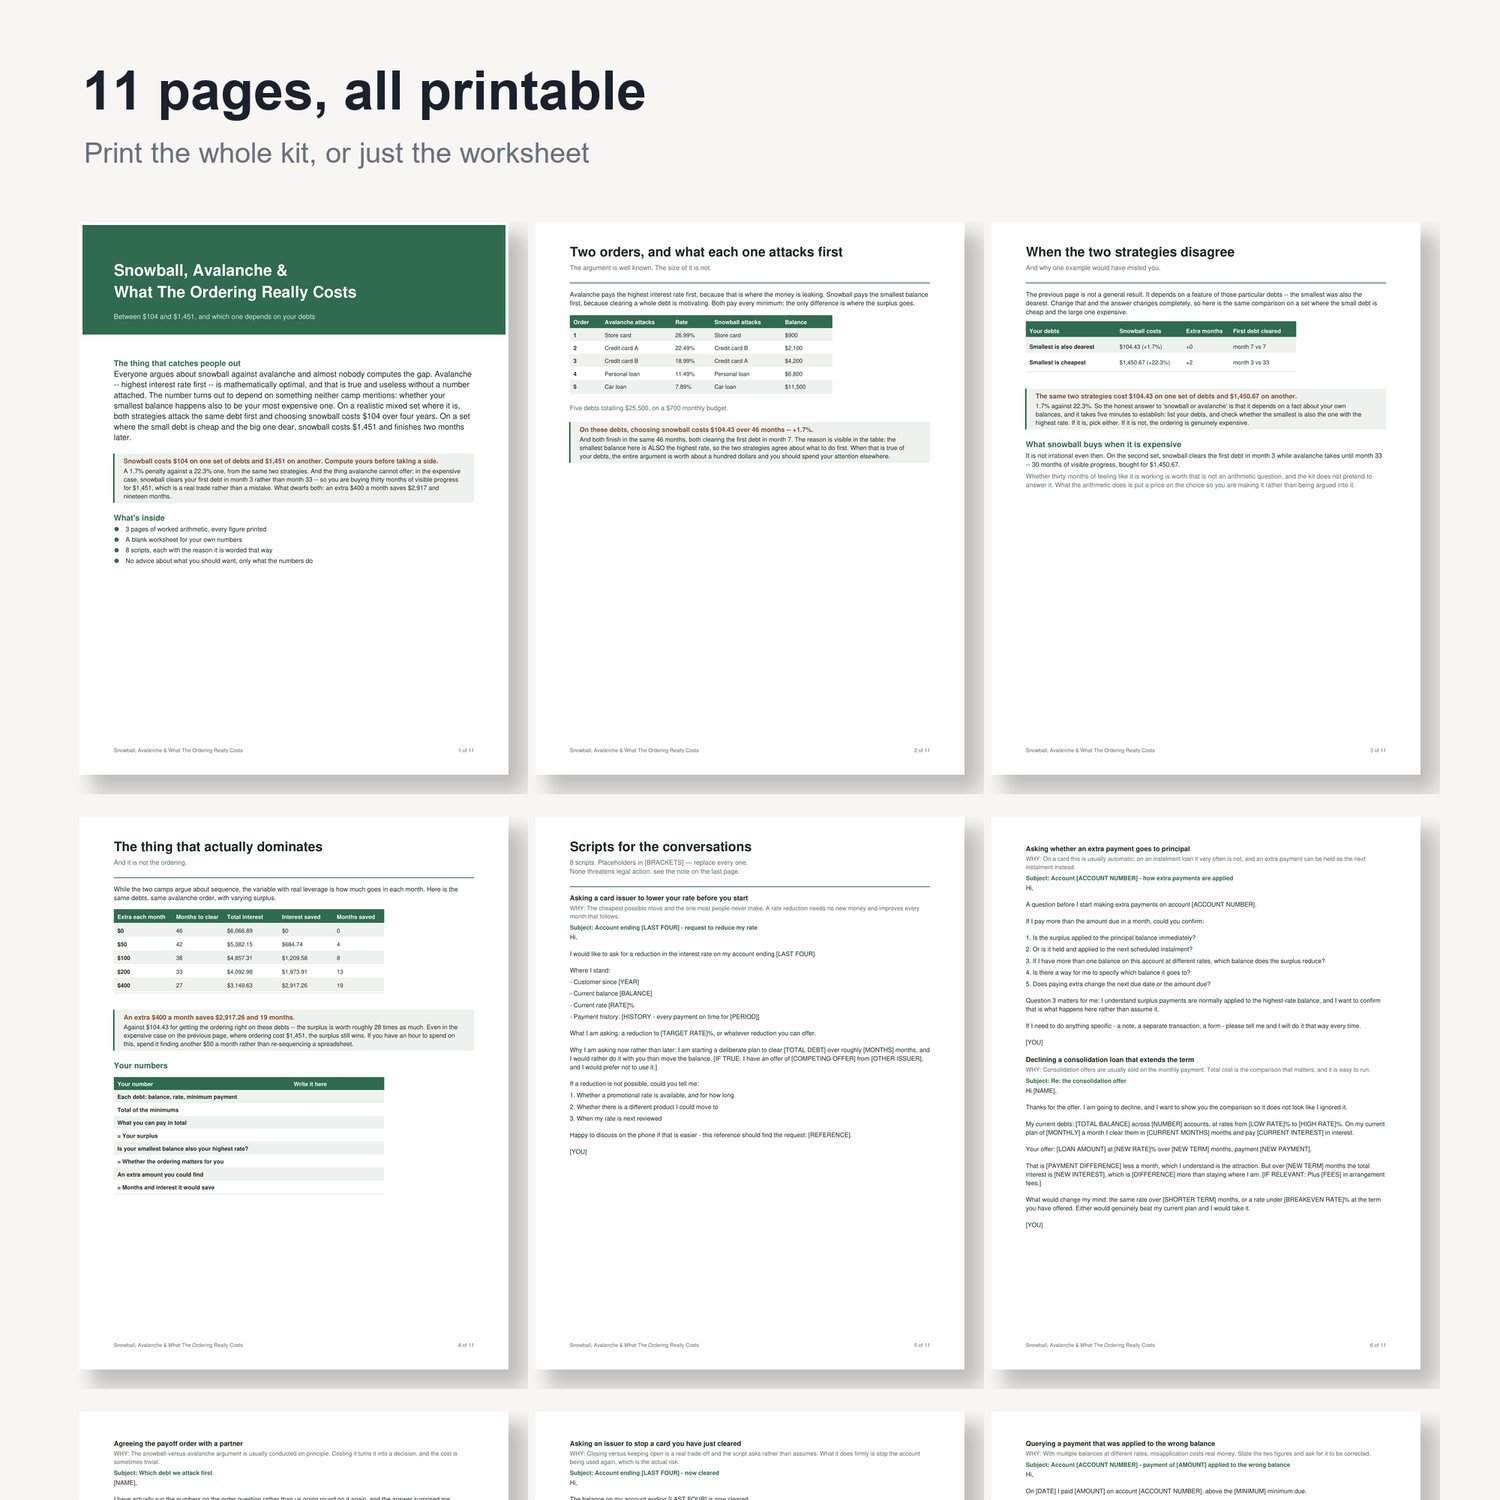
And the thing that dwarfs both: an extra $400 a month saves $2,917.26 and 19 months — worth roughly 28 times the ordering decision. If you have an hour, spend it finding another $50 a month rather than re-sequencing a spreadsheet.
Includes a live Excel workbook that takes your debts and answers the one question that settles it — is your smallest balance also your highest rate — plus eight scripts: asking an issuer to lower your rate before you start, whether an extra payment reaches principal, declining a consolidation loan that extends the term, and asking for a hardship rate before you miss a payment rather than after.
8 scripts for the conversations this involves
Each one carries a line explaining why it is worded that way, because a script you do not understand is one you will not send. Placeholders are in [BRACKETS] so nothing goes out in someone else's words.
- Asking a card issuer to lower your rate before you start
- Asking whether an extra payment goes to principal
- Declining a consolidation loan that extends the term
- Agreeing the payoff order with a partner
- Telling family you are pausing a shared expense to clear debt
- Asking an issuer to stop a card you have just cleared
- Querying a payment that was applied to the wrong balance
- Asking for a hardship rate before you miss a payment
What this is not
This is arithmetic, not advice. Every figure is computed from the inputs stated on the page, and the working is printed so you can substitute your own. What it cannot tell you is what you should want — it shows what a choice costs, not which choice is right for your household.
Nothing here is financial, tax or legal advice, and it is not a recommendation to buy, sell, borrow or sign anything. The scripts are wording for a conversation, not legal instruments, and none of them threatens anything.
Where the kit uses a published rate or threshold, it is the one current when the kit was built. Those change; the arithmetic does not.
Honest about the format
Printable PDFs plus an editable Excel workbook, not a physical product. One US Letter PDF (11 pages) and one A4 PDF (11 pages), and one .xlsx that opens in Excel, Numbers, LibreOffice and Google Sheets. Files are available immediately after purchase; nothing ships.
Refunds
If this isn't what you expected, email me within 30 days and I'll refund you in full — no need to explain. Because it's an instant download I can't take the files back, so I'd rather you just had your money back.