
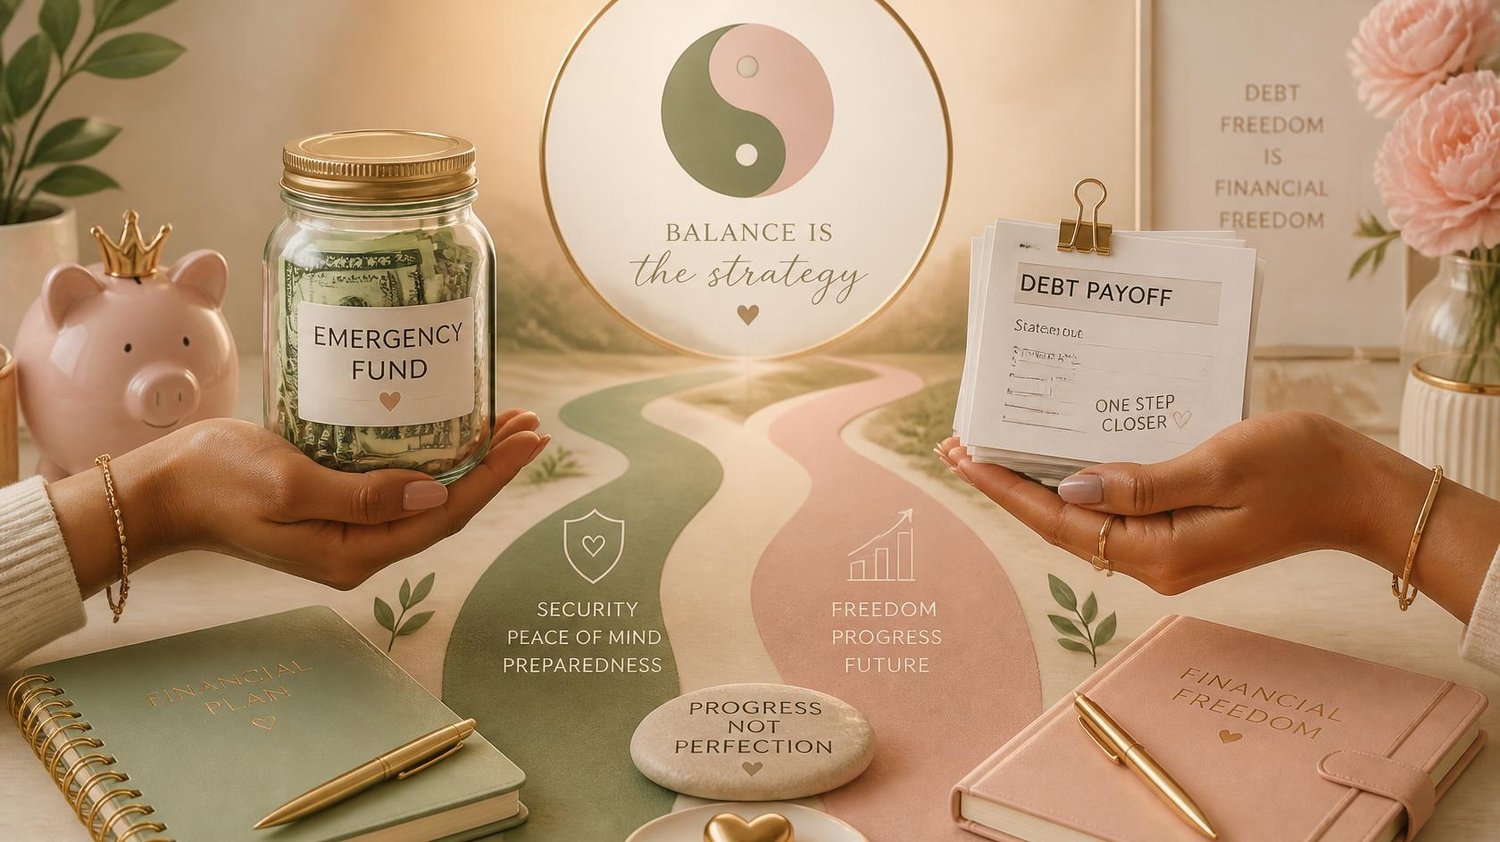
You finally have a little extra breathing room in your budget — maybe $200, maybe $500 — and now you're staring at two very reasonable, very different options.
Build the emergency fund you've never quite had. Or throw everything at the debt that's been sitting there, quietly charging you interest every month.
Every finance account online seems to have a strong opinion about which one comes first. Here's the truth: the "right" answer depends on your situation, not a universal rule — and once you see the framework, you'll know exactly which one is right for you.
Why This Question Feels So Hard
It's not really about math. It's about safety.
Debt feels urgent because it's loud — a statement in your inbox, a due date, interest accruing while you sleep. An emergency fund feels quiet by comparison — nothing bad is happening yet, so it's easy to deprioritize.
But that quiet is exactly the problem. Without a cushion, the next unexpected expense — a car repair, a medical bill, a slow month at work — doesn't just interrupt your life. It goes straight back onto a credit card, and the debt you were trying so hard to pay off grows right back.
The Framework: A Starter Fund First, Always
Before anything else — before extra debt payments, before investing, before anything — most financial educators agree on this: build a small starter emergency fund first. Not a fully-loaded six-month fund. Just enough to catch you.
A common starting target is $1,000, or one month of essential expenses, whichever feels right for your life. This isn't your final safety net — it's a shock absorber, just big enough that a flat tire or a broken phone doesn't become new debt.
Once that starter fund exists, then the real decision begins.
After Your Starter Fund: How to Decide
Lean toward debt payoff first if:
- Your debt carries high interest (think credit cards in the 20%+ range)
- Your income and job feel relatively stable right now
- The weight of that debt is affecting your peace more than the fear of not having savings
Lean toward building your full emergency fund first if:
- Your income is unpredictable, seasonal, or commission-based
- You don't have reliable support if something went wrong tomorrow
- Your existing debt carries low interest (think a car loan under 7%)
Or — do both, just not equally. A popular middle path: split your extra money, sending the majority toward your highest-interest debt while still adding a smaller, steady amount to savings each month. Progress on both fronts, even if one moves faster than the other.
There's no wrong answer here as long as you're choosing on purpose, instead of freezing because you can't find the "perfect" one.
A Simple Way to Decide This Week
Ask yourself one question: if my car broke down tomorrow, what would I do?
If the honest answer is "put it on a credit card," your starter emergency fund isn't optional — it's next. If the honest answer is "I'd be annoyed, but I'd be fine," you likely have enough of a cushion to send extra money toward debt with confidence.
That one gut-check usually tells you more than any calculator.
Give This Decision a Home in Your Budget
Whichever path you choose, the hardest part usually isn't deciding — it's remembering to actually follow through every single month. That's exactly why my Monthly Money Blueprint treats savings and debt payoff as their own line items, right alongside your bills, so the plan you make today doesn't get lost by week three. If you need a more in dept look into your debt payoff plan my Debt Freedom Tracker or Debt Payoff Calculator.
Shop the Monthly Money Blueprint and Debt Freedom Tracker
You don't need the perfect answer today. You just need a next step — and either one you choose is progress.
One day. One decision. A better future. ♡