
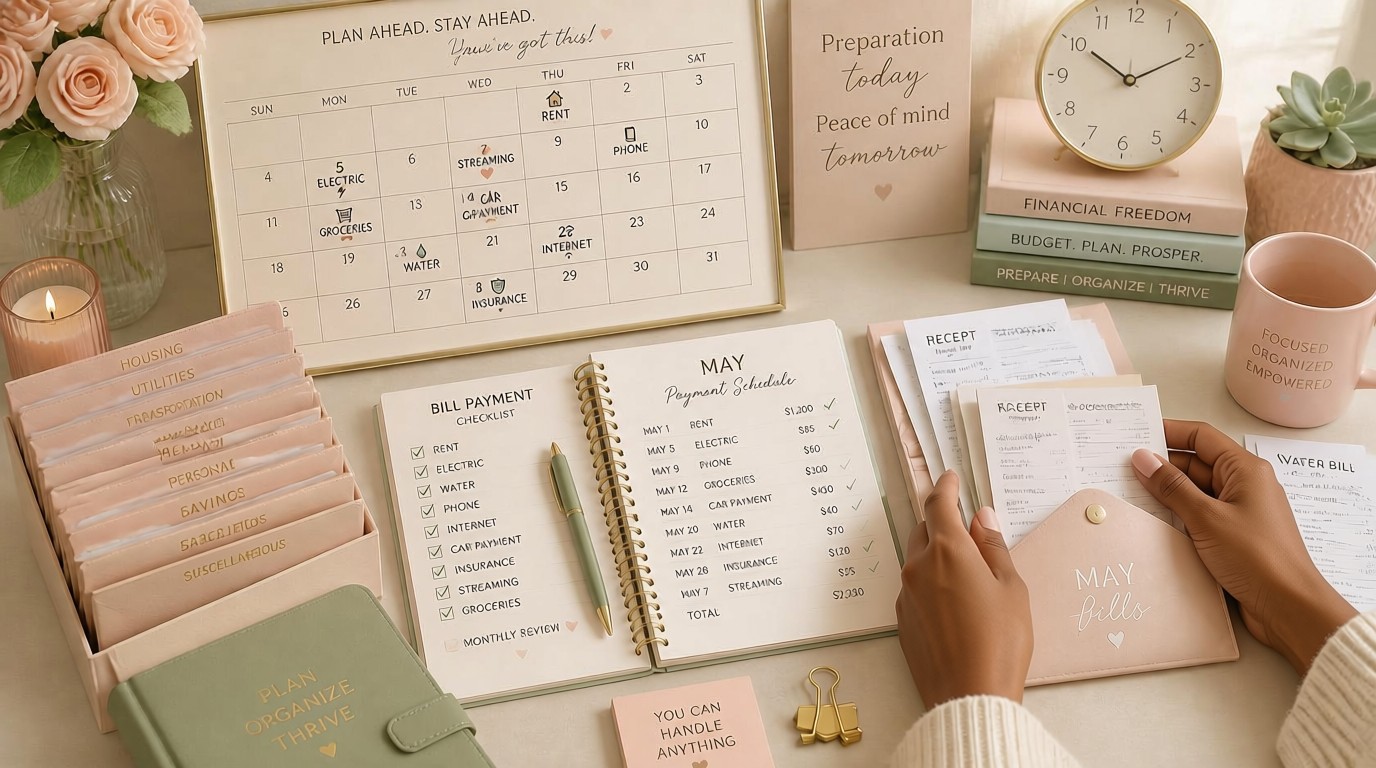
Every month, before a single bill is due, I already know exactly what's coming, when it's due, and whether it's handled. Not because I have a special gift for numbers — because I built a system that does the remembering for me, so my brain doesn't have to.
I get asked all the time how I actually plan my bills using my Monthly Money Blueprint planner, so today I'm pulling back the curtain a little. But more importantly, I want to give you the framework behind it — because whether you use my planner or a plain notebook, the categories and the thinking are what actually change your month.
How I Set It Up
The first thing I did — and the thing that saved me the most time going forward — was build a default list of bills once, instead of rewriting my bills from scratch every single month.
My defaults look something like this:
- Rent / Mortgage
- Electric / Gas
- Internet / Phone
- Car / Transport
- Insurance
- Subscriptions
- Savings / Invest
That last one isn't a mistake — I treat my savings transfer exactly like a bill. It has a due date (payday), and it gets paid just like everything else. Nothing about it is optional, and putting it on the same list as my rent is what finally made it stick.
Every month, that list carries forward automatically. I'm not rebuilding my bill sheet from a blank page — I'm just checking in and adjusting the amounts if something changed. Some months are simply the template as-is. Other months — say, a higher electric bill in August — I make a one-time adjustment just for that month, without touching my default plan going forward. That one shift alone is what took my bill planning from a 45-minute chore to a five-minute check-in.
How to Figure Out Your Own Categories
Here's the part that matters more than any tool: your bill categories should reflect your actual life, not a template you copied from someone else.
Start with these three questions:
- What comes out of my account on a fixed schedule? List everything that hits your account like clockwork — rent, insurance, subscriptions, loan payments. If it's the same amount (or close to it) every month, it belongs here.
- What would hurt if I missed it? This isn't about size — it's about consequence. A missed subscription is annoying. A missed rent payment is a crisis. Order your categories with this in mind, because it tells you what gets protected first when money is tight.
- What am I currently tracking in my head instead of on paper? This is usually the category people forget — car maintenance funds, annual memberships, that one quarterly bill that always seems to "sneak up." If you're mentally tracking it, it deserves its own line.
Once you have your list, put it somewhere it can live permanently — not scribbled fresh every month, but sitting there ready for you to simply glance at and adjust. That single shift, from rebuilding to reviewing, is the entire secret.
A Small Habit With a Big Payoff
The month I stopped rebuilding my bill list from scratch was the same month I stopped feeling behind.
There's a specific kind of calm that comes from opening your planner and seeing everything already there, waiting for you to just confirm it instead of recreate it.
That's not really about the tool. That's about giving yourself permission to build something once and let it hold you steady, instead of proving your discipline all over again every thirty days.
If You Want a Home for Your Bills Too
If you've been managing your bills from memory, sticky notes, or a fresh page every month, my Monthly Money Blueprint was built for exactly this — a bill list that carries forward automatically, with room to adjust any single month without losing your defaults. It's the same system I use myself, month after month.
Shop the Monthly Money Blueprint →
You don't have to reinvent your bill list every month. Build it once. Let it hold you.
Discipline today. Freedom tomorrow. ♡