
Small Business CGT Concessions Checker (Australia) – Eligibility, 15-Year Exemption, 50% Active Asset Reduction, Retirement Exemption, Rollover and CGT Cap (Excel)
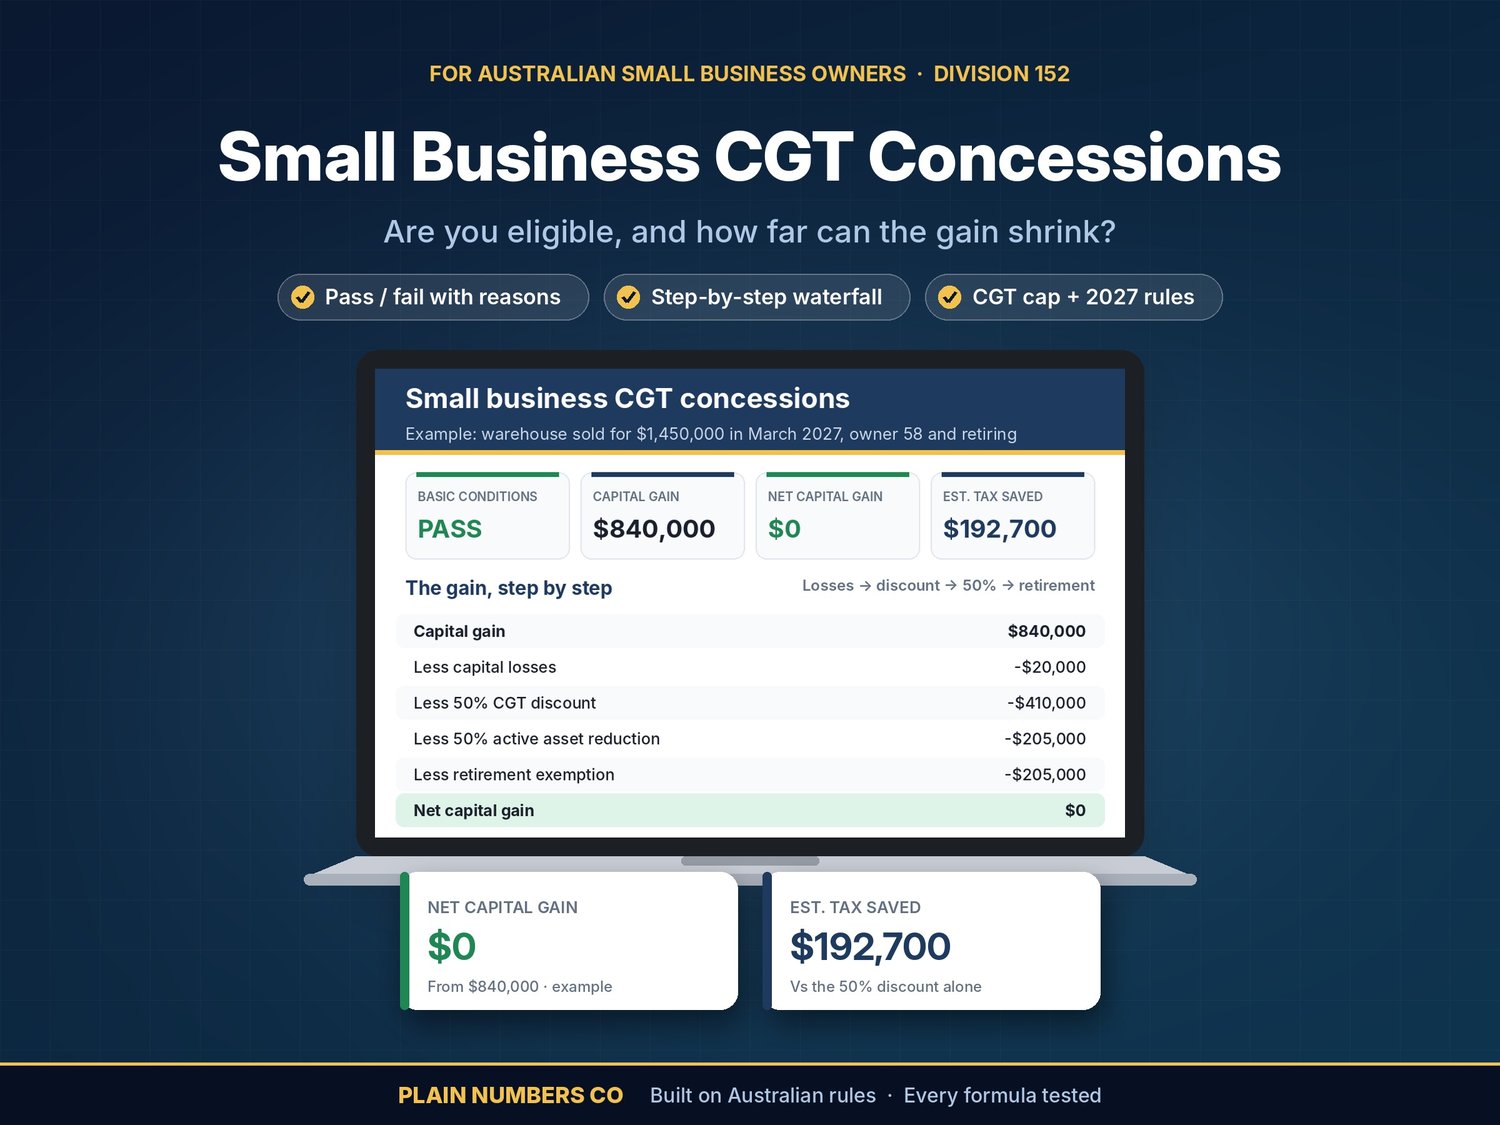
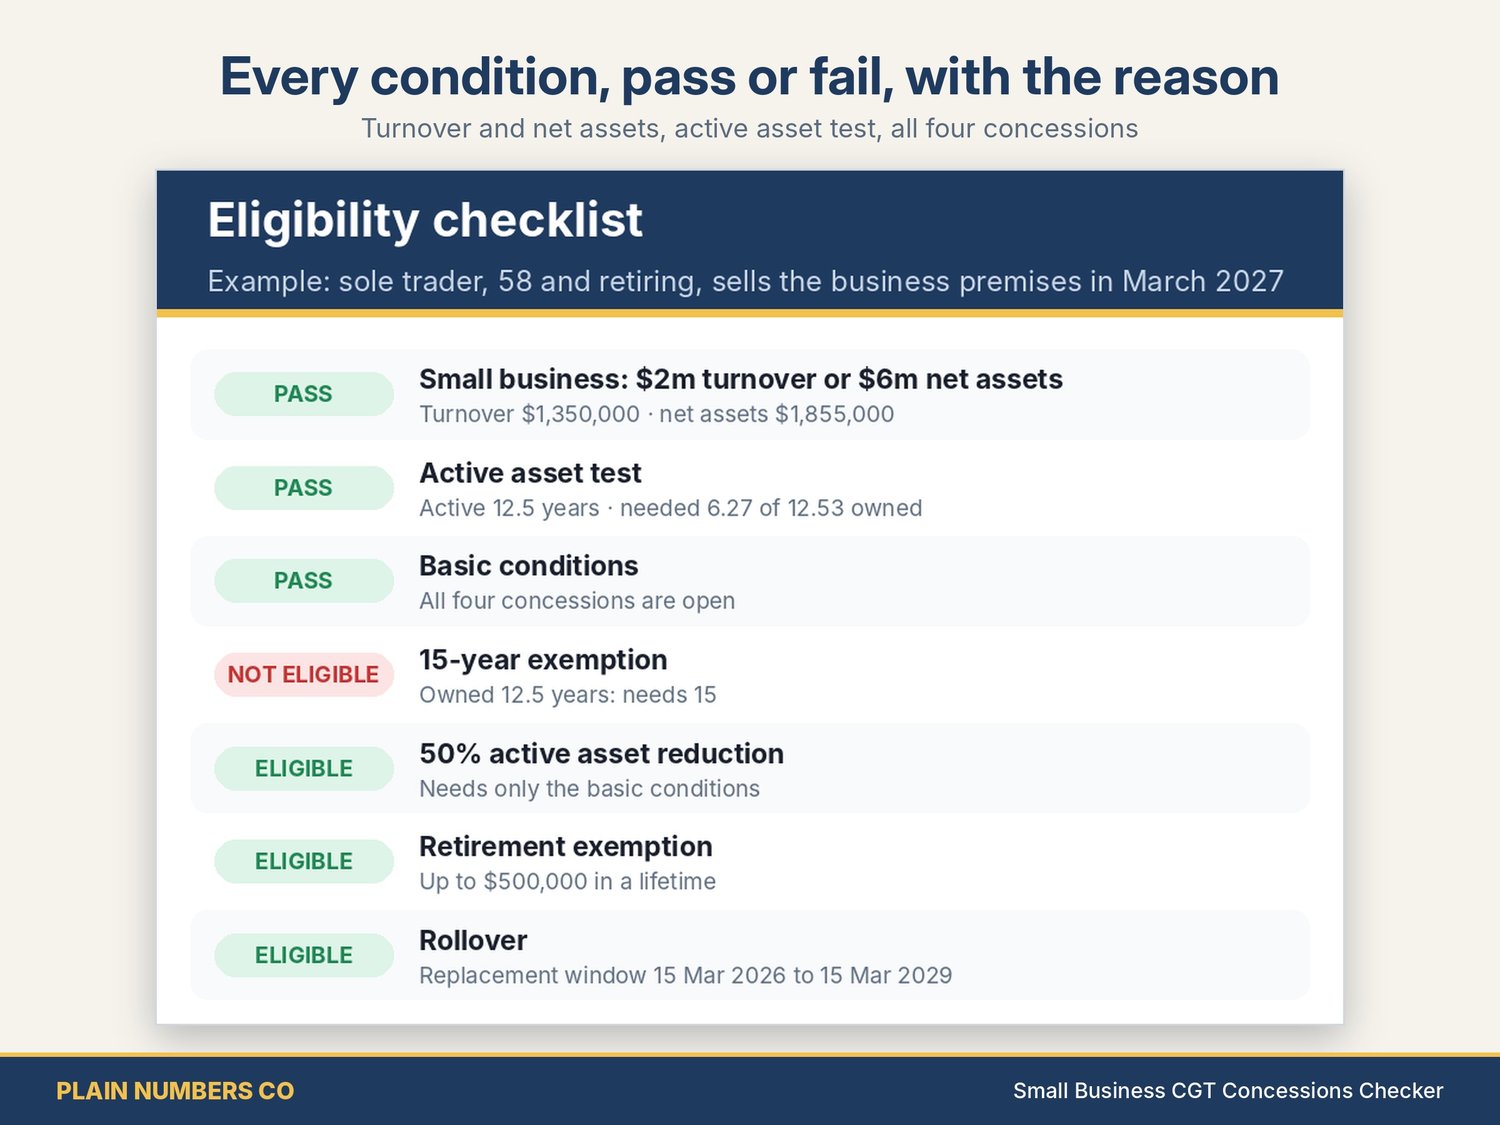
Find out whether your business sale qualifies for the small business CGT concessions, which ones apply, and how far they cut the gain: every condition is marked PASS or FAIL with the reason, then the gain is reduced step by step in the order the law applies the concessions, down to the net capital gain you report. It also shows what must (or can) go into super and how much of your lifetime CGT cap that uses.
Enter the sale, the business's turnover, your net assets, how long the asset was used in the business, and your age. The workbook shows:
- The basic conditions (Division 152): the $2 million aggregated turnover test or the $6 million net asset test, with a net assets worksheet that counts connected entities and affiliates and leaves out your home's private use, super, personal-use assets and life insurance. Then the active asset test (half the ownership period, or 7.5 years if owned more than 15 years), including the rule for selling within 12 months after the business stopped.
- Shares or units in your company or trust: the extra conditions, including the 20% significant individual / CGT concession stakeholder test, the 90% test, the company or trust's own turnover or net asset test, and the 80% test.
- The four concessions, with the reason each applies or doesn't: the 15-year exemption (owned 15 years, 55 or over and retiring, or permanently incapacitated), the 50% active asset reduction, the retirement exemption ($500,000 lifetime limit, with the under-55 super rule) and the rollover (replacement period 1 year before to 2 years after the sale, with the J5 and J6 traps flagged).
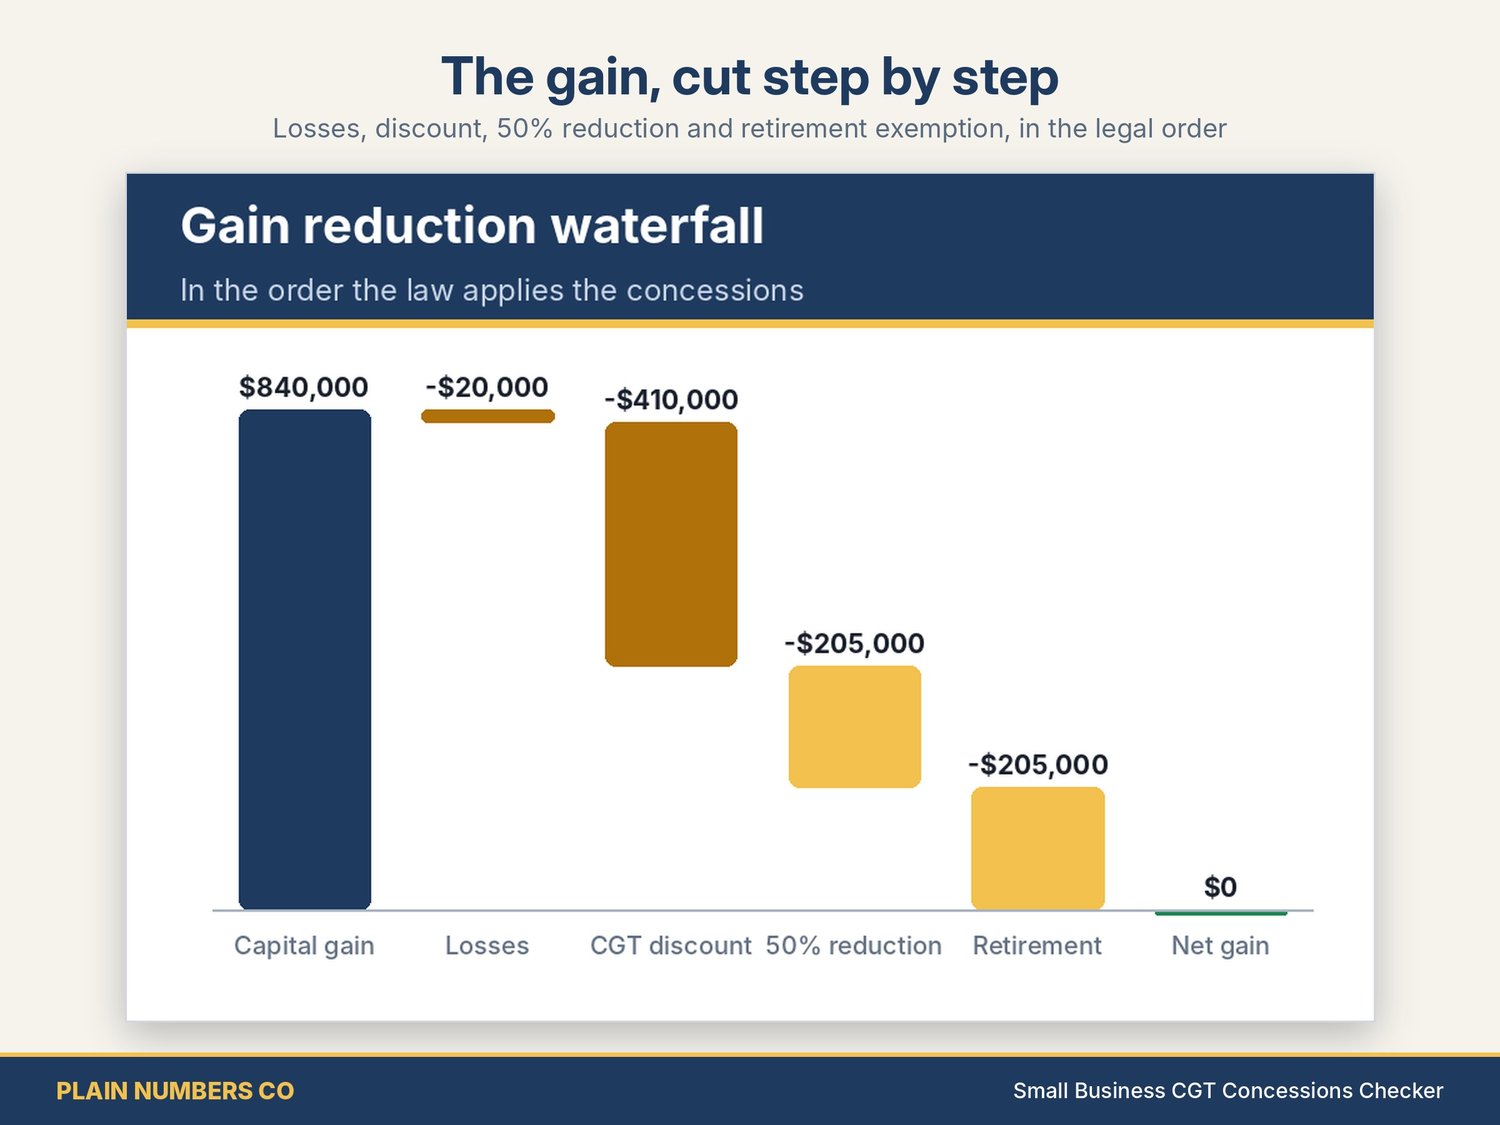
- A step-by-step gain reduction waterfall: 15-year exemption first, then capital losses, the 50% CGT discount, the 50% active asset reduction, the retirement exemption and the rollover. It shows the losses you keep, the net capital gain and an estimate of the tax saved.
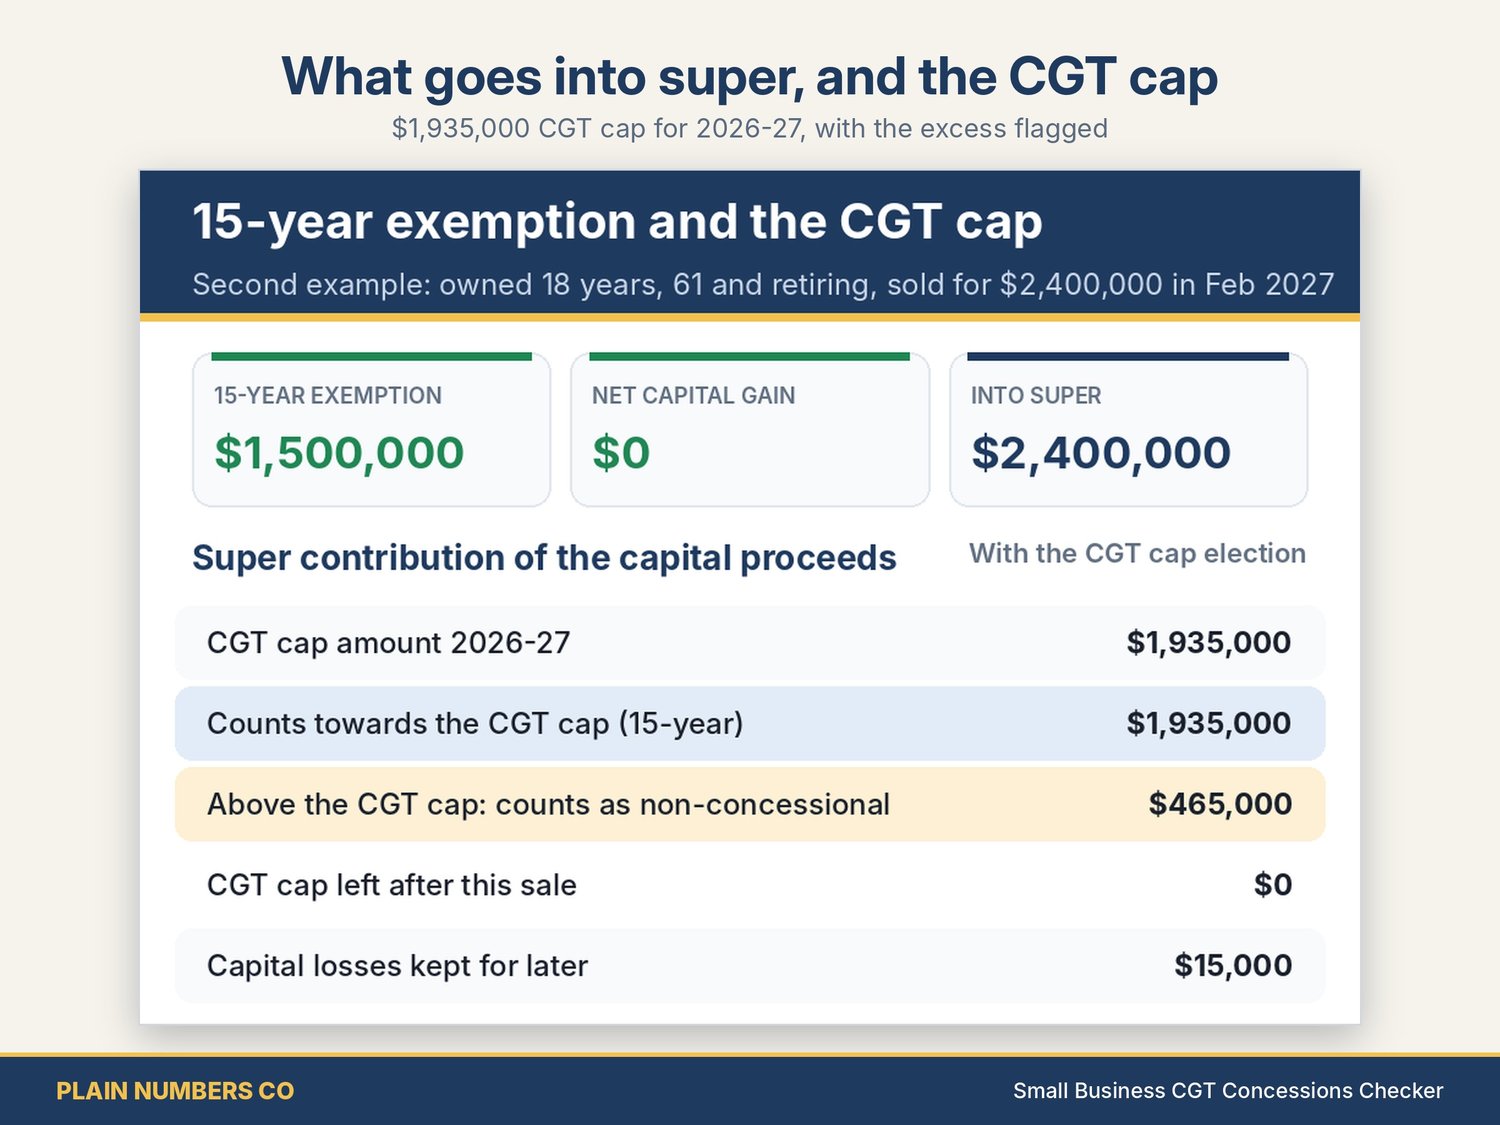
- Super and the CGT cap: the contribution from the 15-year exemption (up to the capital proceeds) and the retirement exemption, how much counts towards the CGT cap ($1,935,000 for 2026-27) with the election form, and what spills into your non-concessional cap.
- Sales on or after 1 July 2027: as the ATO describes the Treasury Laws Amendment (Tax Reform No. 1) Act 2026, the gain is split at 1 July 2027 (the 50% discount on the part before, cost base indexation after), the four concessions stay, and the 50% active asset reduction uses the $10 million turnover limit from 2027-28. Anything not yet law (such as the apportionment method) is labelled as not legislated. The 30% minimum tax is explained but not calculated.
- A plain-English summary and 12 automatic checks.
Includes: Home, Dashboard, Your Details, Net Assets, Eligibility, Waterfall, Super & CGT Cap, Summary, 2027 Changes, Rules & Rates, Checks and Notes & Sources. Notes & Sources lists every official link and the date it was checked. Example figures are filled in. Works in Excel and also opens in LibreOffice.
Built and checked by a CPA. Every formula tested against a separate calculation.
Designed by Plain Numbers Co with the help of AI tools. Listing images are designed previews of the actual file.
30-DAY MONEY-BACK GUARANTEE: if it doesn't work for your situation, message us within 30 days. We'll fix it, or refund you in full if you'd rather. This is in addition to your rights under the Australian Consumer Law, which are not excluded.
General information only, not tax or financial advice. This workbook does not consider your objectives, financial situation or needs. The small business CGT concessions have many conditions and choices: speak to a registered tax agent before you sign a contract, choose a concession or lodge a return.