
If you're staring down more than one debt right now — a credit card here, a car loan there, maybe a store card you forgot you even had — you already know the real question isn't should I pay these off. It's which one first?
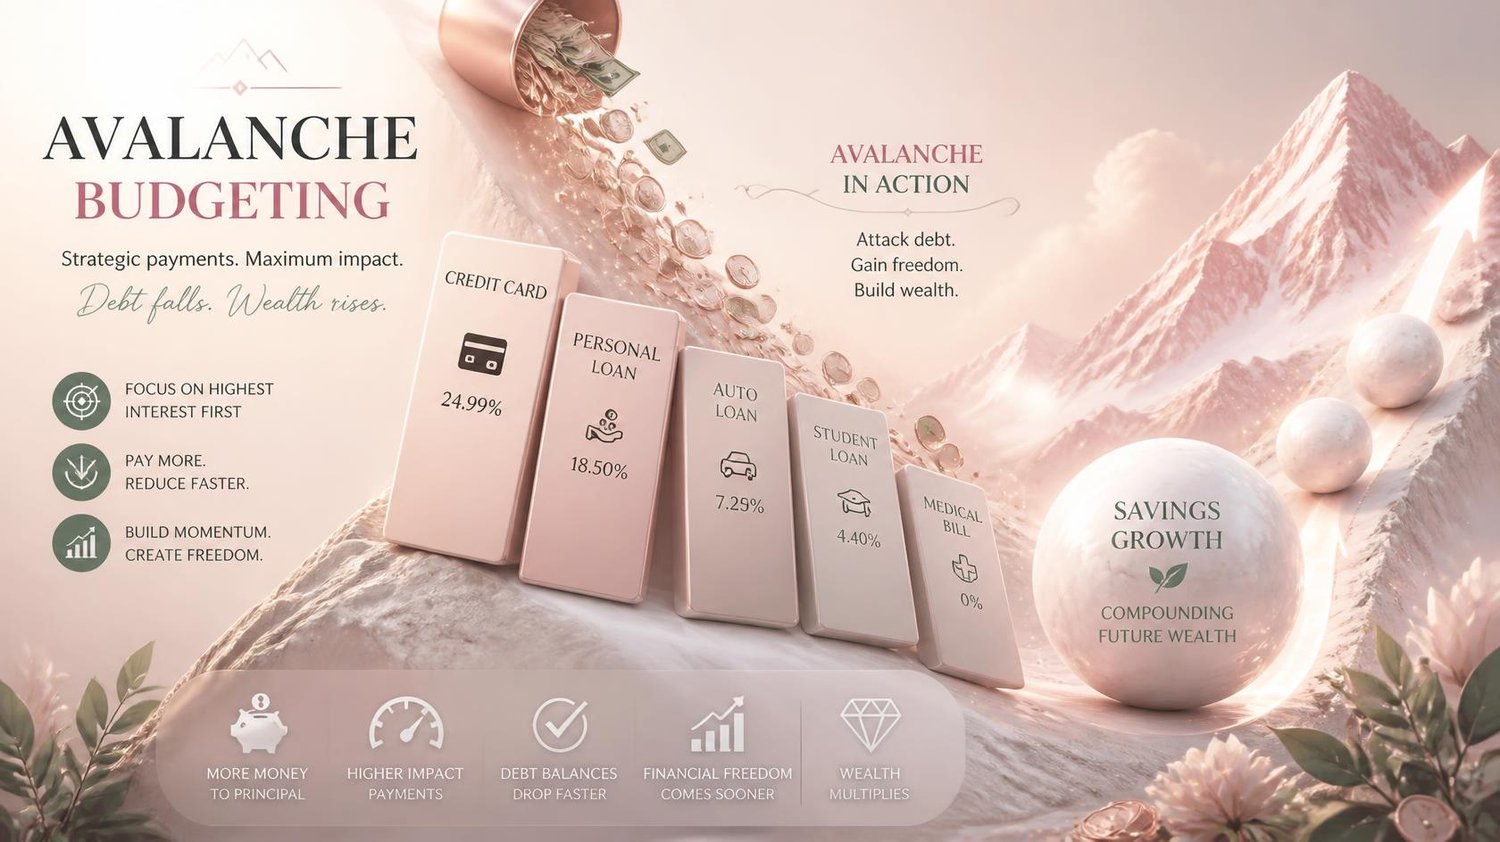
There's a method for that, and it has nothing to do with which balance feels the scariest. It's about which debt is costing you the most money every single month it stays alive: the debt avalanche method, and it's built entirely around one number — interest.
The Idea in One Sentence
Pay the minimum on every debt you owe, and put every extra dollar you can toward the debt with the highest interest rate first. Once that one's gone, roll everything you were paying on it into the next-highest-interest debt. Repeat until you're free.
That's the whole strategy. Deceptively simple — and mathematically the fastest, cheapest way out of debt there is.
Let's Make It Real
Say you're carrying three balances:
- Credit Card A: $3,000 balance - 24% interest
- Store Card: $1,200 balance - 27% interest
- Car Loan: $8,000 balance - 6% interest
A lot of us would instinctively want to knock out the Store Card first — it's the smallest number, and paying it off feels like a fast win. But look at the interest rate: 27%. Every month that balance sits there, it's quietly growing faster than almost anything else you owe.
With the avalanche method, the Store Card does get attacked first — not because it's small, but because it's the most expensive debt you have. Every extra dollar goes there until it's gone. Then that same extra dollar rolls into Credit Card A. The car loan, sitting at a comparatively gentle 6%, waits its turn.
The result: less of your hard-earned money goes to interest, and more of it actually shrinks what you owe.
"But What About the Debt Snowball?"
You may have heard of the other popular method — the debt snowball, where you pay off your smallest balance first regardless of interest rate, for quick emotional wins.
Here's the honest answer: the snowball is better for motivation. The avalanche is better for your wallet. If you know you need fast, visible progress to stay motivated, the snowball isn't wrong. But if you can stick with a plan even without those early wins, the avalanche will almost always save you more money — sometimes thousands of dollars — over the life of your payoff.
Only you know which kind of motivation keeps you going. Neither choice is a failure.
How to Start This Week
- List every debt you owe, along with its balance and interest rate.
- Order them from highest interest rate to lowest — that's your payoff order.
- Keep paying minimums on everything else.
- Send every extra dollar you can to the top of that list.
- When it's paid off, don't stop — roll that payment straight into the next one.
That last step is what makes this method so powerful. Your payoff speed actually increases with every debt you clear, because you're never adding new money to the plan — you're just redirecting what's already there.
Give Your Debt Payoff a Home
Once you know your order, the hardest part is often just staying consistent — remembering which debt gets the extra dollars this month, and tracking the balance as it drops. That's exactly the kind of clarity the Debt Payoff Calculator and Debt Freedom Tracker is designed to hold, right alongside your monthly Needs, Wants, and Savings — so your debt payoff plan isn't a separate project, it's built into the month.
Shop the Free Debt Payoff Calculator
Shop the Monthly Money Blueprint
You don't have to pay it all off today. You just have to know where the next dollar goes.
Discipline today. Freedom tomorrow. ♡