
Grubbs VA Guide VA Home Loan
🇺🇸 GRUBBS VA GUIDE
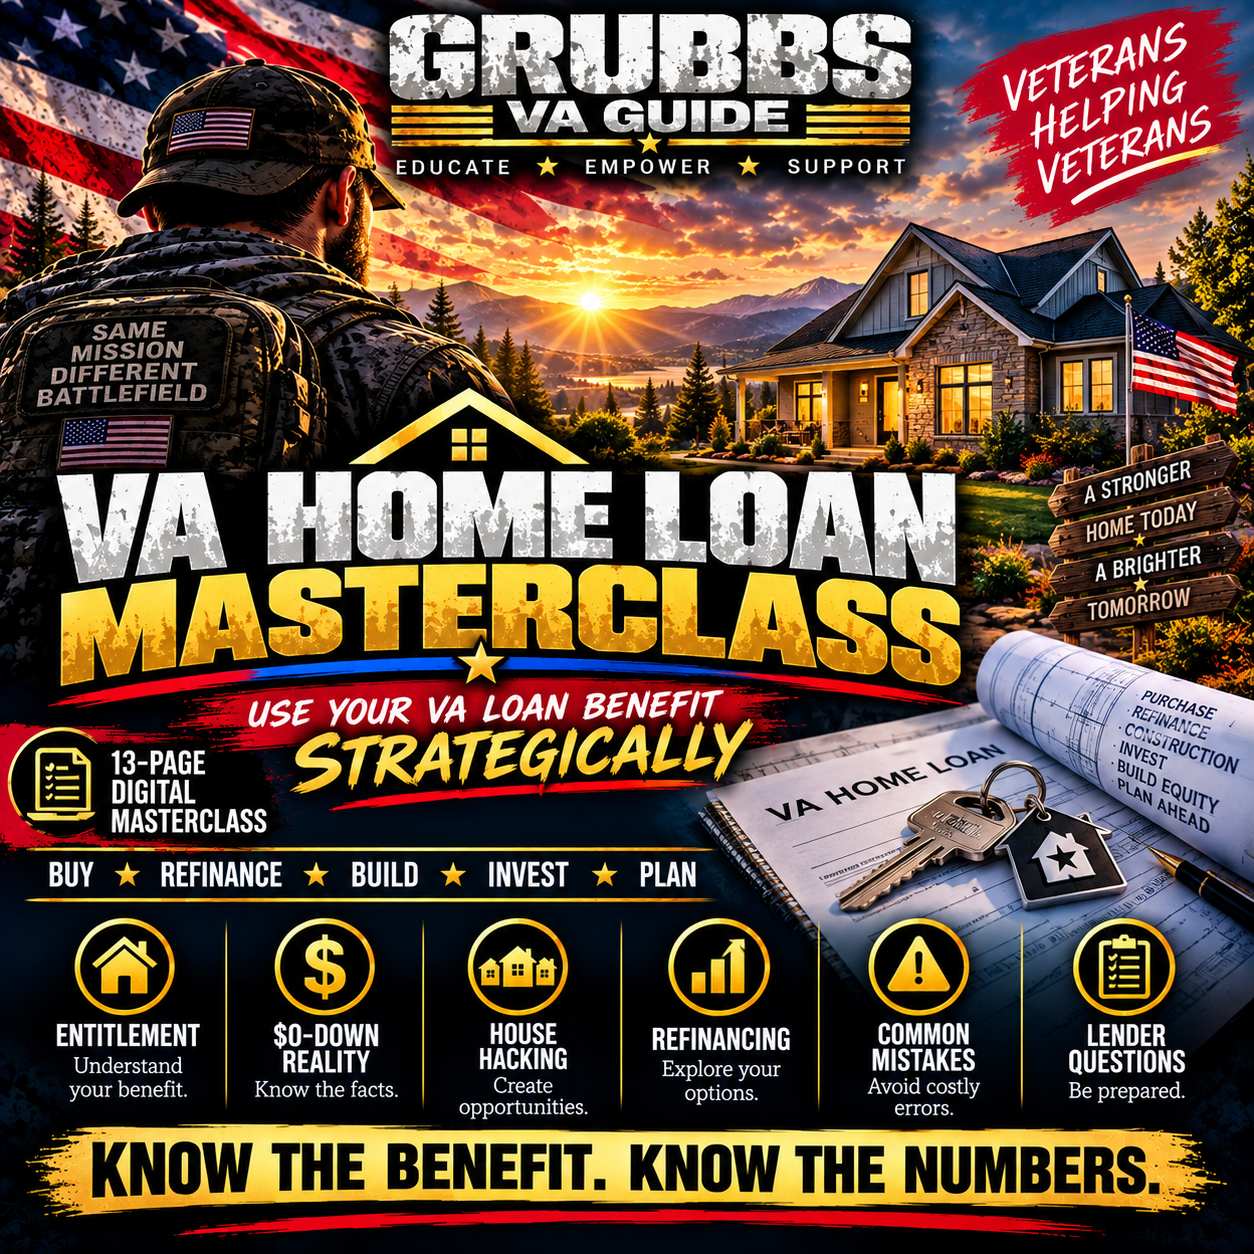
VA HOME LOAN MASTERCLASS
USE YOUR VA HOME LOAN BENEFIT STRATEGICALLY
Your VA home loan benefit can be more than just a way to buy a house.
But understanding how the benefit works, how entitlement works, what you can actually afford, and what your lender is charging can make a major difference.
The Grubbs VA Guide — VA Home Loan Masterclass is a practical 13-page digital guide designed to help Veterans understand the major VA home-loan strategies before making a major financial decision.
🏠 INSIDE THE MASTERCLASS
VA HOME LOAN BASICS
How VA-backed loans actually work
Eligibility and Certificate of Eligibility (COE)
What VA guarantees vs. what the lender decides
$0-down reality
PMI considerations
ENTITLEMENT
Basic entitlement
Remaining entitlement
Restored entitlement
Using your VA benefit again
Understanding second VA loans
BUYING A HOME
How much house you can actually afford
Credit, income and debt
Residual income
Taxes, insurance, HOA and maintenance
Cash-to-close considerations
Appraisal vs. inspection
HOUSE HACKING
Using a VA loan for a 2–4 unit property
Owner occupancy
Rental-income considerations
Real-world risks of becoming a landlord
BUILDING & CONSTRUCTION
VA construction financing
Construction-to-permanent loans
Builder requirements
Construction budgets and contingencies
REFINANCING
IRRRL
Cash-out refinance
Break-even analysis
Comparing refinance offers
Refinance red flags
AVOID COSTLY MISTAKES
Relying on the lender's maximum approval
Assuming "$0 down" means "$0 cash required"
Using only one lender
Ignoring funding-fee exemptions
Skipping an independent inspection
Misunderstanding entitlement
Falling for misleading refinance offers
BE PREPARED
13 questions to ask every VA lender
VA home-buying game plan
Home-loan planning worksheet
Loan comparison worksheet
VA Home Loan Master Checklist
The guide specifically emphasizes that eligibility is not the same as lender approval, and that Veterans should build their own sustainable housing budget rather than simply targeting the maximum amount a lender will approve.
VA confirms that eligible borrowers may use VA-backed loans to buy, build, improve, or refinance homes, subject to VA and lender requirements.
💰 KNOW THE BENEFIT. KNOW THE NUMBERS.
The VA home loan can provide powerful opportunities, but $0 down doesn't mean $0 cash required, and a lender's maximum approval isn't necessarily the right payment for your household.
This guide helps you think through the numbers before you sign on the dotted line.
🇺🇸 13-PAGE DIGITAL MASTERCLASS
BUY • REFINANCE • BUILD • INVEST • PLAN
⚠️ IMPORTANT
This guide is for educational and informational purposes only. VA eligibility, funding fees, loan requirements, interest rates, lender overlays, and other rules can change. Always verify current requirements with VA and your lender before making a financial decision. VA specifically recommends comparing lenders because rates, fees, and requirements can vary.
GRUBBS VA GUIDE
Educate • Empower • Support