
Downsizer Contribution Planner (Australia) – Excel
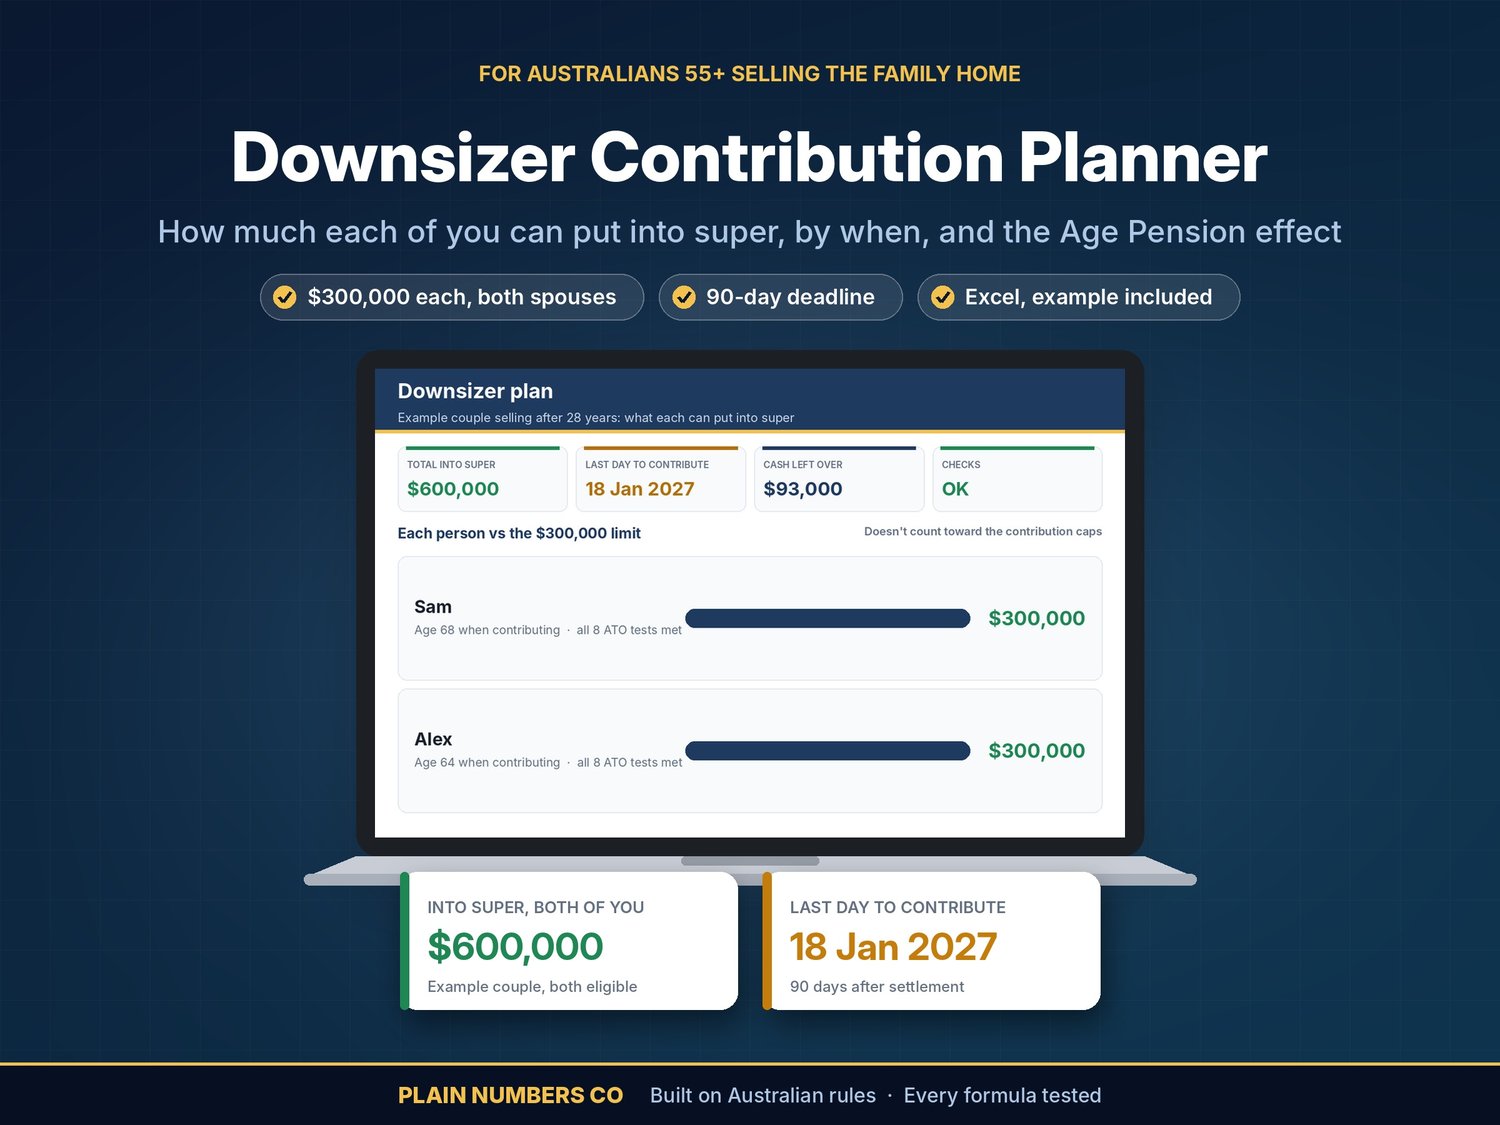
Selling the family home at 55 or over? Enter your sale, your dates and each person's details. The workbook tells you how much each of you can put into super as a downsizer contribution, the last day to do it, and what it does to your Age Pension under the assets test, compared with keeping the money outside super.
- How much each of you can contribute: up to $300,000 each, with both of you together no more than the sale proceeds. It uses the gross proceeds, because selling costs and the mortgage don't reduce the limit.
- Whether each of you is eligible. It checks the 8 conditions the ATO lists, person by person:
- aged 55 or over when you contribute;
- home owned for 10 years or more;
- contracts exchanged on or after 1 July 2018;
- a home in Australia;
- a full or partial main residence exemption;
- no earlier downsizer contribution (it's a one-time scheme);
- contribution within 90 days of settlement;
- the downsizer form given to your fund.
- The rules that trip people up, shown plainly:
- A downsizer contribution doesn't count toward the concessional or non-concessional caps.
- It isn't tax deductible.
- It does count in your total super balance from the next 30 June.
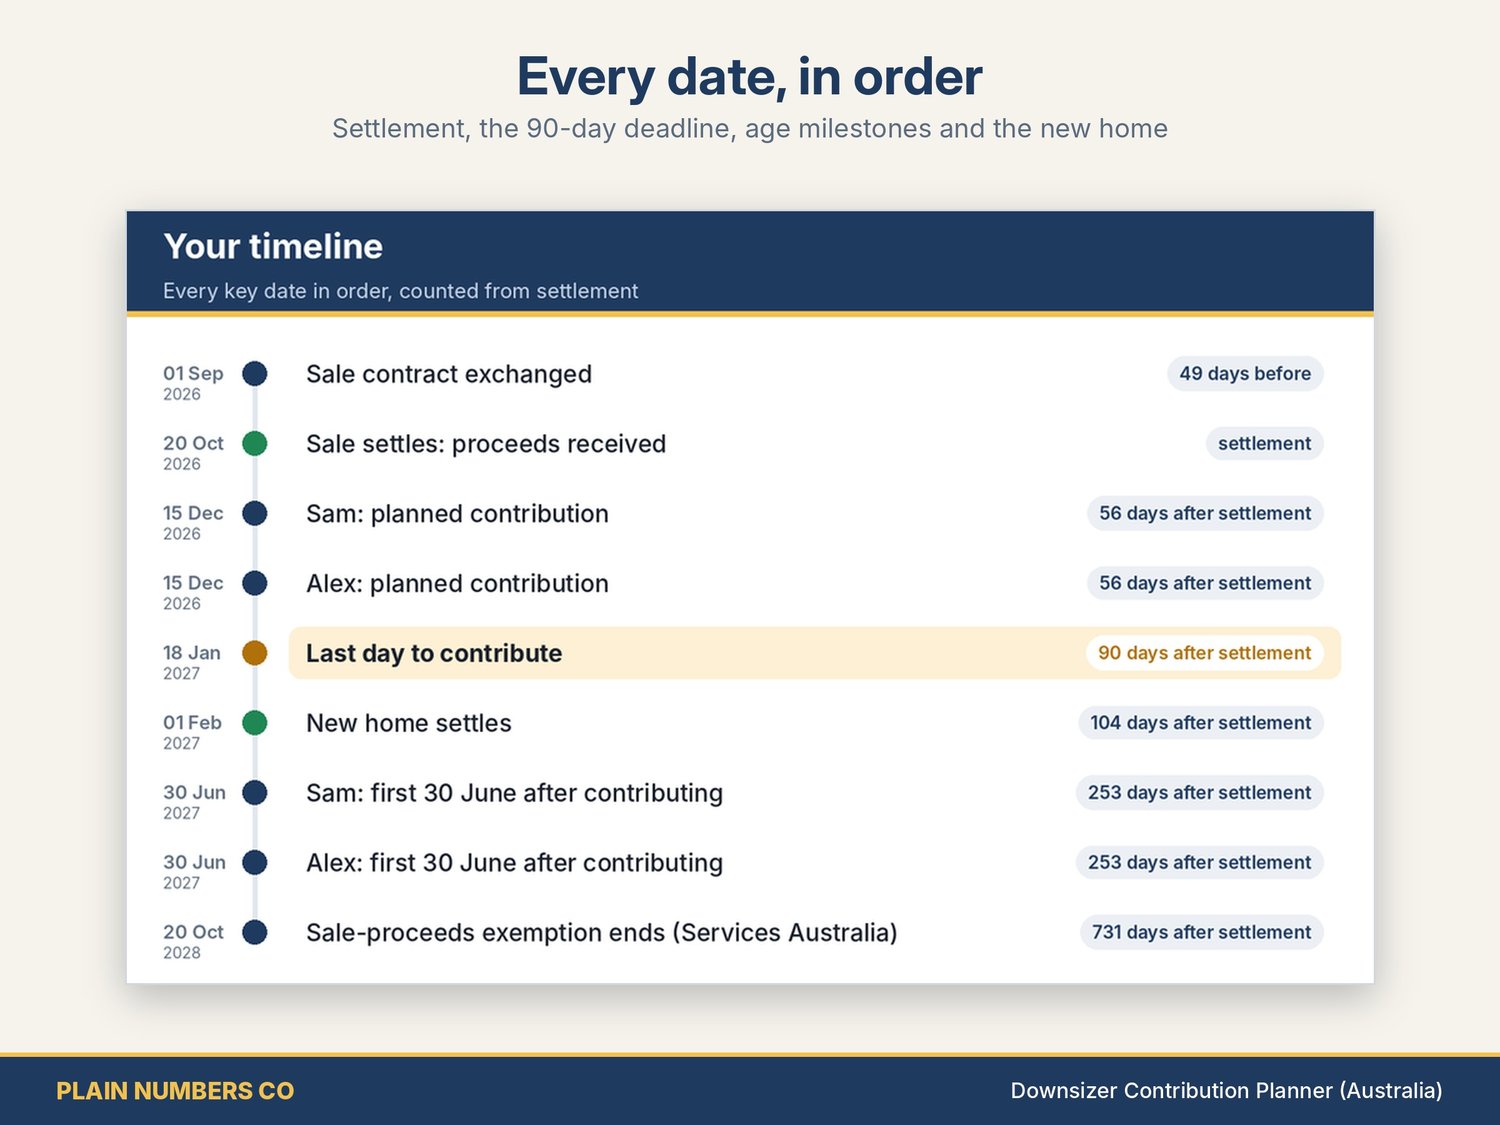
- Your timeline in date order:
- settlement and the 90-day deadline;
- 55th birthdays;
- planned contribution dates;
- the first 30 June after contributing;
- Age Pension age;
- the end of Services Australia's 24-month sale-proceeds exemption.
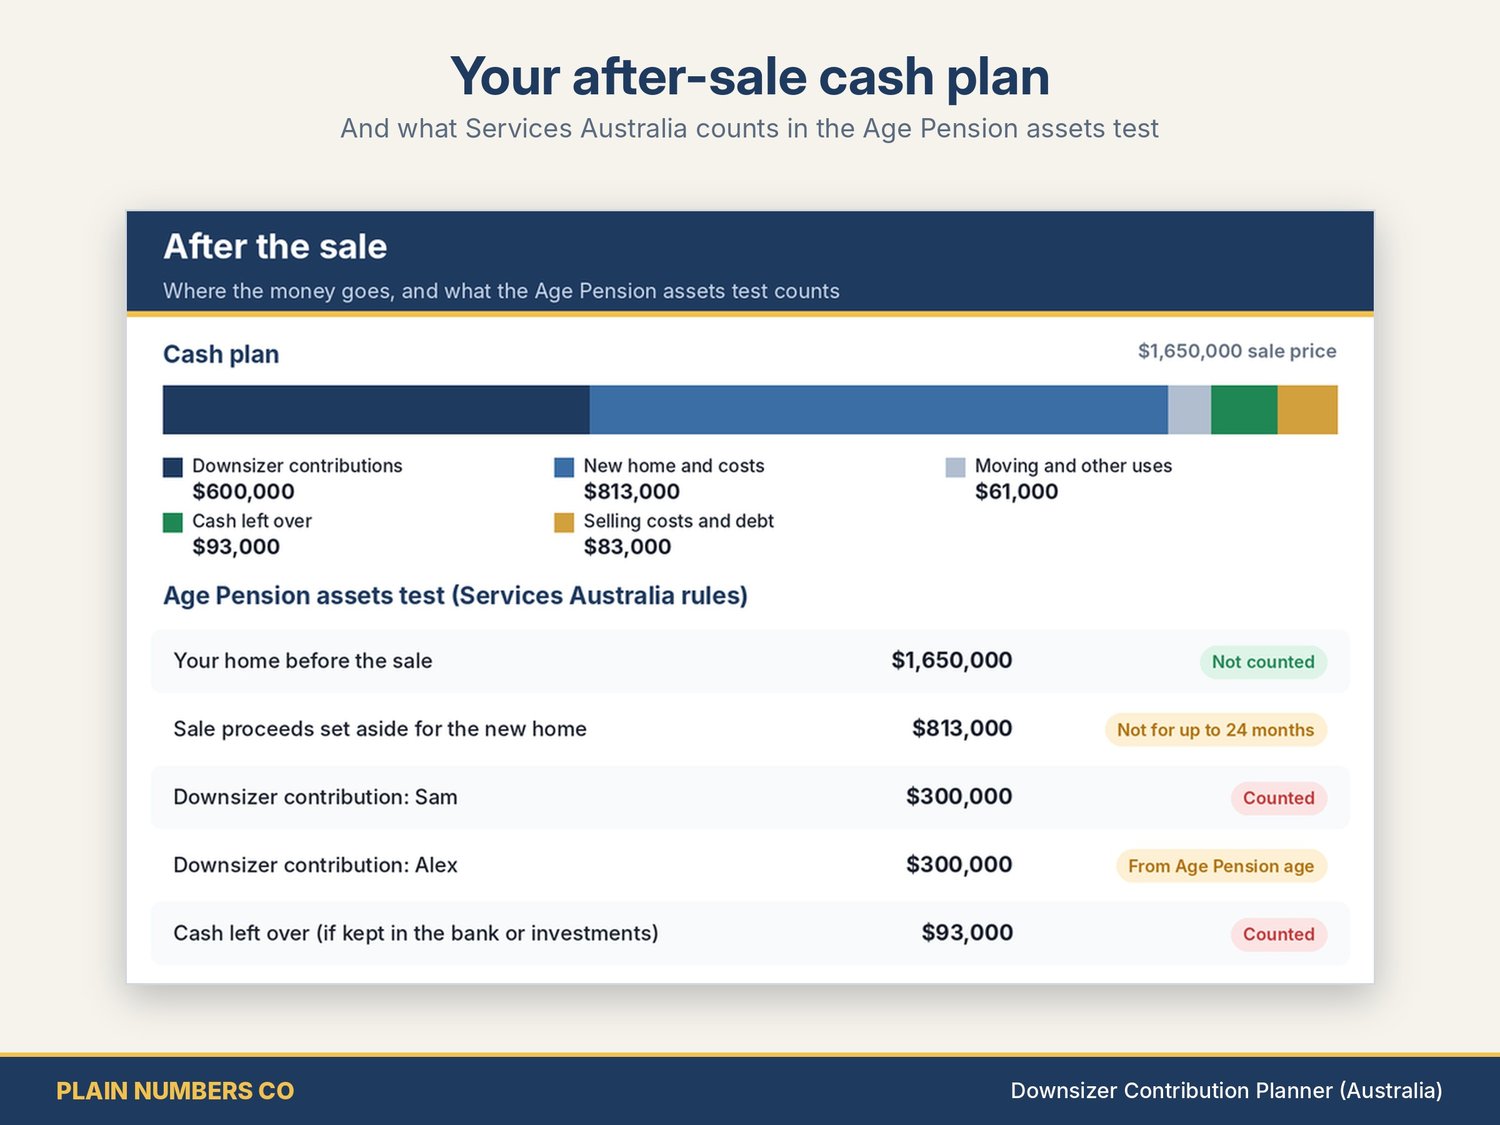
- Your after-sale cash plan: the sale price less selling costs and the mortgage, then contributions, the new home and its costs, and other uses. Shows the cash left over, or the shortfall.
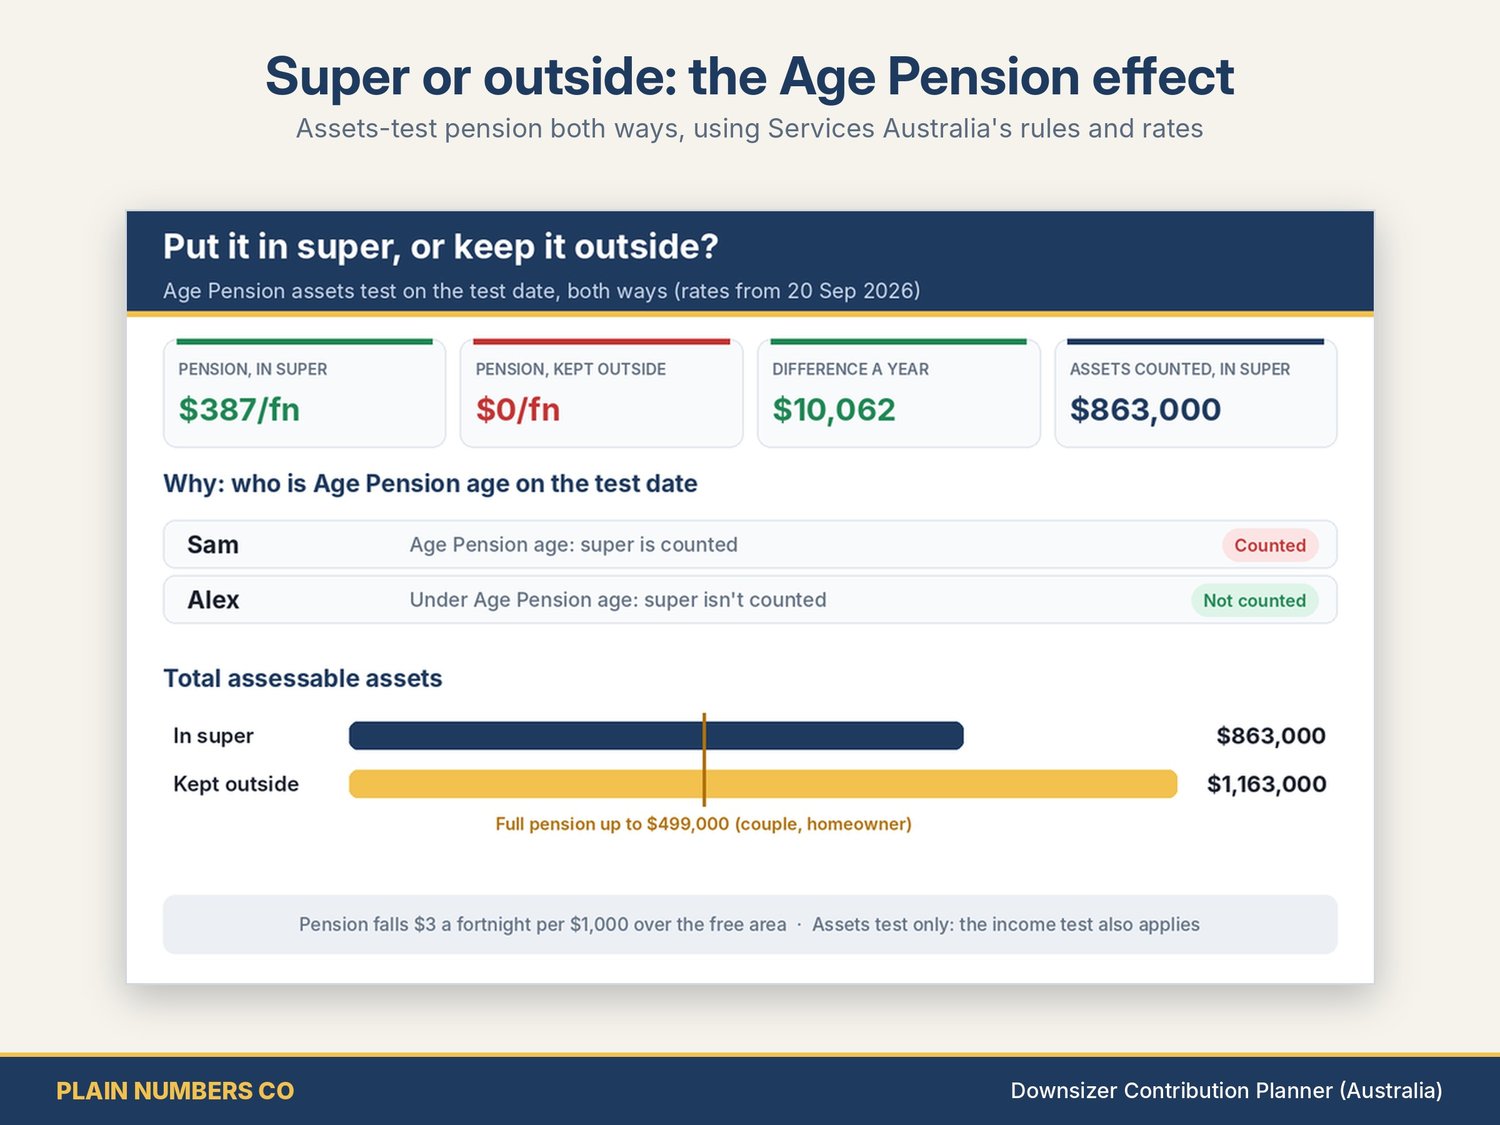
- Put it in super, or keep it outside? Your Age Pension under the assets test, both ways, on a date you choose:
- It uses the 20 September 2026 rates and the 1 July 2026 limits.
- Super isn't counted until you reach Age Pension age; money in the bank is counted at any age.
- So contributing can raise your pension while one of you is younger, and makes no difference once you're both of age.
- It also compares growth over the years you choose: 15% earnings tax in super (nil in retirement phase) against your own tax rate outside super.
What's inside: Home page, Dashboard, Inputs, Eligibility, Contributions, Timeline, Cash Plan, Age Pension, Super or Outside, Checks, and Notes & Sources. Notes & Sources gives every rule and rate with the ATO, Services Australia or DSS page it came from and the date we checked it: 24 October 2026. An example couple is filled in so you can see how it works before typing in your own figures.
Works in Microsoft Excel and LibreOffice. Instant download.
Built and checked by a CPA. Every formula tested against a separate calculation.
Designed by Plain Numbers Co with the help of AI tools. Listing images are designed previews of the actual file.
30-DAY MONEY-BACK GUARANTEE: if it doesn't work for your situation, message us within 30 days. We'll fix it, or refund you in full if you'd rather. This is in addition to your rights under the Australian Consumer Law, which are not excluded.
General information only, not tax, financial or legal advice. It doesn't consider your personal circumstances. The Age Pension figure is the assets test only; Services Australia also applies the income test and pays the lower amount. Check with your super fund, the ATO, Services Australia or a licensed financial adviser before acting.